Why Most Mid-Market Consulting Firms Plateau and How Taylor Company Broke Through
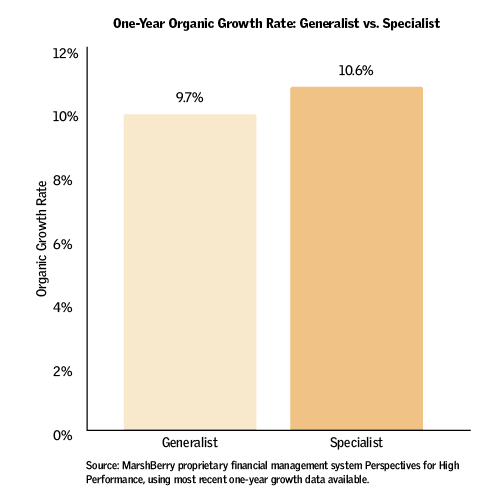
I spent about six years running strategy engagements for firms in the 30-to-80-consultant range, and I can tell you that the growth ceiling for these organizations is usually structural, not talent-related. They hit a wall around $15 million to $25 million in revenue and then spend the next decade slowly grinding toward $50 million with diminishing returns. Taylor Company is one of the few examples I've seen where leadership made a deliberate, unpopular decision to compress their service offering into a single vertical and accept short-term revenue sacrifice for long-term moat-building. The firm started around 2012 doing generalist management consulting—basically everything from operational improvement to org design to technology implementation for mid-market clients across healthcare, manufacturing, and professional services. They were profitable but stuck. Revenue growth hovered around 8 to 12 percent annually, and they couldn't seem to move above roughly $18 million without either over-hiring or discounting heavily to fill the pipeline. The turning point came when the managing partner, who had a background in healthcare operations, pushed to shut down three of the firm's four practice areas and focus exclusively on health system operational transformation. The partners who weren't onboarded on that direction left within eighteen months. Revenue dropped about 22 percent in the first year because they lost two major manufacturing clients and a professional services engagement. That's the part most case studies gloss over. The dip was real and it was uncomfortable.
What happened next is where the specificity matters. Rather than just rebranding, they rebuilt their delivery model around a repeatable framework for value-based care transition projects. Instead of billing by the hour or by phase, they structured engagements around outcomes tied to specific efficiency metrics. This let them charge premiums that generalist competitors couldn't match because the clients perceived them as the only firm that actually understood the regulatory and operational nuances of that particular work. By year four after the pivot, they were doing over $52 million in revenue, up from roughly $14 million at the nadir. The mechanism behind that growth wasn't simply being the only player in a narrow space. It was the compounding effect of three specific advantages that niche specialization unlocks when you actually commit to it rather than just choosing a narrow marketing message while still accepting work outside your stated expertise. First is what I call the delivery learning curve. When you run the same type of engagement repeatedly, even across different clients, your team develops shortcuts and templates that aren't obvious to outsiders. Taylor Company reported that their average project duration shrank by about 35 percent between year one and year three post-pivot, not because the work got easier but because they stopped reinventing the wheel on each engagement. Their diagnostic phase went from a three-week custom assessment to a two-week standardized workflow with a validated data intake template. That margin improvement on delivery is where the profitability jump came from.
Second is referral velocity. In specialized consulting, word of mouth operates differently than in generalist work. Health system executives talk to each other through very narrow channels—healthcare-specific conferences, peer networks, and board appointments. Once Taylor Company landed a referenceable win with a regional health system, the referrals came from people who already trusted the referrer. This cut their sales cycle dramatically. A typical RFP response that would have taken six weeks for a generalist firm dropped to about twelve days for them because the initial outreach was often an introduction from a current client rather than a cold bid. Third is pricing power, which is the least talked about but probably the most important factor. When you're a generalist, your pricing competes on the bottom of every RFP. When you're the known specialist in a vertical, you can price above market rate and clients still choose you because the perceived risk of going with a generalist who might stumble on domain-specific landmines is higher. Taylor Company moved from blending rates in the $225-to-$275 range to a blended rate closer to $340 within two years of the pivot. That's not inflation—that's structural. Here's where it gets complicated and where the approach doesn't work for every firm. Niche specialization has real downsides that people don't talk about enough. The first is demand cyclicality. If your niche contracts, you contract hard. Taylor Company's health system focus meant they were exposed to healthcare spending cycles and policy shifts. When value-based care reimbursement models stalled in certain markets during 2019 and 2020, their pipeline dried up faster than a diversified firm would have experienced. They had to lean on existing client renewals and referral relationships to bridge that gap, which required maintaining a higher cash reserve than most mid-market firms carry.
Get the Full Details
The second downside is talent recruitment and retention. Specialists are harder to find and more expensive to hire. Taylor Company struggled for about eighteen months to replace consultants who left after the pivot because their brand had shifted from a broad consulting platform to a healthcare-focused shop. They had to adjust their recruiting language, target candidates from healthcare operations backgrounds rather than traditional MBA programs, and accept that their hiring funnel was narrower. This slowed their delivery capacity during a period when demand was actually accelerating. A third practical limitation I want to flag is the danger of niche complacency. Once you've carved out a specialty, there's a tendency to assume your depth protects you from newcomers. That's not always true. Larger generalist firms occasionally develop specialized arms precisely because the margins in niche work are attractive. I watched a Big Four firm launch a dedicated health system operations practice that directly competed with Taylor Company on a few key accounts. The advantage Taylor had was institutional knowledge and relationship depth, but on commoditized components of those engagements, the larger firm could underprice them significantly. This forced Taylor Company to continually elevate their positioning toward strategic advisory rather than operational execution, which required investment in senior talent they might not have otherwise pursued. I encountered a specific edge case while advising a firm that was considering a similar pivot. They were in industrial manufacturing and wanted to narrow down to a sub-segment—something like packaging operations. The problem I ran into was that their target niche was too small to support their cost structure. The total addressable market in their region for that specific work was perhaps eight to ten meaningful engagements per year, and each engagement averaged around $400,000 to $600,000. Even at a 30 percent win rate, that's two to three new projects annually, which wouldn't cover their overhead. I recommended they broaden slightly to allied verticals within industrial operations—something like packaging and logistics integration—rather than going fully narrow. The compromise lost them some of the pure specialization premium but preserved enough market size to make the model viable. This is the kind of calculation most firms get wrong because they optimize for positioning clarity rather than unit economics.
The implementation steps for a firm considering this path are deceptively straightforward but practically difficult. You need to identify which of your current or past engagements generated the highest margins, the strongest client satisfaction, and the most natural referral potential. Then you assess whether that segment has enough total addressable market to support your revenue targets. After that, you make the commitment—shutting down or outsourcing work outside the niche—and you rebuild your marketing, recruiting, and delivery around it. The hardest part is the commitment itself. Most firms dabble in specialization without actually committing, which means they keep taking generalist work that dilutes their brand and prevents them from building the deep expertise that justifies premium pricing. If you're looking at this from an investment or partnership perspective, the key metrics to track during the transition are gross margin per engagement, average sales cycle length, referral rate as a percentage of new business, and client renewal rate. During Taylor Company's pivot, gross margin per engagement improved from roughly 28 percent to 41 percent within three years, average sales cycle dropped from eleven weeks to six weeks, and by year four, about 60 percent of new business came from referrals or repeat engagements. Those are the numbers that matter, not the headline revenue figure. The approach works best for firms that already have some depth in a particular vertical and are hitting the generalist ceiling. It works less well for firms that are starting from scratch in a new niche or for those whose existing client relationships are deeply embedded in their current broader offerings. In those cases, a gradual adjacent expansion might be more appropriate than a full pivot.