(1).png?width=1520&height=1205&name=Taux de TVA en France (métropole) (1).png)
French VAT Rates Explained Without the Fluff
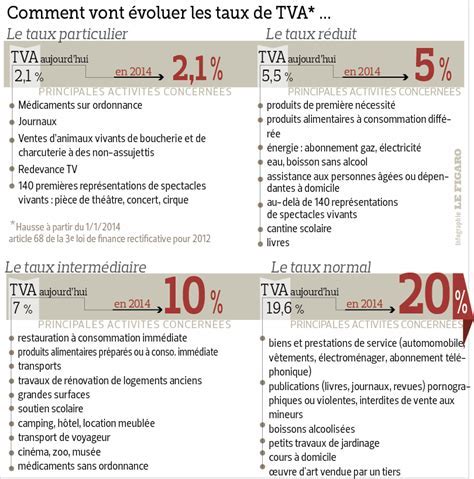
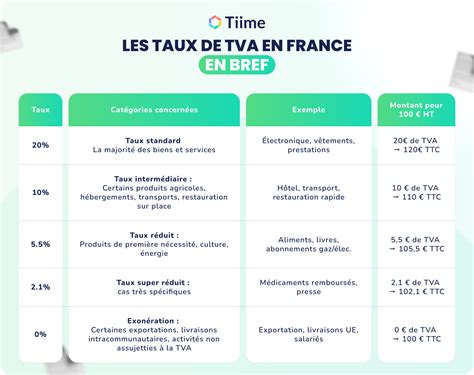
Taux Tva The Lowdown On French Vat Rates Simplified comes down to understanding that France doesn't just have one rate. It has four, plus a handful of special regimes that make even experienced accountants second-guess themselves on a good Tuesday. The standard rate sits at 20%. It applies to almost everything unless a specific law says otherwise. Restaurant meals, consumer electronics, private insurance premiums, most professional services. If you're selling B2B software to a French company, that's 20%. If you're importing textiles from Bangladesh into Marseille, that's 20% plus customs duties layered on top. I used to think the standard rate was straightforward. Then I worked with a client who imported cosmetic devices classified under CN code 8509. The customs brokers wanted to apply the 20% rate. But if those devices are purely cosmetic and not electrical, they can fall under a reduced category. We ended up getting them reclassified and paid the difference back in credits. Took six months and three emails to the DIRECCTE to sort out.
The Reduced Rates: 10%, 5.5%, and 2.1%
The 10% rate covers things like restaurant services (not alcoholic beverages), transportation of passengers, hotel accommodation, and certain agricultural inputs. The 5.5% rate applies to food products that aren't basic staples, books, energy supplies for residential use, and some cultural events. The 2.1% rate is the narrowest one - it covers newspapers, magazines, and certain pharmaceutical products reimbursed by social security. Here's where people mess up. The 5.5% rate on food isn't automatic. You have to prove the product falls within the specific categories listed in Article 278 sexdecies of the Code Général des Impôts. A lot of small retailers just apply 5.5% to everything that looks edible and get caught during audits. I've seen penalties hit 25% of the underpaid tax, plus interest calculated from the original due date.
Practical Application and Common Pitfalls
When you're issuing invoices as a French business, the VAT rate has to appear on every line item. Not just the total. This matters because clients can deduct input VAT based on what's shown on individual lines. If you lump everything under one rate when different products qualify for different rates, your client's accountant will flag it, and you'll end up correcting invoices retroactively. Reverse charge mechanisms also trip people up. If you're a non-French supplier selling services to a French business, the French client may need to self-assess the VAT through reverse charge. This doesn't change the rate itself - it stays at 20% for most services - but it shifts who accounts for it. I handled a case where a German web developer kept invoicing French clients without mentioning reverse charge. The French clients were deducting the VAT themselves, but their auditors caught it two years later. The German developer had to register for French VAT and pay back taxes plus penalties. Digital services deserve special attention here. Since 2015, the VAT location rule for B2C digital services follows the customer's location, not the provider's. So if you're based in Lyon and sell SaaS subscriptions to customers in Germany, you charge German VAT at 19%, not French 20%. You can register under the OSS scheme and file one quarterly return covering all EU customers instead of registering separately in every member state. Without OSS, you'd need registrations in potentially dozens of countries.
Get the Full Details
The Intrastat Question
If your intra-EU shipments exceed certain thresholds, you'll need to file Intrastat declarations. France has separate thresholds for arrivals and dispatches. For goods dispatched to other EU countries, the threshold is currently around 374,000 euros annually. Below that, you don't file. Above it, you file monthly declarations with detailed commodity codes. Getting the CN codes wrong here causes delays and sometimes fines, but it's a completely separate obligation from VAT filing itself. People conflate the two regularly. One thing nobody warns you about: the French VAT return deadline. It's the 15th of the month following the reporting period. For monthly filers, that means January 15th, February 15th, and so on. If the 15th falls on a weekend or holiday, it moves to the next business day. I've lost track of how many times a new bookkeeper misses this because they assumed it was the last day of the month. The penalty for late filing is 0.4% per month of delay, capped at 4% for delays under 4 months, then scaling up to 8% after 4 months. It compounds with interest at the official rate.
What the System Gets Wrong
The French VAT system isn't broken, but it has real bottlenecks. The biggest one is the complexity of the reduced rate catalog. It's scattered across multiple articles of the CGI, amended frequently, and interpreted differently by regional tax offices. A product classified at 5.5% in Paris might be challenged at 20% in Lille. There's no central database where you can look up whether a specific SKU qualifies for a reduced rate. You have to either build your own reference table or accept the audit risk. Another issue is the lag between rate changes and system updates. When France dropped the restaurant VAT from 10% to 5.5% temporarily during the pandemic, most accounting software needed updates within weeks. Small businesses using older systems or manual processes spent extra weeks recalculating invoices and correcting past returns. The tax office eventually granted a grace period, but the cleanup work was real. If you're running a small operation and doing this manually, consider software that at least validates VAT numbers through the VIES system for intra-EU transactions. Manual entry errors in VAT IDs cause rejected invoices and blocked deductions. The VIES check is free and takes about three seconds. Doing it by hand costs you time and exposes you to compliance gaps.
The bottom line is that French VAT follows clear rules but applies them through a labyrinth of exceptions. Learning the structure helps. Building a practical reference for your specific products or services helps more. And keeping records of your rate decisions with the legal basis cited makes audits significantly less painful.