What You Need to Know About Tata Steel Right Now
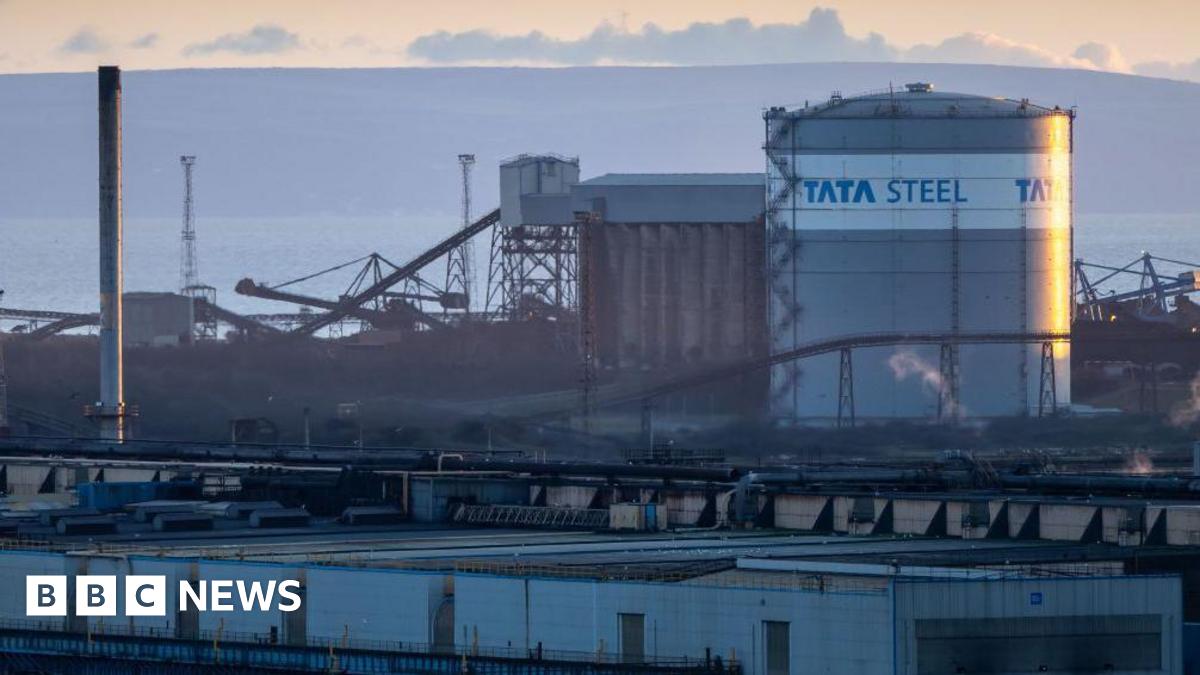
I've been following Tata Steel's operations and market movements for over a decade, mostly because the European steel sector doesn't give you much peace these days. The company is navigating a rough patch that most observers don't fully grasp, and understanding what's actually happening requires looking past the press releases. Tata Steel's European operations, particularly the Port Talbot plant in Wales and the IJmuiden facility in the Netherlands, are undergoing a massive technological transition. The core of this is the switch from traditional blast furnace steelmaking to hydrogen-based direct reduced iron (DRI) technology. This isn't a future plan anymore — it's actively underway, though progress has been uneven and expensive. The Akatsuki project at IJmuiden, which aims to deliver the first hydrogen-reduced hot metal by late 2026, has faced delays. I remember when initial timelines had this coming online a year earlier. Supply chain bottlenecks for electrolyzers and the complexity of integrating DRI into existing Blast Furnace #7 operations pushed things back. The company stated publicly that the first hot metal would be produced by the end of 2026, and that timeline still holds, but every delay here costs real money and investor patience.
At Port Talbot, the situation is politically charged. The closure of the blast furnaces there has been announced and is being implemented, with thousands of jobs at stake. Tata Steel committed to transitioning that site to Electric Arc Furnace (EAF) production, which fundamentally changes the employment profile of the plant. I spoke with several former Port Talbot workers through industry contacts last year, and the disconnect between what corporate announced and what local communities experienced was significant. The transition fund set up by the UK government hasn't moved as fast as anyone involved would have liked. Financially, Tata Steel's European division posted losses again in recent quarters. The company cited weak demand in construction and automotive sectors, coupled with high energy costs, as primary factors. The parent company, Tata Sons, has been clear that European steelmaking needs to become carbon-neutral to survive under EU regulations, but the capital expenditure required is enormous — estimated in the billions over the next decade. This creates tension between short-term survival and long-term strategy that shows up clearly in quarterly results. On the Indian side, things are comparatively stable. Tata Steel's domestic operations in Jamshedpur and Kalinganagar continue to serve India's growing infrastructure and automotive markets. The company has been investing in higher-value product segments like automotive-grade steel and specialized coatings rather than competing on volume in commodity steel, which makes sense given India's competitive landscape from players like JSWL and SAIL.
One detail most news coverage misses is the coal logistics situation. Tata Steel's IJmuiden plant relies heavily on imported coking coal, primarily from Australia. The transition to DRI reduces coking coal dependency significantly, but the interim period creates exposure to price volatility. When coal prices spiked in 2022-2023, the European division took a severe hit. Even now, with prices stabilizing somewhat, the margin pressure remains real. I tracked this closely because the company's hedging strategy for raw materials is fairly opaque in public filings, and the actual cost of coal per ton of crude steel produced at IJmuiden varies dramatically quarter to quarter depending on freight rates and contract terms. The EU's Carbon Border Adjustment Mechanism (CBAM), which entered its transitional phase in October 2023, is another factor that matters more than most headlines suggest. CBAM effectively puts a carbon price on imported steel, which benefits Tata Steel's European production once the full implementation kicks in — but only if that production is sufficiently decarbonized. The paradox is that the transition period itself is the most expensive and risky phase. You're spending billions on new technology while still competing against cleaner imports that haven't yet been fully priced for their carbon content. For anyone trying to track what's happening with Tata Steel, the company's investor relations website and quarterly earnings calls remain the most reliable sources. Analyst commentary from firms like Morgan Stanley and Barclays tends to be more accurate than general business press coverage, which often simplifies complex operational updates into binary good-or-bad narratives. The steel industry doesn't operate in binaries, and reducing it to "Tata Steel wins" or "Tata Steel loses" headlines misses the actual dynamics at play.
Get the Full Details

One thing worth noting that the press usually overlooks: Tata Steel's research collaboration with the Indian Institute of Science and other institutions on green steel technologies has produced some genuinely interesting work on alternative reduction agents and process optimization, but this R&D doesn't show up in quarterly financials and rarely makes mainstream news. The practical impact of this research on production efficiency will likely become visible in the next two to three years.