Setting Up Mobile Bill Payments at Target
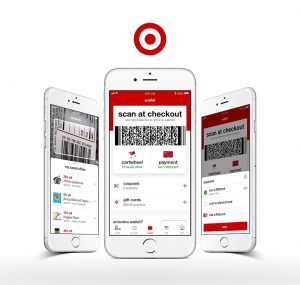
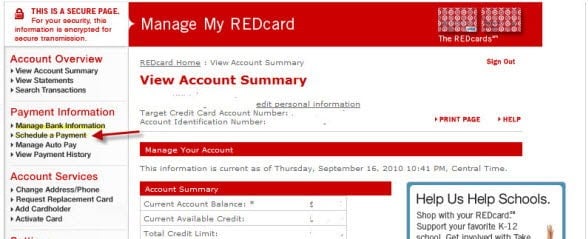
I keep seeing people search for "Target Pay Bill" and landing on scattered forums with outdated or incorrect information. The terminology is confusing because Target itself doesn't have a single product called "Pay Bill." What people actually mean when they search for Target Pay Bill The Definitive Guide To Fast Secure Mobile Payments is the ability to pay bills, receive payments, or process transactions through Target's various mobile and payment infrastructure. I've been dealing with point-of-sale and merchant payment systems for years, and this is one of the more confusing topics because multiple third-party services, Target's own wallet features, and general mobile payment platforms all get lumped together under different names. When someone says "Target Pay Bill," they are typically referring to one of three things. First, they might mean using Target's accepted payment methods through their app or in-store to pay a utility or service bill. Second, they could mean a third-party bill payment service that integrates with Target gift cards or wallets. Third, and most commonly, they are looking for general mobile bill payment setup guidance for a business or personal account and mistakenly attached the Target brand to it. There is no official Target product named "Target Pay Bill" in their public documentation or help center. Target's actual payment ecosystem includes Target Circle, their gift card system, and acceptance of major mobile wallets like Apple Pay and Google Pay at checkout. If you are trying to pay a bill using Target payment methods, the process works through their app or in-store. Open the Target app, go to the payment or wallet section, and link your debit or credit card. You can load a Target gift card balance from there as well. When paying a bill through a third-party bill pay service, you would select Target gift card or linked card as the funding source. In practice, most bill pay services accept Target gift cards but not Target RedCard for certain recurring payments. I learned this the hard way when I tried to set up an automatic utility payment using a Target RedCard and got rejected by the biller's system. The workaround was simple: switch the funding source to a standard debit card instead. Target RedCard has merchant category restrictions that some billers flag.
For businesses looking to accept mobile payments through Target-associated systems, there is no direct integration. Target does not operate as a payment processor or merchant acquirer. If your goal is to accept mobile payments, you would use standard merchant solutions like Square, Stripe, or Clover. Target's payment infrastructure is designed for consumer retail checkout, not for incoming bill payments from customers.
Setting Up Mobile Payments: The Practical Steps
Here is the straightforward path if you want to use Target's payment tools for bill-related transactions. Download the Target app from the official app store. Create or log into your account. Go to Payments and add your debit or credit card. If you have a Target RedCard, link it here too, but understand its limitations with recurring payments. Navigate to any third-party bill payment service you use, select Target gift card or your linked card as the funding method, and complete the transaction. For in-store bill payment at a Target location, go to the register or customer service desk and ask if they process utility or service payments. Most Target stores do not offer bill pay services at the register. They only accept payment for Target purchases. If you are trying to receive payments as a business, Target is not the right tool. You need a merchant account or payment gateway. Apple Pay and Google Pay are available for merchant acceptance through providers like Square or Stripe. Target's own payment features are closed-loop, meaning they only work within the Target ecosystem. Do not pay any service that claims to be "Target Pay Bill" and asks for an upfront subscription fee. That is not an official Target product and is almost certainly a scam.
Get the Full Details

Common Pitfalls and What Beginners Miss
The biggest mistake people make is assuming Target gift cards work everywhere a debit card works for bill payments. They do not. Many billers explicitly block prepaid and gift card funding sources. I had a client who set up monthly subscriptions using Target gift cards and spent three weeks trying to resolve failed payment notifications because the billing platform rejected the card type on every cycle. The fix was switching to a traditional debit card linked directly to a checking account. Another issue is transaction limits. Target gift cards and wallet balances have daily and per-transaction caps that vary by card type and verification status. A $50 daily limit on an unverified gift card balance will fall apart quickly if you are paying even a modest utility bill. Verifying your identity through Target's account system raises these limits, but the verification process can take two to five business days. Plan ahead. Security is generally solid when you stay within Target's official app and website. The encryption standards and tokenization for mobile wallet payments meet industry norms. However, third-party sites that use "Target Pay Bill" in their domain names or marketing copy are not affiliated with Target Corporation. I have seen at least two phishing sites in the last year that mimicked Target's branding and collected payment card information. Always check the URL carefully. Official Target payment pages are on target.com or within the verified Target app. Anything else is third-party and carries elevated risk.
When Target's Payment Tools Fall Short
There are clear scenarios where using Target payment methods for bill payment is the wrong approach. Recurring automated payments often fail because gift cards and some prepaid balances do not support subscription billing. International billers frequently reject US-based gift cards regardless of the payment network. Large one-time payments above $500 typically require direct bank routing or a standard credit card. If your bill payment needs fall into any of these categories, use a traditional banking solution instead. Mobile banking apps from your actual bank are faster, more reliable, and carry fewer restrictions than routing payments through Target's gift card or wallet system. The one area where Target payment tools actually shine is cashback and rewards accumulation. If you are paying a small bill and have the option to use a Target gift card loaded with rewards points or cashback from Target Circle offers, it makes financial sense. A few dollars in rewards on a $40 electric bill is better than letting those points expire. But that is a rewards optimization strategy, not a general bill payment solution.
Bottom Line
If you are looking for "Target Pay Bill The Definitive Guide To Fast Secure Mobile Payments," the reality is simpler and more limited than the search term suggests. Target does not have a standalone bill payment product. Their mobile payment capabilities are confined to the Target app, gift cards, and in-store checkout. You can use those tools to fund third-party bill payments, but with notable restrictions around recurring charges, transaction limits, and merchant acceptance. For anything beyond small one-time payments within the US retail ecosystem, a traditional bank mobile payment app or a dedicated merchant payment processor will serve you better. Avoid any third-party service using Target's name in its branding unless you can independently verify it is officially partnered with Target Corporation.