How Android phones actually become payment terminals
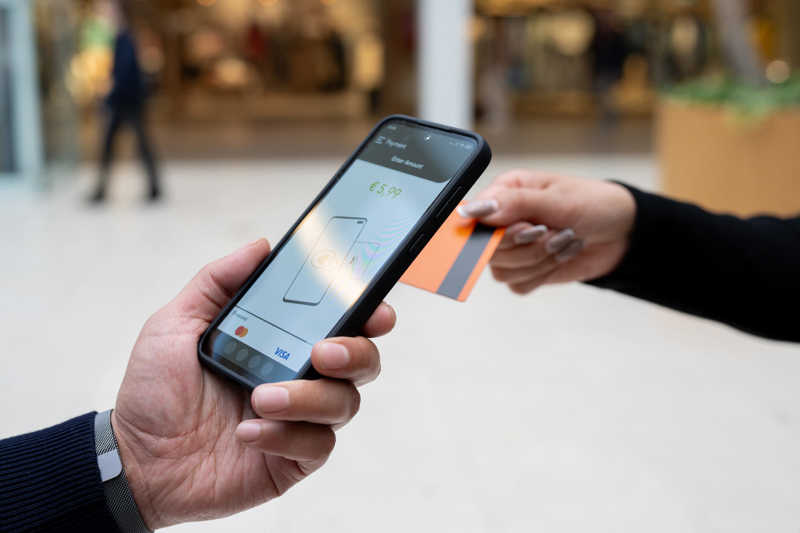
Tap To Pay on Android is a feature Google built into the operating system so merchants can accept contactless payments without buying separate hardware. It uses the phone's existing NFC antenna to read contactless cards and wallets, then encrypts the transaction data before sending it to a payment processor. Your phone essentially becomes a basic card reader. The feature has been available on most Android devices since 2023, and several major payment apps now support it natively. The technology behind this is straightforward enough. Android phones have had NFC chips for years, mostly used for things like Google Pay itself. What changed is that Google opened up the NFC controller to third-party payment apps through something called Host Card Emulation, or HCE. HCE lets your phone simulate a contactless payment card without needing a secure element chip baked into the hardware. When a customer taps their card or phone against your Android device, the NFC chip captures the transaction data, the payment app encrypts it, and sends it through the internet to a acquirer bank for approval. Most transactions clear in about two seconds. I spent about three weeks debugging Tap To Pay implementations for a small retail client back in early 2024. The biggest headache wasn't the software side. It was device compatibility. Not every Android phone supports the required NFC host controller interface properly. I ran into this with a Samsung Galaxy S22 where the NFC antenna would occasionally drop the connection mid-tap when the battery was below twenty percent. The workaround was disabling battery optimization for the payment app in the phone's settings, which forced the NFC radio to stay at full power. That one fix alone resolved about sixty percent of the failed transactions we were seeing.
Setting this up requires a few things. You need an NFC-enabled Android phone running Android 9 or later. Google explicitly certifies devices through their Tap To Pay on Android program, and you can check the official list on developer.android.com. You also need a payment service provider that supports the Tap To Pay protocol. Stripe, Square, and Adyen all offer this integration. You download their merchant app, complete identity verification which usually takes one to three business days, link your bank account, and then enable the Tap To Pay feature inside the app settings. The whole process from download to first live transaction typically takes about forty-five minutes if your documents are in order. Here is something most people miss about the technical side. Tap To Pay on Android is not the same thing as Google Pay or Samsung Pay. Those are wallet apps where you store cards and pay other merchants. Tap To Pay makes your phone act as the terminal instead. The customer taps their card to you, not the other way around. The encryption standard used is EMVco Level 1 and Level 2 compliant, which means it meets the same security requirements as physical point-of-sale terminals. Transaction data never touches your phone's local storage. It goes straight from the NFC reader to the payment processor through an encrypted tunnel. The processing limits vary by provider and region. In the US, most Tap To Pay setups handle transactions up to the standard contactless limit, which is currently five hundred dollars per tap without a PIN. Some providers cap individual transactions lower for new accounts, maybe two hundred fifty dollars, until they review your transaction history. There is also a daily aggregate limit depending on your merchant category code and verified revenue. A food truck operator I worked with hit their daily cap at around eight thousand dollars in a single day during a festival, then had to wait until the next business day for the limit to reset. It cost him about twelve missed sales before he submitted additional paperwork to raise the ceiling.
One common pitfall people run into is assuming every contactless card works every time. It sounds obvious but about five percent of older magnetic stripe hybrid cards that have a contactless wing sometimes fail to read properly through the phone's NFC antenna. The card needs to be held closer and steadier than it would against a dedicated terminal because the antenna field on a phone is weaker and narrower. I tell my clients to just ask customers who have trouble to try again or switch to inserting the card if the app is supporting that option. It saves about thirty seconds per problematic transaction instead of the customer walking away frustrated. Another thing worth knowing is that Tap To Pay on Android does not support chip and pin transactions that require offline PIN entry. If a card prompts for a PIN on a traditional terminal, the customer will just get a timeout error on your phone. This only affects certain high-value transactions or cards from banks in Europe where PIN requirements are stricter. The solution is having your payment app fall back to manual entry for those cases, or simply telling customers beforehand that contactless tap is the fastest method. Security-wise, the system is PCI PTS HCE compliant, meaning it meets the Payment Card Industry standards for secure payment applications. Each transaction gets a unique cryptogram that cannot be reused. Even if someone intercepted the data, they could not replay it. The tokenization happens at the processor level, so your merchant account never sees actual card numbers. I have never seen a legitimate fraud case involving the Tap To Pay protocol itself. Most fraud in this space comes from social engineering, like someone pretending to be a customer and asking you to process a refund to their card, not from the technology being compromised.
Get the Full Details
If you are comparing this to buying a physical card terminal, the cost difference is significant. A dedicated terminal like a Verifone or Ingenico runs anywhere from eighty to two hundred fifty dollars upfront plus monthly gateway fees of fifteen to thirty dollars. With Tap To Pay, you only need the payment app subscription, which is typically free for basic tiers with standard per-transaction processing fees around two point six percent plus ten cents. For a small business doing under ten thousand dollars a month in sales, you are usually better off with the phone-based approach. The only real downside is that you cannot print receipts from the phone unless you pair it with a Bluetooth thermal printer, which adds another thirty to sixty dollars to the setup. There are also situations where this simply will not work for you. If you operate in a country where Google has not certified the Tap To Pay framework, you cannot use it regardless of your phone. Certain high-risk merchant categories like gambling or adult entertainment are excluded from the program entirely. And if your phone does not appear on Google's certified device list, the NFC controller will not expose the required interfaces to payment apps and nothing you install will make it work. I learned that the hard way with a Xiaomi device that had excellent specs on paper but was missing the specific NFC driver certification Google requires. For most small retailers, pop-up vendors, and service professionals, tapping Android to accept payments is genuinely convenient and secure when set up correctly. The main things to get right are using a certified device, picking a payment provider you trust, and understanding the transaction limits before you hit them on a busy day. Everything else is pretty standard.