Why I Still Talk About Iarcher After Two Years
I first started looking at Archer back when they were still operating under the name Karem Aircraft division. That was 2022, maybe early 2023. I was tracking several eVTOL companies at once, mostly for a client who wanted exposure to the urban air mobility space without putting too much capital into any single bet. Archer kept showing up on my screen for reasons that had nothing to do with flight tests or FAA progress. It came down to the balance sheet and the partnership with BP. The truth about investing in companies like this is that nobody tells you how quiet the early years are. There are no earnings calls that move the needle. The product isn't flying commercially yet. What you actually get is press releases, regulatory milestones that take longer than expected, and stock price swings driven entirely by momentum and social media narratives. I watched the Archer ticker drop 40% in a single month during the worst of the 2023 SPAC correction, and I had to resist the urge to do anything. Which is harder than it sounds when your initial investment is underwater by that margin.
Taking Flight With Iarcher Aviation Is It A Smart Investment
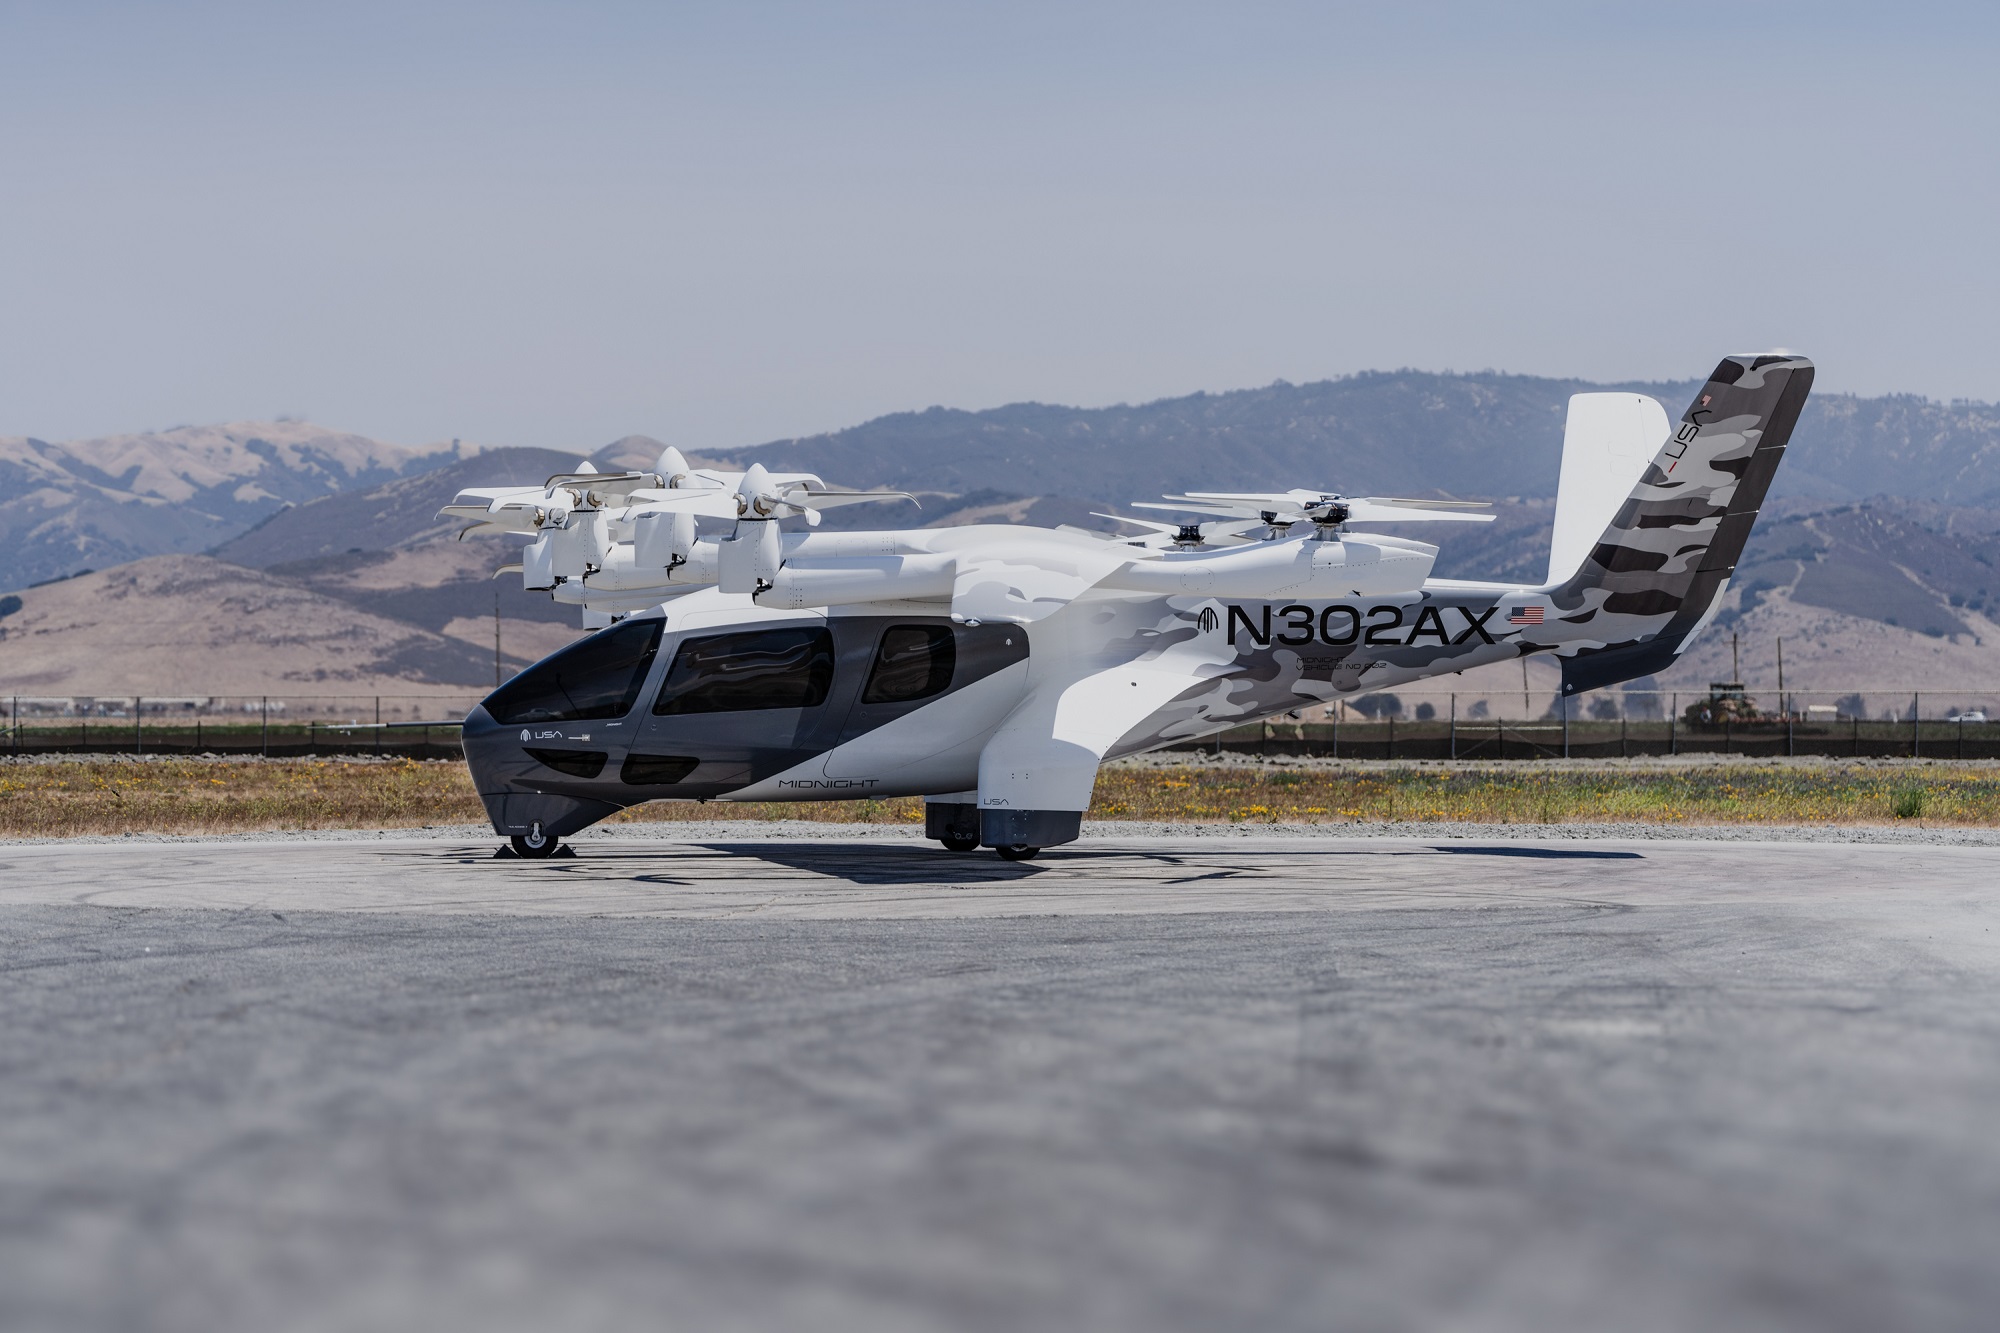
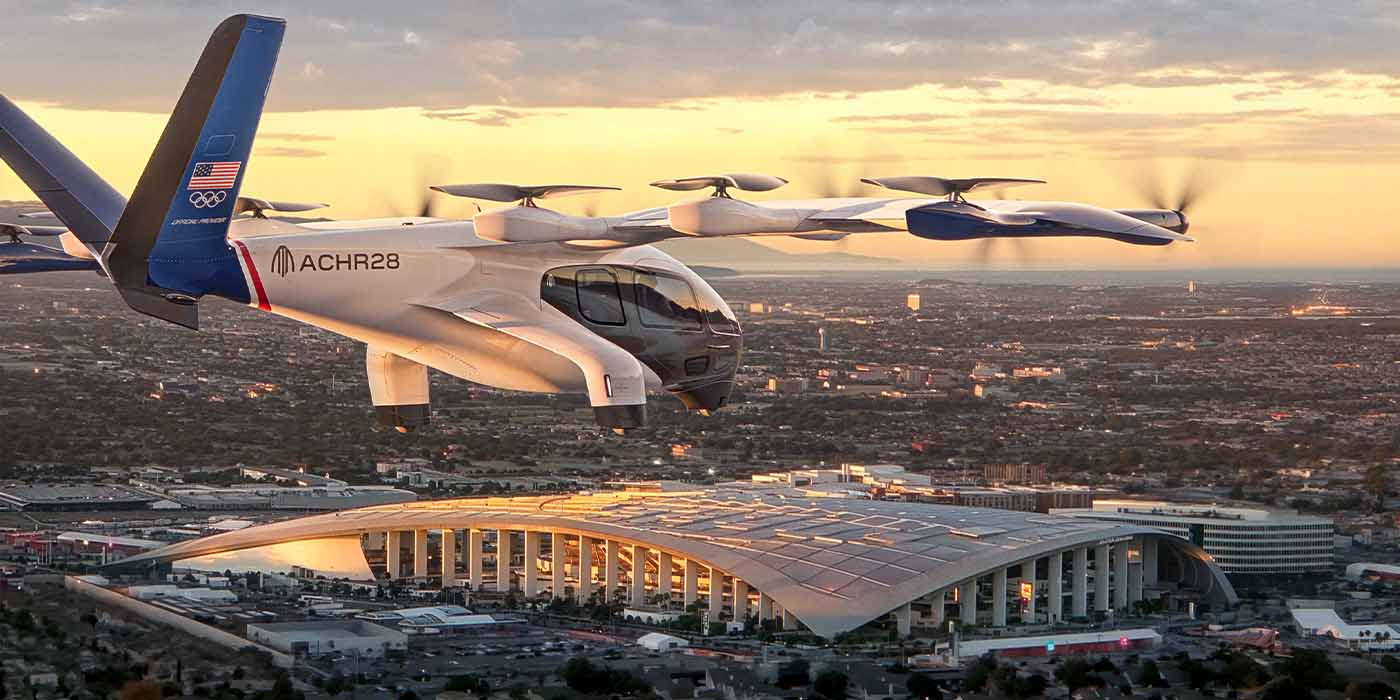
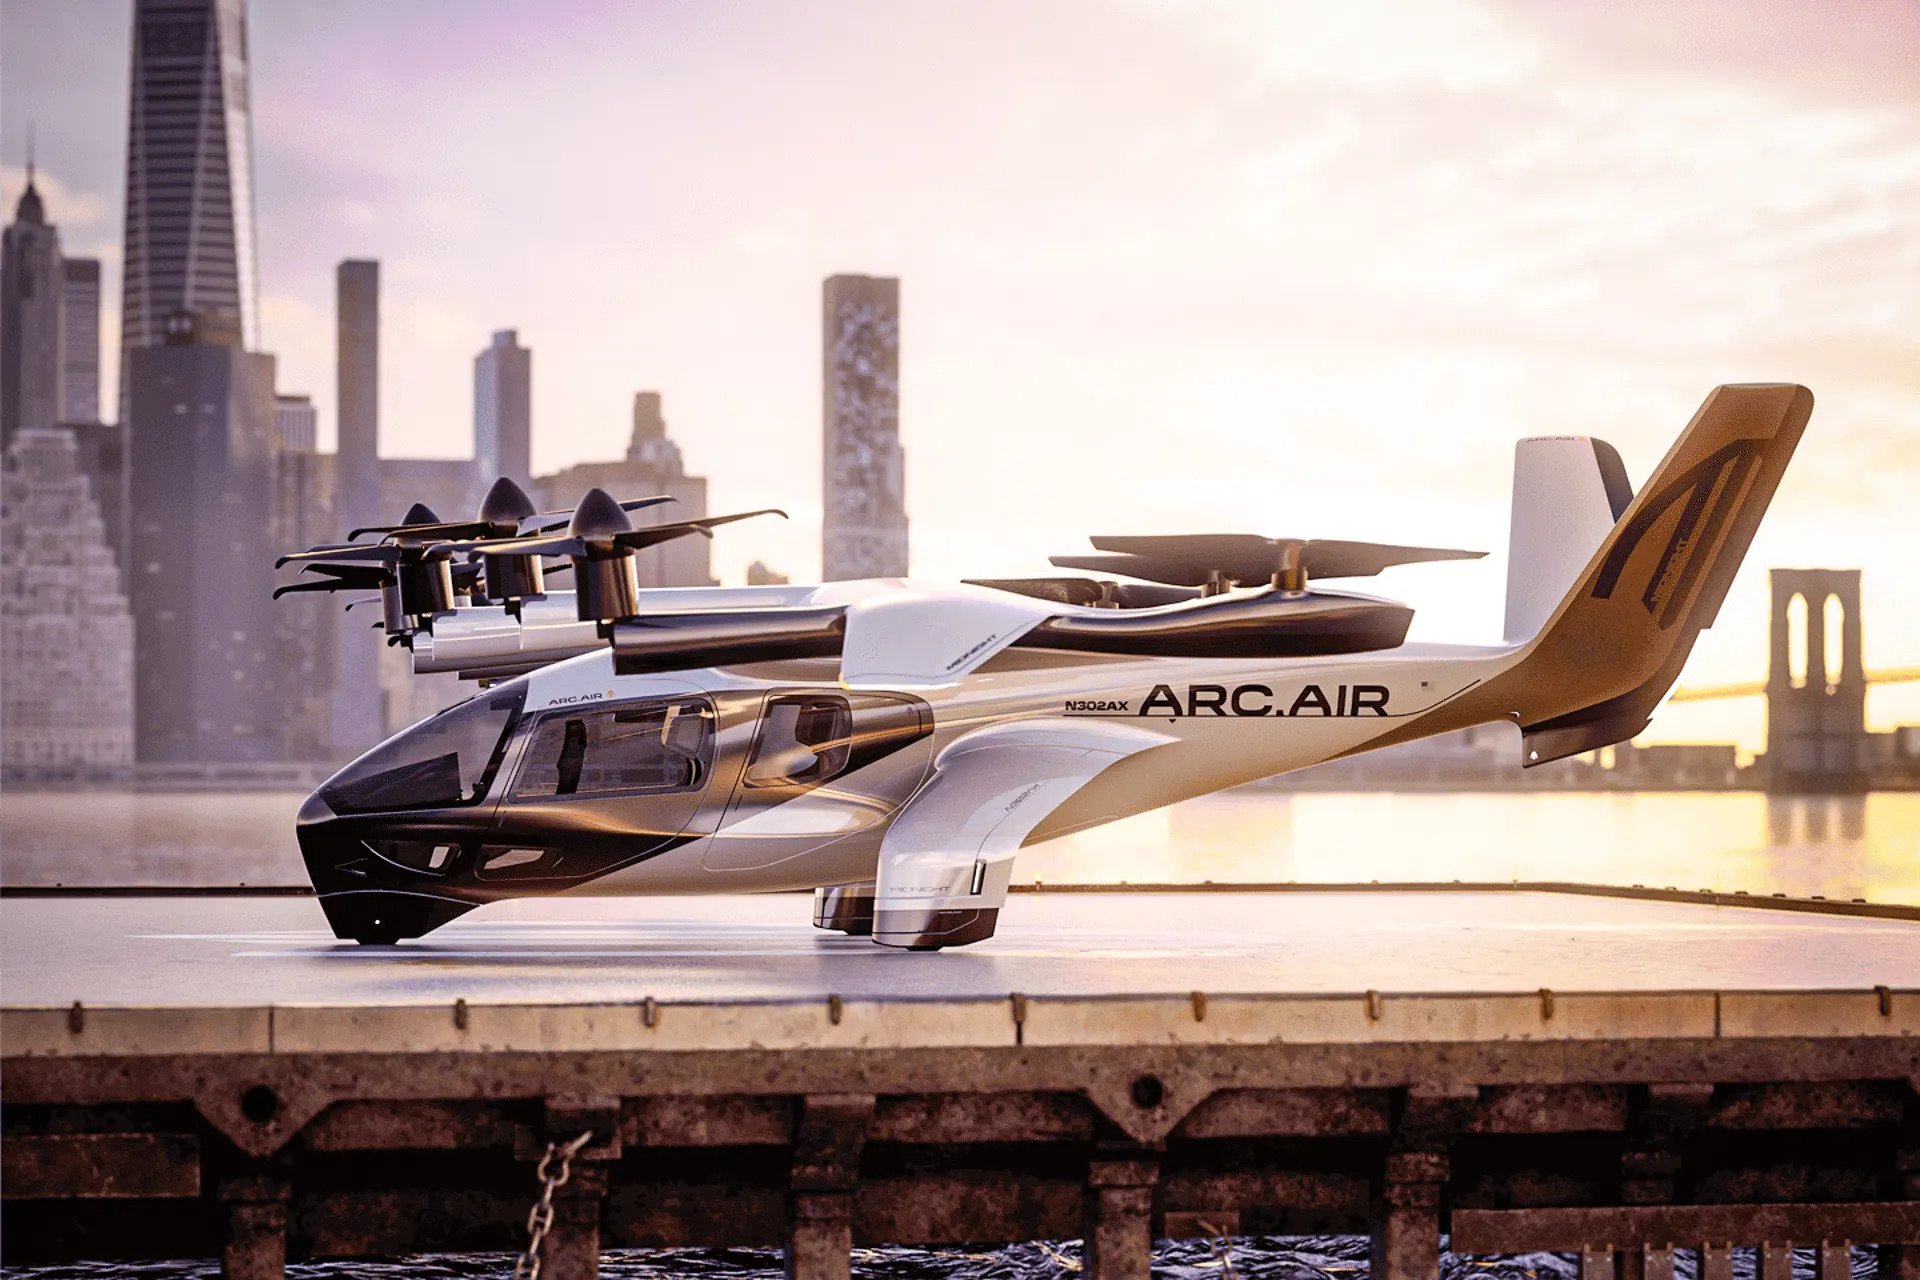
Let me explain what I actually mean by that question, because the answer depends entirely on your time horizon and your tolerance for regulatory risk. Iarcher Aviation — the company went public through a SPAC merger with Perceptive Acceleration Corp in July 2021, and has since rebranded to simply Archer Aviation Inc. The stock trades under ACHR on the NYSE. The core thesis is that they will build a fleet of electric vertical takeoff and landing aircraft and operate them as an air taxi network in major US cities, starting with New York and San Francisco. The aircraft in question is the Midnight, a five-seat eVTOL designed for urban routes of roughly 50 to 100 miles. Here is what most people miss when they evaluate this as an investment. The Midnight has not received type certification from the FAA. None of the other major eVTOL competitors have either. This is not a minor delay — it is the entire business model sitting behind a regulatory gate that has never been opened for this category of aircraft. The FAA is developing new certification standards, specifically Part 21 subpart F for special class aircraft, and there is no guaranteed timeline. My best read from watching the process unfold is that a realistic certification window for Archer lands somewhere between late 2026 and 2028, assuming no major safety incidents occur that reset the entire review process. I also want to flag something specific that cost me money last year. I was tracking Archer's production ramp alongside their cash burn rate. They reported a quarterly burn of roughly $180 to $200 million at one point, and their runway was always framed as 18 to 24 months from any given quarter end. The risk is that production scaling costs more than expected, which is almost always the case in aerospace. When this happens, companies issue dilutive offerings. Archer did exactly this in mid-2024, selling shares at a price that crushed the stock for three weeks straight. The workaround I used was simple but effective — I stopped watching the stock price and started tracking their quarterly cash position and debt issuance instead. Those numbers told the real story long before the share price dropped.
The Technical Position They Actually Hold
Archer is not building a car with propellers. The Midnight uses distributed electric propulsion with eight rotors, and the powertrain is entirely in-house, which is significant. Most eVTOL competitors source their motors and batteries from existing suppliers. Archer designs the motor, the reducer gearbox, the power electronics, and integrates the battery management system themselves. This gives them tighter control over weight and efficiency but also means every failure mode is their problem to solve. Battery energy density remains the single biggest technical constraint. The Midnight is designed to carry a useful load of about 1,000 pounds with a range near 60 miles under optimal conditions. That is enough for an airport-to-downtown route. It is not enough for cross-country travel, and it is not enough if you need a 20% payload buffer for wind or weather deviations. The BP partnership is real and it matters more than the marketing copy suggests. BP is committing $150 million in a combination of cash and equity, and they are building electric vehicle charging infrastructure that doubles as ground power for the Midnight fleet at vertiports. This is not a vanity deal. Electric aircraft charging requires high-power direct current at scale, and building that infrastructure is one of the most expensive parts of the business. Having an oil company fund that part of the stack is structurally useful even if BP's involvement doesn't guarantee anything about certification speed.
Get the Full Details
What the Financials Actually Look Like
Archer is pre-revenue. I want to be blunt about that because some prospectus language and investor presentations make it sound like revenue is just around the corner. It is not. The company reports operating losses measured in hundreds of millions per quarter. Revenue as of the most recent filings is essentially zero from operations. Any revenue they show comes from government contracts, research partnerships, or one-time payments, not from flying passengers in a commercial service. Here are the numbers that matter for your own evaluation:
- Annual revenue before 2026 is expected to be minimal, likely under $20 million from non-dilutive sources
- Operating expenses are running in the $200 to $300 million annual range
- Cash and equivalents have fluctuated between $600 million and $1 billion depending on capital raises
- Dilution has occurred multiple times, reducing early shareholder ownership by an estimated 60 to 70 percent from the SPAC merger
This is not a value investment. It is a speculative position on whether a new transportation category gets certified and scales in the United States within the next five to seven years. If you are looking for dividend income or steady cash flow, this company provides neither now and likely will not for several years. I treat eVTOL exposure as a satellite position, not a core holding. The maximum allocation I have ever put into any single name in this space is 3 percent of a total portfolio, and that was after they showed meaningful progress toward certification. For most investors, even that is aggressive. The sector carries concentration risk, regulatory risk, execution risk, and dilution risk simultaneously. When multiple risks converge, which they tend to do in aerospace development programs, the drawdowns can be severe and prolonged. One thing I learned the hard way: do not average down blindly on a SPAC-era eVTOL stock just because the price dropped 50 percent. The original thesis may still be intact, but the share count is likely much higher than it was when you first bought. Averaging down without recalculating your percentage ownership and expected dilution simply makes you more exposed to the same risk at a higher cost basis. I stopped averaging down on Archer after my second or third round and switched to buying only on technical support levels with a defined exit if the next earnings report showed accelerating cash burn without progress toward certification milestones.
Alternatives Worth Considering
If you want exposure to urban air mobility but prefer less direct risk, there are two paths I would recommend instead. The first is a broad aerospace and defense ETF. These funds hold companies that supply components, materials, and subsystems to eVTOL programs without carrying the full binary risk of any single manufacturer failing certification. The second path is to wait. The market will price in certification news when it happens. Buying after a Type Certificate is granted, even at a higher price, is often a better entry than buying before the certificate is issued at a lower price, because the probability of failure is still meaningfully above zero at the current stage. I checked my positions this morning and I still own a small amount of ACHR. Not because I am excited about the near-term outlook, but because I have already written down the capital and I am comfortable letting the thesis play out over a multi-year window with no additional investment. That is the honest answer to whether this is a smart investment. It can be, if you size it correctly and understand that you are buying optionality on a regulatory outcome, not a business that is currently generating revenue.