Navigating Wells Fargo's Mobile Platform Without Losing Your Mind
The Wells Fargo mobile app login process has gone through several iterations over the years. If you are trying to Take Control Of Your Finances The Power Of Wells Fargo Mobile Login, the first thing you need to understand is that the app itself is only one piece of the puzzle. The underlying online banking infrastructure behaves differently depending on whether you are using Safari, Chrome, or the in-app browser, and that difference matters more than most people realize. I set up mobile banking access for roughly a dozen clients back when I was handling financial operations coordination, and the single most common failure point was not the password itself. It was the device enrollment step. Wells Fargo uses a companion device registration system where your phone has to be explicitly approved before it can access account data. Skip that step or cancel it prematurely and you will spend twenty minutes watching the app spin.
Take Control Of Your Finances The Power Of Wells Fargo Mobile Login
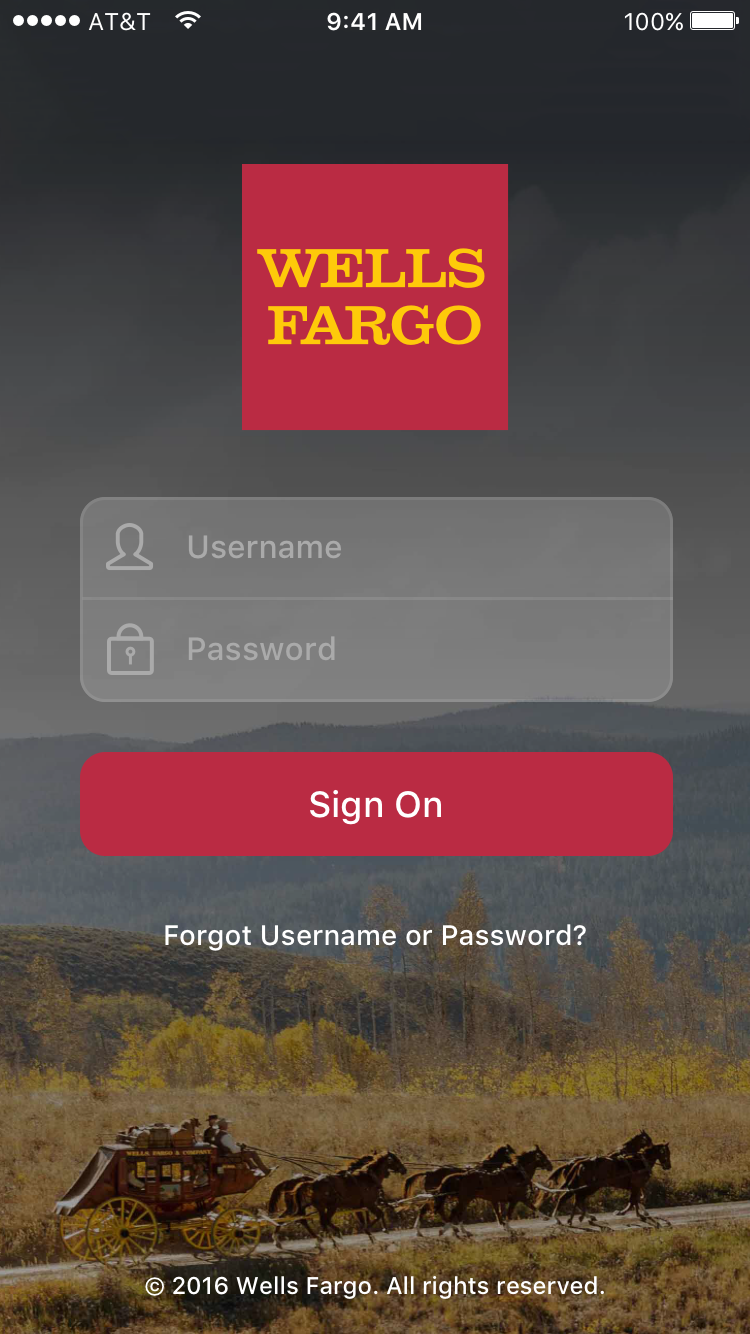
Here is the actual flow that works consistently. Download the official Wells Fargo Mobile app from the App Store or Google Play. Open it and select log in with your existing online banking credentials. If you do not have an online banking profile yet, you will need to enroll through their website first on a desktop. The mobile enrollment path exists but it is slower and more prone to session timeouts. Once you enter your user ID and password, you will be prompted to set up a PIN or biometric authentication. After that, the app sends a device enrollment code. You enter that code into the app. That is when most people hit a wall. The system says "processing" and then does nothing for several minutes. The workaround here is straightforward. Close the app completely. Wait ten seconds. Reopen it. Log in again with the same credentials. The second attempt usually completes the enrollment because the initial session had established the backend handshake but the app UI had not refreshed properly. This is a known timing issue with their token validation system, not something wrong with your device.
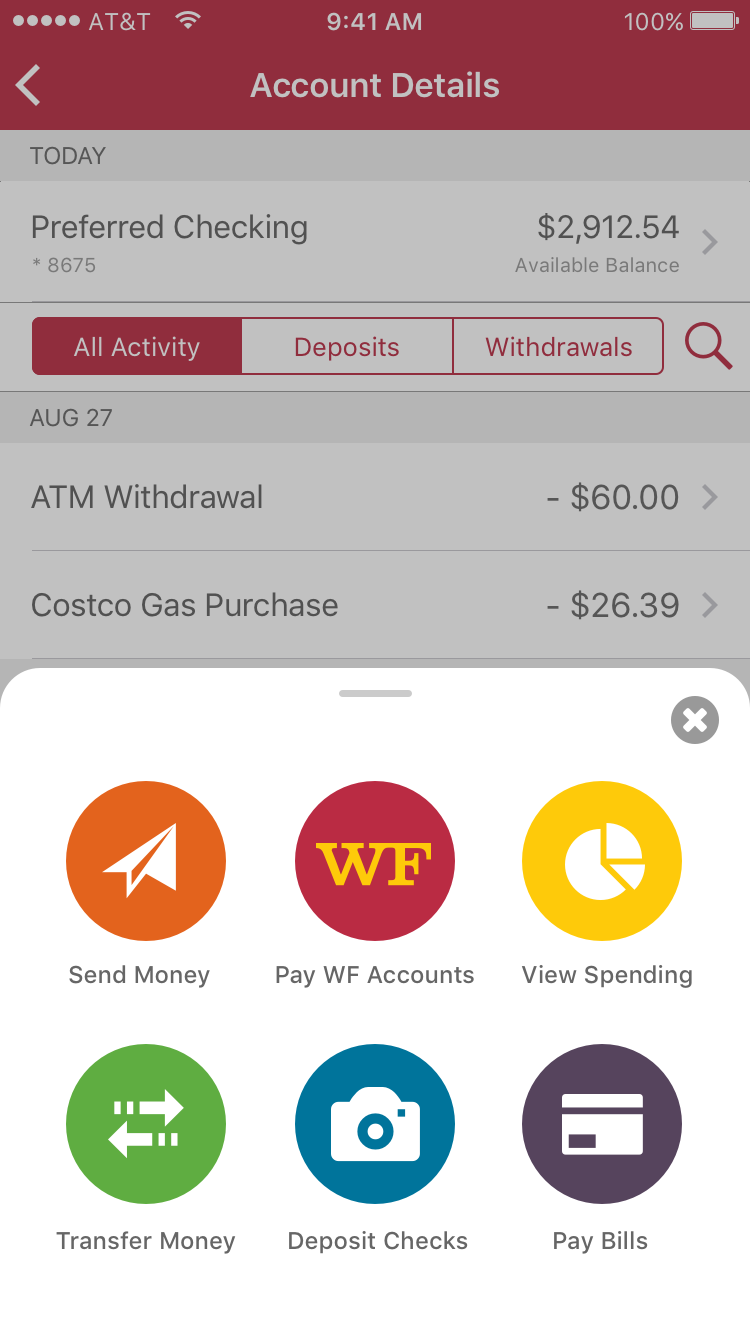
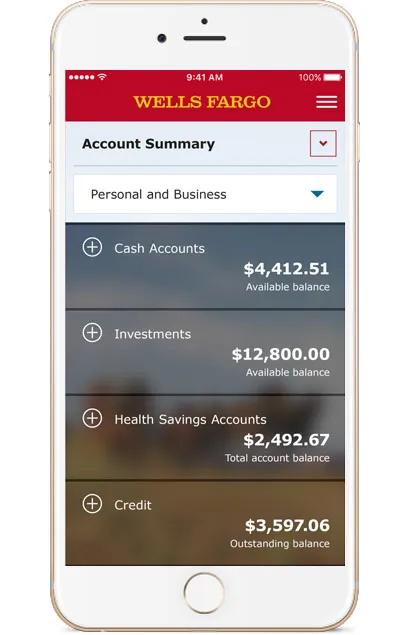
One thing that catches people off guard is the multi-factor authentication layer. Wells Fargo does not rely solely on a password. After you log in, they may send a one-time code via text or email, or prompt you to answer a security question you set up during initial enrollment. If you lost access to the phone number on file, which happens more often than you would think, you cannot reset it through the app. You have to call customer service or visit a branch. The app will not let you verify a new number independently. The biometric login feature works well once it is set up. Face ID and fingerprint authentication bypass the password step entirely for subsequent logins. However, there is a quirk. If you update your passcode on your phone or restore from a backup, sometimes the biometric keys get invalidated. The app will still ask for your username and password, which is correct behavior, but the saved biometric option disappears until you re-enable it in the app settings under Security and Privacy. It is a minor inconvenience but worth knowing about. From a practical standpoint, the mobile app covers most day-to-day banking needs. You can check balances, transfer between accounts, deposit checks by photographing them, pay bills, and set up alerts. The check deposit feature has a limit that varies by account type, usually ranging from a few thousand dollars per transaction to around ten thousand depending on your history with the bank. If you need to move larger sums, the app will block it and direct you to initiate the transfer through the online portal on a computer.
Get the Full Details

There are legitimate downsides to the platform that the marketing materials do not mention. The app can be sluggish during peak hours, especially on older devices. The search function for transactions is rudimentary at best. If you need to pull a detailed report spanning multiple years or filter transactions by a specific merchant category, you are going to have a bad time. The online banking website on a desktop browser handles those queries far better. The mobile app is designed for quick lookups and simple transfers, not for deep financial analysis. Another frustration is the notification system. Alerts are configurable but the options are limited. You can set up balance alerts and transaction alerts, but you cannot create custom conditional logic like "alert me if any single transaction exceeds fifty dollars AND it is from a category I have not seen before." The alerting engine is basic. For anyone managing complex budgets or running a small business through their Wells Fargo account, this gap becomes apparent quickly. If you prefer a more powerful mobile experience, some people use aggregator apps like Mint or Monarch to pull their Wells Fargo data alongside accounts from other institutions. This works through Plaid, the data aggregation service that Wells Fargo supports. The tradeoff is that your full transaction history is visible to a third-party service, and occasionally the connection breaks during bank maintenance windows. When that happens, you cannot refresh the synced data until Wells Fargo restores their API, which sometimes takes hours.
The bottom line is that the Wells Fargo mobile login gives you functional control over routine banking tasks. It is not elegant. It has edge cases that will waste your time if you are not prepared for them. But for checking balances, approving transfers, and monitoring daily spending, it does the job without requiring you to sit at a computer. Set up your device enrollment carefully, keep your contact information current, and know when to switch to the desktop portal for anything beyond basic account management.