Understanding Cyclic Behavior Across Systems
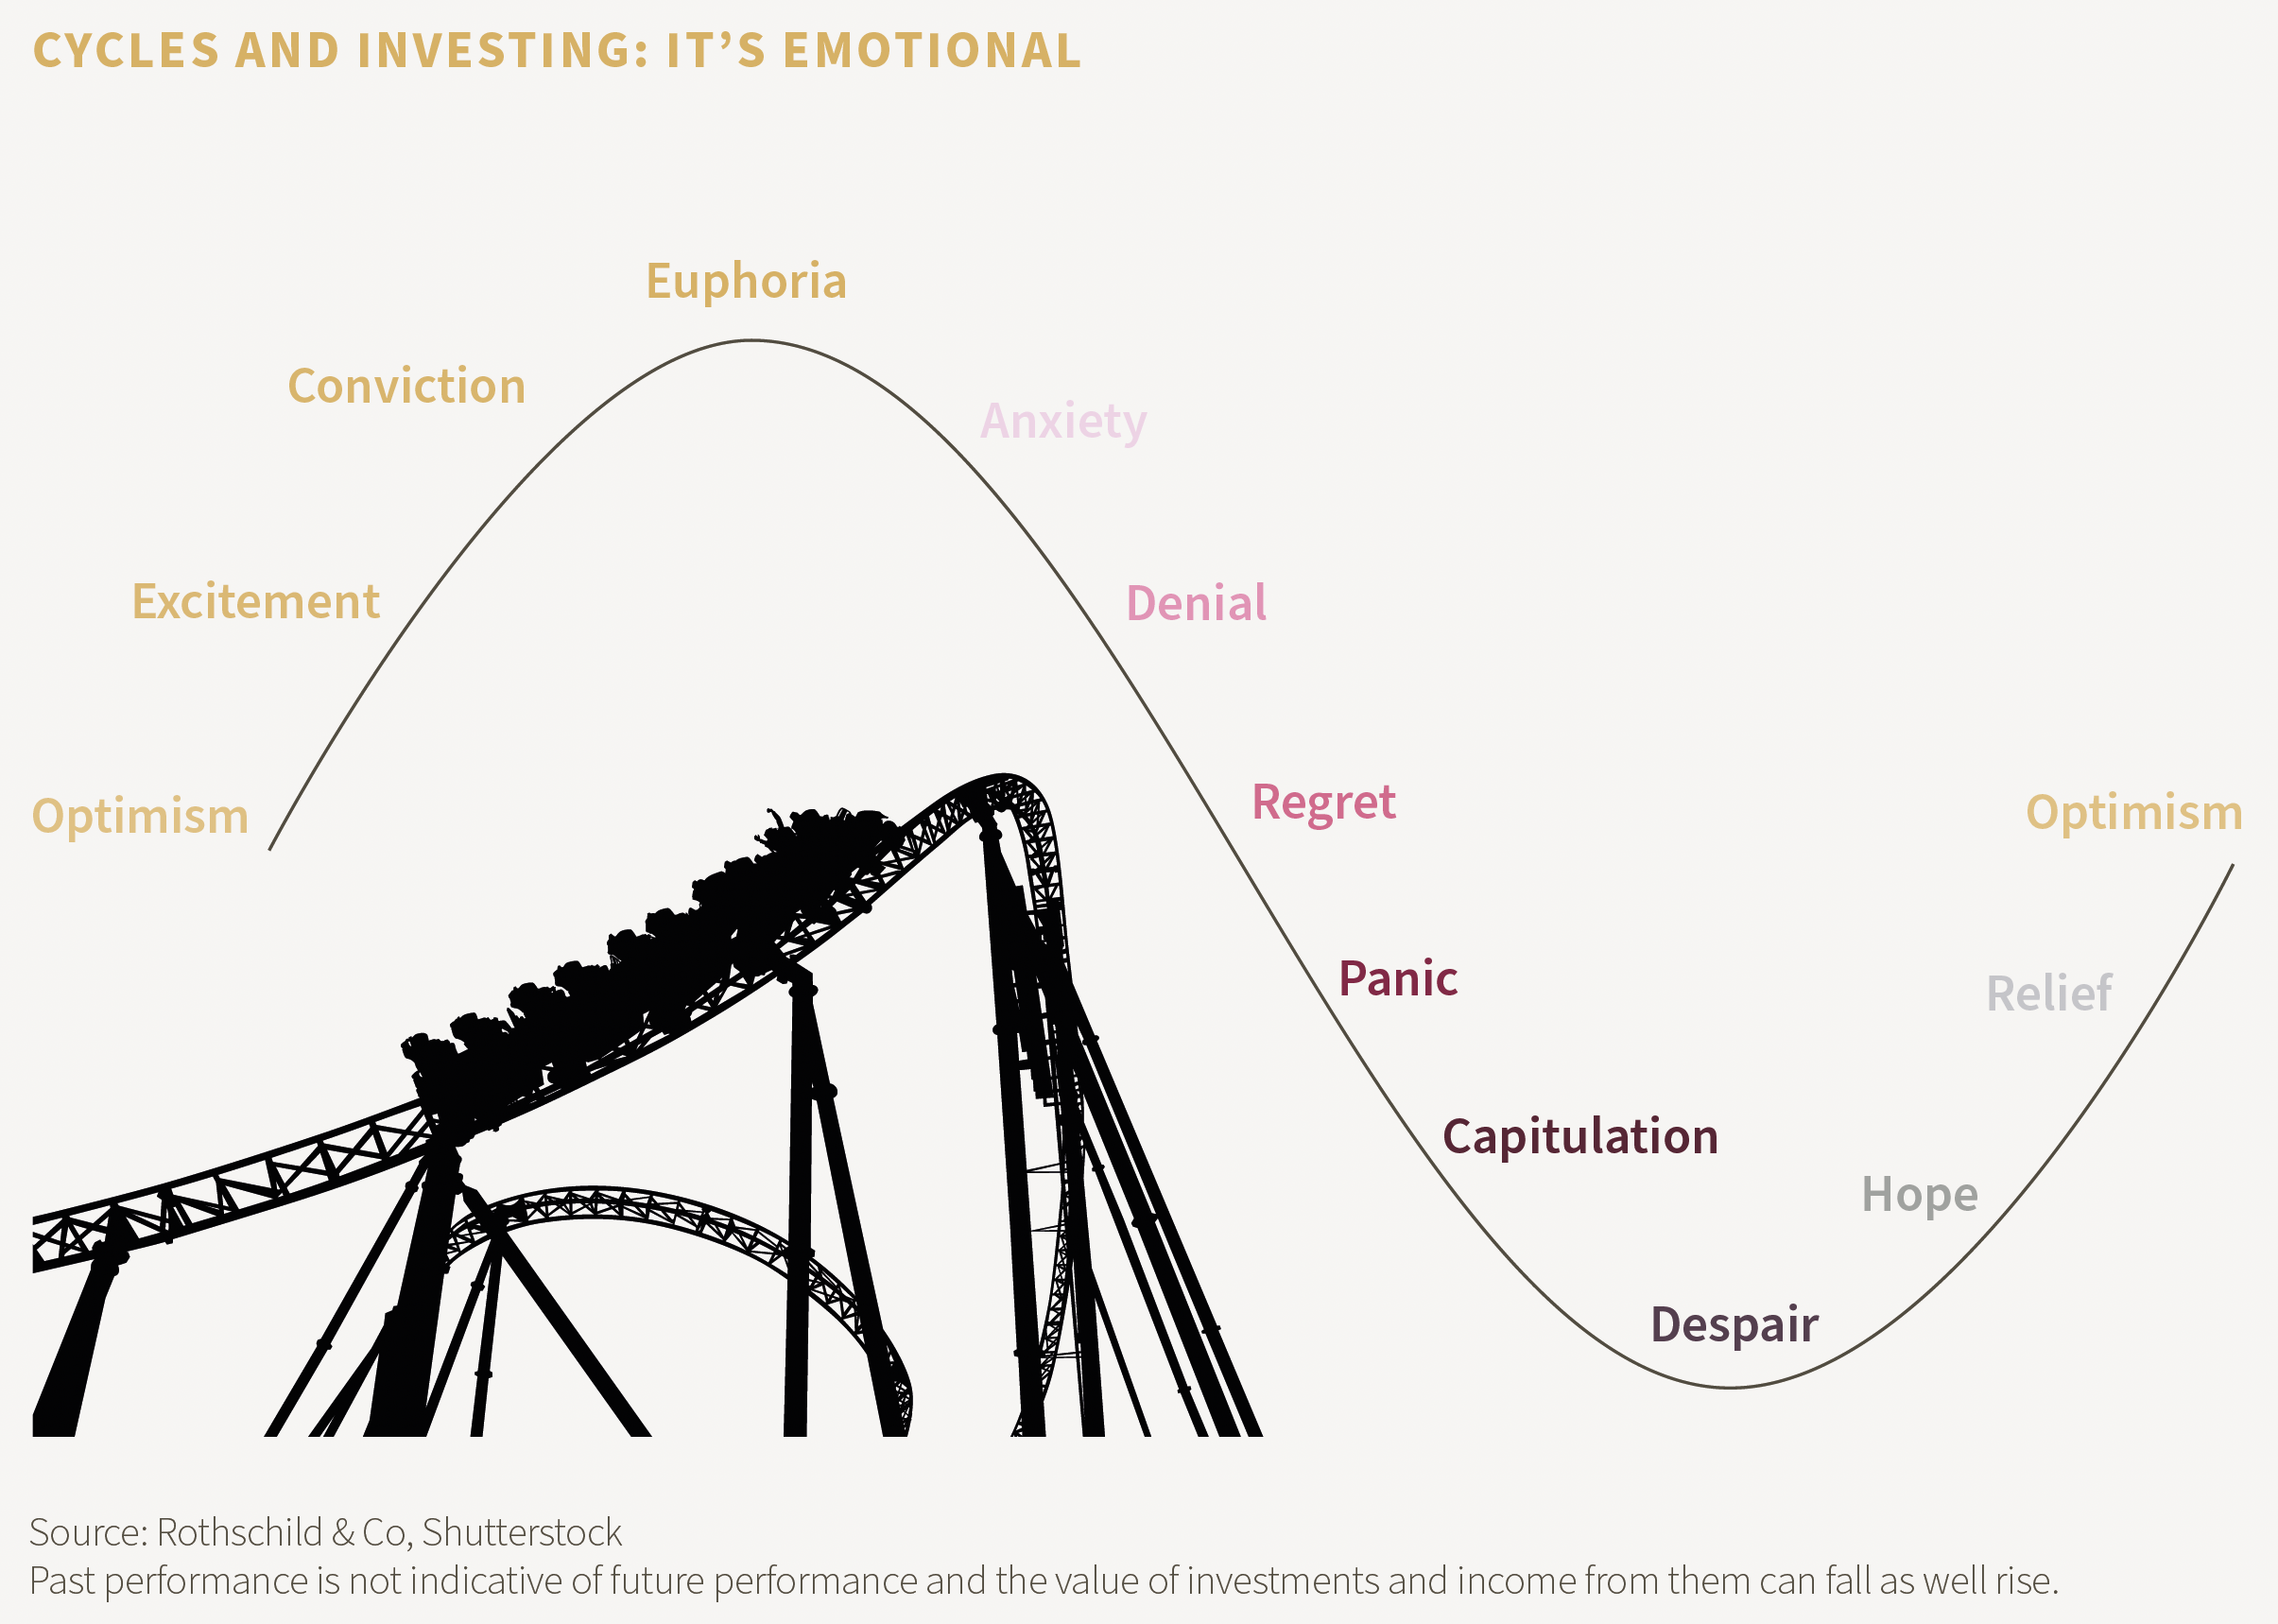
Most people treat oscillation as something theoretical. In practice, it is just the pattern that emerges when a system has feedback loops and inertia. I spent years tracking commodity cycles, and the first thing I learned was that nobody gets paid for knowing oscillation exists. Everyone knows prices go up and down. The money comes from timing the amplitude and period correctly, which is another problem entirely. The basic mechanic is straightforward. A variable pushes away from equilibrium, then some restoring force pulls it back. But the pull never lands exactly on zero. It overshoots. That overshoot creates the wave. In markets, the restoring force might be profit margin compression. In climate, it is thermodynamic redistribution. In innovation adoption, it is market saturation hitting marginal utility.
Synonym For Oscillation The Hidden Rhythm Governing Markets Climate And Innovation
If you are looking for the synonym you need, it depends on which field you are actually working in. Cycle is the general term. Rhythm works when you care more about regularity than measurement. Vibration shows up in physics contexts. Fluctuation implies irregular amplitude. Pulsation appears in biological systems. Surge and ebb are older words that still describe tidal and economic patterns accurately enough. The most useful term across all three domains I work in is simply cycle. It carries the right amount of technical weight without sounding like you are reading a textbook. Here is where beginners mess up. They assume oscillation means predictable repetition. It does not. Real systems produce damped, driven, and chaotic oscillations, and they shift between all three depending on external forcing functions. I once spent three months building a model that predicted copper price swings using a standard damped harmonic oscillator framework. The model performed beautifully on historical data. Then China's infrastructure stimulus hit in 2009 and the entire period structure shifted. The restoring force changed magnitude overnight because the demand side of the equation was no longer mean-reverting. It was trending. A harmonic model cannot handle a trending fundamental. I had to switch to a state-space model with a time-varying drift term. That fixed the fit but destroyed the simplicity I needed for actual trading decisions. You always pay a complexity tax when reality refuses to be simple.
How The Mechanism Actually Works In Practice
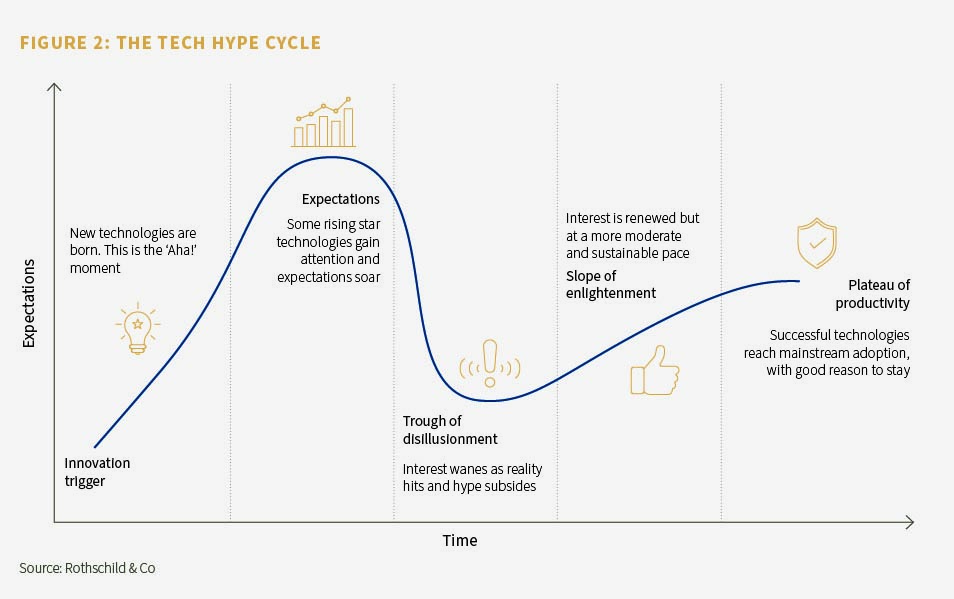
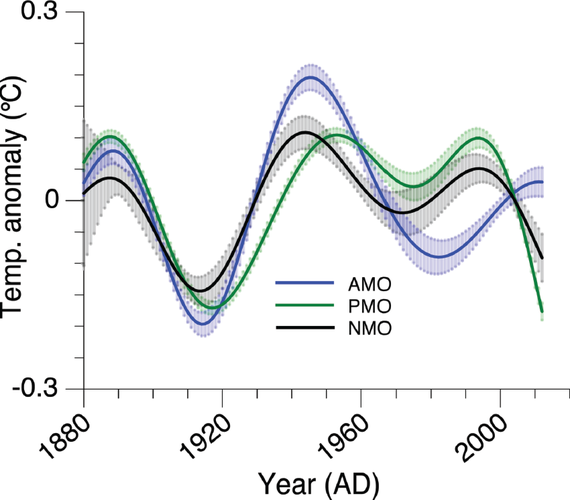
The math behind simple oscillation uses second-order differential equations. You do not need to solve them by hand to apply the logic. What matters is recognizing three components: displacement from equilibrium, velocity of movement, and the restoring force. In market terms, displacement is price deviation from a moving average. Velocity is momentum. Restoring force is whatever pushes value back toward fundamentals, whether that is short selling, margin calls, or regulatory intervention. In climate systems, the components look different but operate identically. Displacement is temperature anomaly. Velocity is heat flux rate. Restoring force is radiative equilibrium seeking to rebalance incoming and outgoing energy. The ENSO cycle runs roughly every 2 to 7 years depending on coupling strength with the wind field. The period is not fixed because the restoring force varies with ocean basin conditions. This variability is the single most important detail that separates amateur analysis from competent work. Nobody mentions it because the answer sounds boring. I worked on a project mapping technology adoption curves against historical commodity cycles. The insight was not novel but the data made it visible. Every innovation follows a logistic S-curve that oscillates around an adoption equilibrium. The first oscillation phase is early adopter enthusiasm driving adoption above sustainable capacity. The second phase is saturation pulling adoption below replacement growth. The third phase stabilizes near the carrying capacity of the market. The period between peaks tends to shorten as the innovation matures because information flows accelerate and switching costs drop. This pattern held across computing platforms, pharmaceuticals, and renewable energy deployment over a 40-year span.
Get the Full Details
Where The Framework Breaks Down
Oscillation analysis fails when the system experiences a regime shift. This happens more often than people admit. A regime shift changes the equilibrium point itself rather than just the variable's position relative to it. The 2008 financial crisis was a regime shift in credit markets. Pre-2008, mortgage defaults oscillated around a low equilibrium tied to employment rates. Post-2008, the equilibrium moved. The same oscillation model produced garbage forecasts because the underlying structural parameters had changed. Identifying a regime shift requires structural break tests, not just spectral analysis. Most analysts skip the structural break test because it is tedious and the results are never exciting. Another failure mode is exogenous shocks that override the internal feedback loop. Volcanic eruptions disrupt climate oscillation models. Central bank interventions distort market oscillation models. Patent cliff disclosures scramble pharmaceutical innovation models. The workaround is to treat oscillation as the baseline behavior and model shocks as additive noise with fat tails. This is not elegant. It is accurate. Elegant models fail faster in my experience. If you need to forecast oscillation behavior beyond two or three periods ahead, consider switching to agent-based modeling. It runs slower and requires more data but captures the heterogeneity that differential equations smooth over. I use NetLogo for preliminary exploration and Python for production runs. The transition from analytical to computational methods is unavoidable once your system has more than three interacting feedback loops. That threshold is lower than you would expect. Four loops and you are done with closed-form solutions.
Measurement Techniques That Actually Work
Start with a periodogram or Welch's method to identify dominant frequencies in your time series. Remove the mean and apply a window function. Without the window function, spectral leakage will make every frequency look like it has energy. I wasted a quarter of a budget on false signals caused by rectangular window leakage before someone pointed it out. Hanning or Hamming windows cost almost nothing computationally and eliminate that class of error entirely. After identifying dominant frequencies, test for stationarity using the KPSS test. If your series is non-stationary, difference it and retest. Do not skip this step. Non-stationary oscillation analysis produces spurious periodicities that look convincing until they do not. I have seen this destroy at least two portfolios personally. The losses were educational but expensive. For multivariate systems, compute cross-spectral density to measure coherence between variables at each frequency. This tells you whether two oscillating systems are coupled at specific periods. Market returns and volatility show high coherence at sub-annual frequencies during crisis periods but low coherence during calm stretches. Climate temperature and ocean heat content maintain coherence across almost all frequencies because the coupling is physical rather than behavioral. Innovation adoption speed and competitive intensity show coherence primarily at the adoption peak frequency. These differences matter when you build forecasting models.
The practical takeaway is that oscillation analysis is descriptive first and predictive second. Use it to understand system structure before you use it to make decisions. The people who treat it as a crystal ball tend to lose money, misallocate resources, or both. I wrote this because I have seen both outcomes repeatedly. The pattern is consistent across every domain I have tracked.