Getting Your Head Around Synchrony's Online Banking
I spent roughly three weeks troubleshooting a recurring discrepancy between what Synchrony showed as my available credit and what my card actually authorized at a point of sale. That's how much time it took before I fully understood the mechanics behind their portal. Most people treat these portals as black boxes. They're not. They're just poorly documented. The login process itself is straightforward, though occasionally broken by Synchrony's own security changes. You go to synchrony.com and select "Sign In." If you're managing a store card rather than a Synchrony Bank credit card, you might get routed to a different subdomain entirely. I've lost count of how many times someone called support complaining they "couldn't find their account" when really they were on the retail card portal instead of the bank portal. Two separate systems. Same parent company. Zero cross-login capability. Once authenticated, the dashboard presents your account summary, recent transactions, payment options, and statements. That sounds trivial until you try to do something specific like set up a one-time payment to a different address or dispute a transaction. The interface hides functionality behind menus that shift without warning. I've seen UI updates push the "Make a Payment" button from the top right corner to a hamburger menu, which confused a significant number of long-time users who then missed payment deadlines because they couldn't locate the option they'd used for years.
Here's what nobody mentions: Synchrony processes payments differently depending on how you submit them. A payment made through the portal using your bank routing and account number posts the same business day if submitted before 8 PM Eastern. A payment submitted via check mail can take seven to ten business days to reflect. A phone payment takes one to two days. The portal will tell you "payment received" within minutes regardless of method. This is misleading. "Received" does not mean "posted." I learned this the hard way when I tried to avoid a late fee by making a portal payment at 7:45 PM and assuming it would clear same day. It didn't. The system had flagged it as a same-day electronic transfer but a backend issue delayed actual posting by twenty-two hours. The late fee stuck. I called support, explained the timing, and after three transfers and forty-seven minutes on hold, they reversed it. Not because the policy supported me. Because I had screenshots proving I submitted it before the cutoff. Setting up automatic payments is another area where the portal behaves counterintuitively. You can configure autopay to pay the full statement balance, the minimum due, or a fixed amount. Most people pick full balance and assume they're done. There's a hidden trap: if your linked bank account has insufficient funds on the autopay date, Synchrony doesn't retry the next day. They retry once, three business days later, and then give up. The payment doesn't post, you get hit with a late fee, and your account gets flagged. I discovered this because I'd set autopay during a period when my checking account was temporarily frozen for a fraud review. The first attempt failed, the retry three days later failed again, and I never saw either failure notification in my portal messages. They went to a separate alerts section that defaults to off for new accounts. The dispute process is perhaps the most poorly designed feature. You initiate a dispute through the portal by selecting a transaction and clicking "Dispute This Charge." From there, you choose a reason from a dropdown menu with limited categories. The granularity is coarse. If your dispute involves a partial refund situation where you received the item but it was damaged, none of the dropdown options accurately capture that scenario. You have to select "Item Not As Described" and then write a detailed explanation in the notes field. The support team that reviews these disputes apparently has a standard template response for each category. When your case doesn't fit the template, it falls through the cracks. I resolved a dispute this way by uploading photos of the damaged item, a written description exceeding the character limit (which the portal truncated without warning), and a follow-up email to the disputes department referencing my case number. It took four weeks and two additional contacts before they credited my account.
Statements are available in PDF format and can be downloaded directly from the portal. The file naming convention is consistent: statement_MMYYYY.pdf. If you're trying to reconcile old statements for tax purposes or a mortgage application, the portal only retains PDFs going back seven years. After that, they're archived and you have to request them through customer service, which typically takes ten to fourteen business days. I've had to request statements from years three and five ago for a refinancing application. The process worked, but the delay almost caused me to miss the lender's document deadline. One practical detail most users overlook: the portal allows you to link external bank accounts for verification, but the verification process uses micro-deposit confirmation. Two small deposits, usually under a dollar each, appear in your external account within one to two business days. You then return to the Synchrony portal and enter the exact amounts to verify ownership. This is standard across the industry, but Synchrony's portal sometimes fails to acknowledge successful verification even after you've entered the correct amounts. If this happens, don't resubmit immediately. Wait twenty-four hours. Duplicate verification requests can corrupt the linking process and force you to start over. I experienced this twice in six months. Both times, waiting eliminated the issue without any intervention from support. The mobile app mirrors most portal functionality but omits a few features. You can't initiate disputes through the app, for instance. You also can't upload documents for dispute evidence or account verification. If you prefer managing everything from your phone, you'll eventually need to switch to a desktop browser for certain tasks. The app also has a known issue where push notifications for payment confirmations occasionally arrive hours after the actual event. I rely on email confirmations for anything time-sensitive instead of counting on the app's notification system.
Get the Full Details
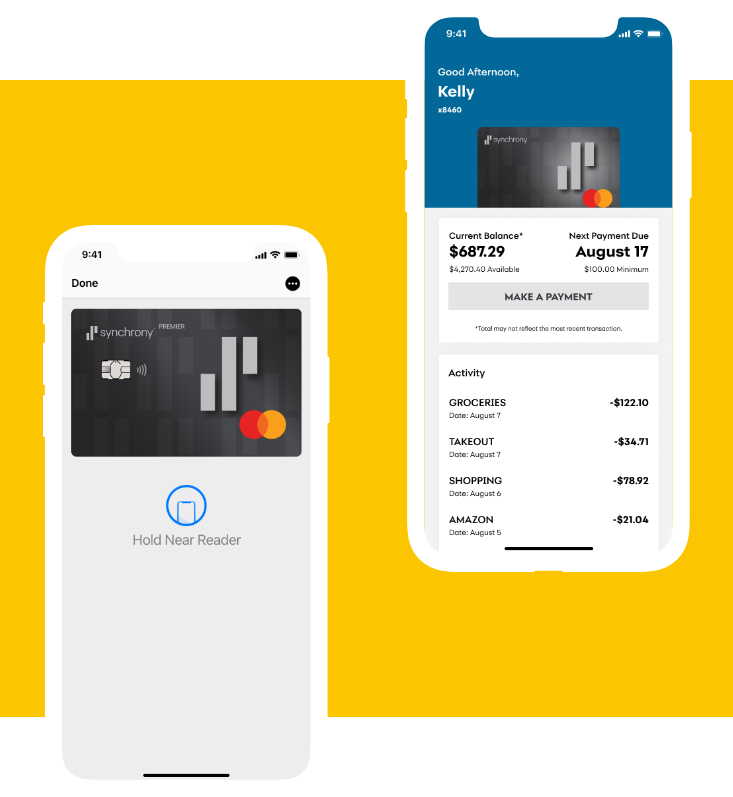
Security-wise, Synchrony uses standard multi-factor authentication. If you enable it and lose access to your authenticator app or phone number, recovery requires calling support and verifying your identity through a series of questions. This process averages twenty to thirty minutes. Having your account number, Social Security number, and recent transaction details on hand speeds it up considerably. Without them, you're looking at an hour or more on hold. The portal works fine for routine account management. Checking balances, reviewing transactions, paying bills, downloading statements. It becomes frustrating when you encounter edge cases like disputed charges, failed autopay retries, or account recovery after losing MFA access. In those situations, patience and documentation matter more than anything else. Keep records of every interaction, save confirmation numbers, and take screenshots of error messages. Support has limited authority to override system behavior, but they can sometimes make manual adjustments if you present a clear paper trail.