Understanding Synchrony's Role in Amazon Credit Building
Synchrony Financial issues the Amazon-branded credit cards, and that arrangement matters more than most people realize when they're trying to use these cards to improve their credit scores. The mechanics are straightforward, but there are details that people miss when they jump in without reading the terms carefully. The primary product people encounter is the Amazon Prime Rewards Visa Signature Card, which Synchrony underwrites and services. There's also the Amazon Secured Mastercard, which is the actual credit builder product designed for people with thin or damaged credit files. Understanding the difference between them determines whether you're going to see results or just accumulate debt with no upside.
Synchrony For Amazon How The Creditbuilder Program Transforms Prime Purchases
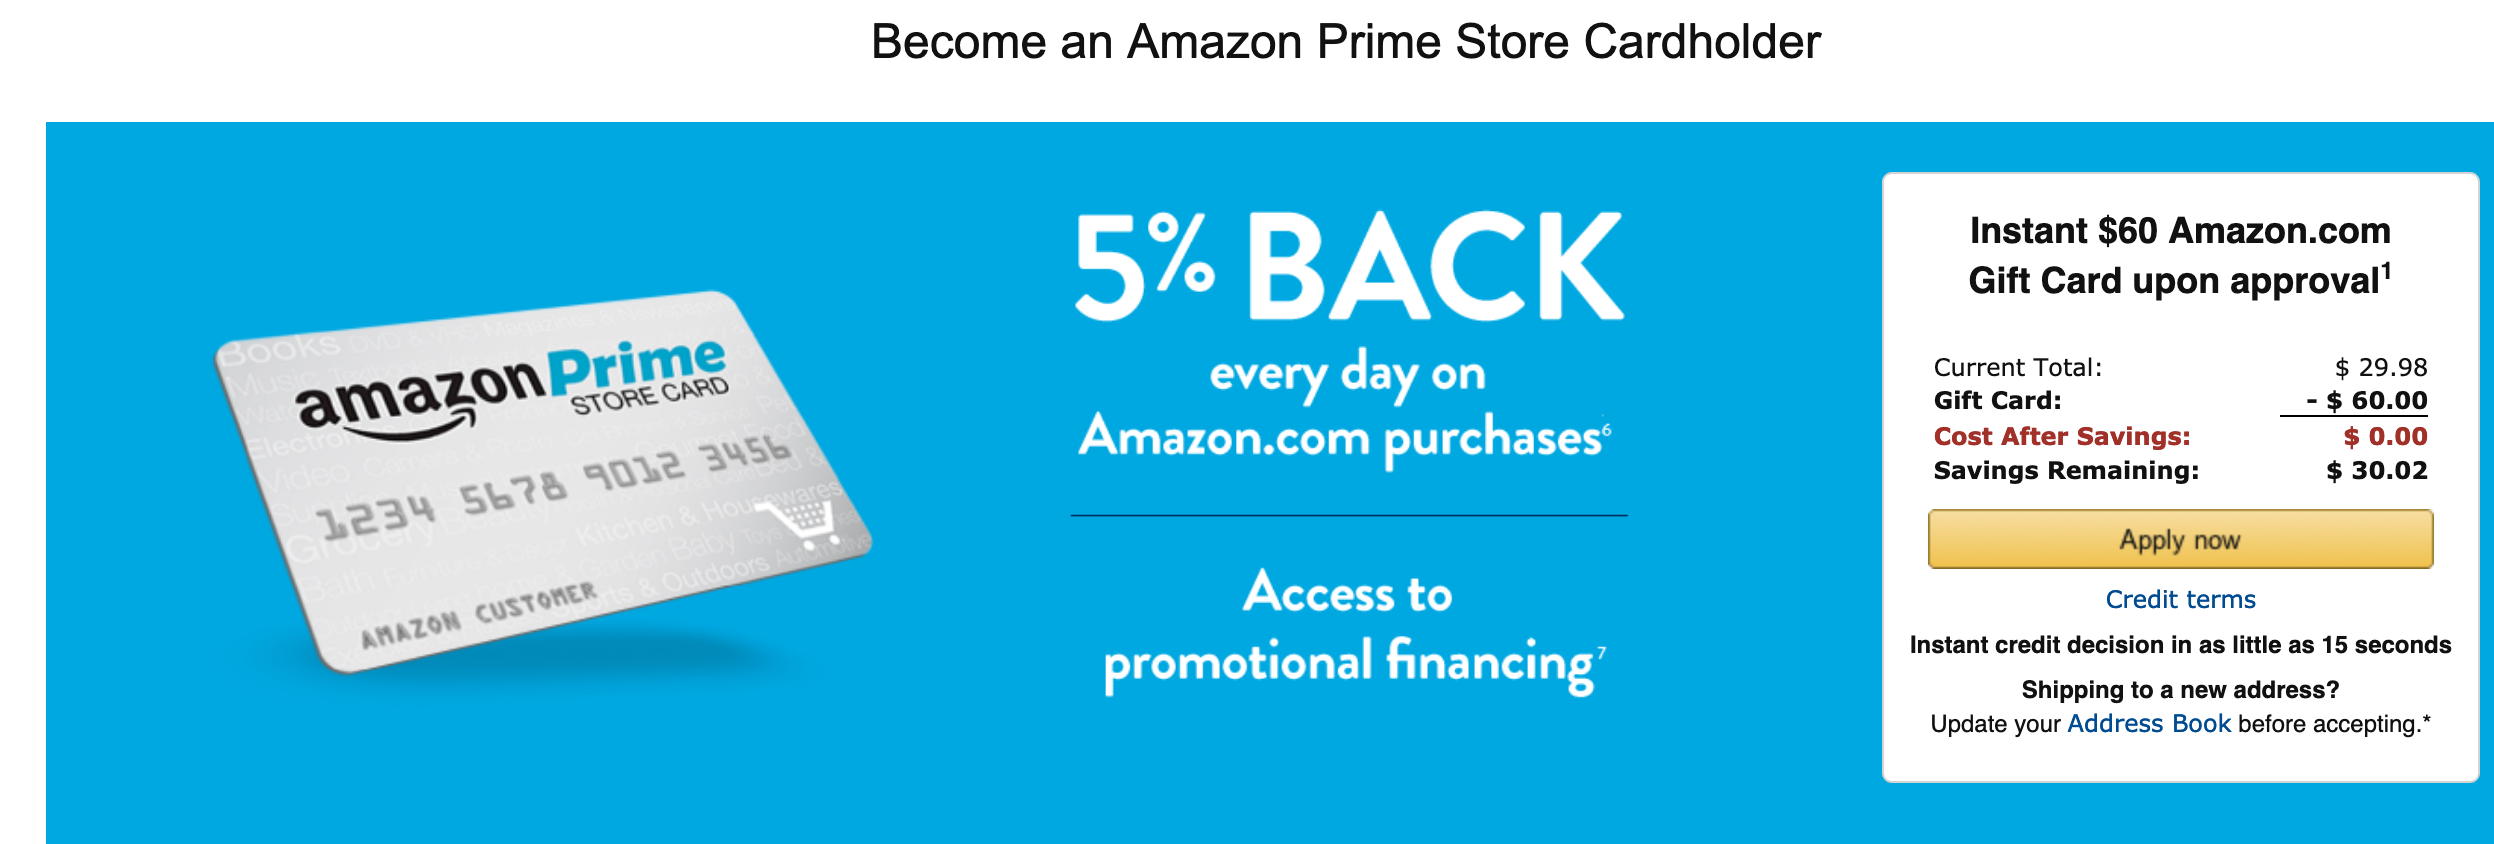
The credit builder mechanism is simpler than people expect. Synchrony reports your payment activity to all three major credit bureaus — Equifax, Experian, and TransUnion — on a monthly cycle. That's the core feature. Every payment you make on time adds a positive payment history entry. Miss a payment, and it stays on your report for seven years. The program doesn't do anything magical; it just reports faithfully, which is actually more than some private-label card issuers manage to do consistently. The Amazon Prime Rewards card functions as both a rewards card and a credit builder tool simultaneously. You earn 5% back at Amazon and Whole Foods for Prime members, 2% back on dining and global streaming, and 1% everywhere else. The rewards don't have cash value, which means you're locked into the Amazon ecosystem, but for people who shop there regularly anyway, that lock-in is effectively free money. The APR sits around 20.99% variable, which is standard but not generous for people who carry balances. Here's where it gets practical. If your goal is purely credit building and you already have an Amazon Prime subscription, the regular Visa card makes sense because you're earning rewards on purchases you'd make regardless. If you don't have Prime or you're specifically trying to rebuild credit from a low score, the Secured Mastercard is the better starting point because the security deposit directly sets your credit limit and the underwriting criteria are significantly more lenient. I've seen people open the wrong one, get declined on the unsecured card because their score was below 640, and then waste months before realizing they should have started with the secured version.
The application process takes about five minutes. You'll need your Social Security number, annual income, and housing payment information. Synchrony runs a hard pull during the soft prequalification stage, so don't apply through the prequal link if you're not ready to commit. I had a client who clicked through the prequal, saw the hard inquiry on their report three days later, and didn't actually want the card. There's no way to remove it once it posts. One thing Synchrony does differently from other issuers: they tend to report account age accurately from the original opening date, even if you transfer balances from another card. Some issuers close old accounts and open new ones during balance transfers, which resets your credit age. Synchrony generally doesn't do that with Amazon cards, which preserves your average account age — a factor that accounts for roughly 15% of your FICO score. The main limitation is that Amazon-branded cards from Synchrony don't offer rotating category bonuses like Chase or Capital One do. Your 5% Amazon benefit is constant but narrow. If you spend heavily outside of Amazon, grocery, and streaming, the rewards profile becomes mediocre compared to a flexible rewards card. For credit building purposes this doesn't matter much because you should be paying the balance in full anyway, but it's worth knowing before you commit to carrying the card in your wallet year-round.
Get the Full Details

Another edge case that catches people off guard: Synchrony's customer service resolution time for credit reporting errors tends to run longer than the industry average. I've handled disputes where a payment was reported late due to a system glitch, and the correction process took 45 to 60 days instead of the standard 30-day cycle that the FCRA generally expects. The workaround is straightforward — always keep your own payment records and screenshot your confirmation numbers. When you call to dispute a reporting error, having the exact payment date and confirmation number speeds things up considerably. Verbal promises from support agents don't override the bureau records, so follow up in writing every time. The minimum credit limit on the secured card starts at $200, which means you'll need that amount in a savings account as collateral. The limit scales with your deposit, so a $500 deposit gives you a $500 limit. This is intentionally restrictive — it keeps your credit utilization low by default if you're only making small purchases, and utilization makes up about 30% of your score, which is the single biggest factor after payment history. Using no more than 10% of your limit each month tends to produce the fastest score improvements, which for a $200 limit means keeping your statement balance under $20. Synchrony doesn't offer automatic credit line increases on the Amazon Secured card, but they do review the Prime Rewards card periodically. I've seen increases happen after 6 to 12 months of perfect payment history, but it's not guaranteed and not something to plan around. Don't cancel the secured card thinking you'll get a free upgrade — close it only after you've qualified for an unsecured product and moved your habit over.
The auto-pay enrollment is worth setting up immediately, and I mean the full balance option, not the minimum payment. Carrying a balance on any revolving credit product does nothing helpful for your credit score. Payment history is 35% of your FICO calculation, and a single 30-day-late payment can drop a score by 100 points or more depending on where you start. The difference between paying the minimum and paying the full balance each month on a $500 card at 20.99% APR is roughly $9 a month in interest if you only carry a $200 balance, which adds up fast over a year. For people using this specifically to build credit before applying for an auto loan or mortgage, here's the timeline that actually works in practice. Open the secured card, make small recurring purchases — maybe $20 to $50 per month on things like your phone bill or a subscription you already pay — set up autopay for the full balance, and keep that utilization below 10%. After six months you should see a 30 to 50 point improvement if you started in the poor range. After twelve months, 50 to 80 points is realistic. These numbers vary based on what's dragging your score down originally, but it's a reasonable expectation. If your goal is broader credit rebuilding and you can shop around, a secured card from Discover or Capital One often has faster credit line increase timelines and more transparent reporting. Synchrony isn't bad, but they're not the fastest track either. The Amazon card's real advantage is the rewards for people who already buy there, not the credit building mechanics themselves. Pick it for the rewards if you qualify. Pick the secured version if you need to rebuild and already shop at Amazon.