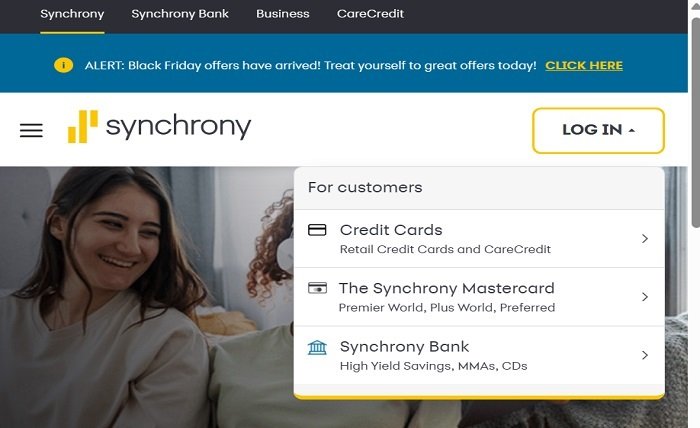
Running an account online with Synchrony isn't as clean as the website makes it look
I've been using Synchrony Bank's digital platform for about four years now, mostly for the higher-yield savings options and occasional retail financing accounts. The interface works fine for basic tasks, but there are enough quirks that a proper walkthrough would actually save you some headaches. Here's how it operates when nobody is selling you anything. The core platform lives at synchrony.com under the "My Account" portal. You log in with your username and password, then get routed to a dashboard that aggregates all your linked accounts. From there you can check balances, transfer money between your own accounts, set up one-time or recurring payments, download statements, and contact support through the chat function. That last part is worth flagging upfront because the chat routing is inconsistent depending on which product you're logged into. What most people don't realize is that Synchrony separates its retail credit products from its deposit products in ways that aren't obvious. If you have a PayPal Credit account and a high-yield savings account, they show up on the same dashboard, but they pull from different backend systems. Transferring money between them isn't a native feature. You have to move funds through an external bank account as an intermediary. I learned this the hard way during a budget crunch when I had money sitting in my Synchrony savings but needed to pay down a retail financing balance immediately. The transfer window wouldn't let me do it directly. I ended up wiring to my Chase checking first, then paying the financing balance from there. Took about forty minutes and two authentication steps that weren't flagged as warnings.
The mobile app mirrors most of the web functionality, but it trims certain features. Statement requests that span more than twelve months disappear from the app interface entirely. If you need historical documents for tax purposes or loan applications, use the desktop site. The app will tell you the document isn't available, which is accurate but not particularly helpful in the moment. Here's a detail beginners miss: Synchrony uses a rolling statement system rather than generating statements on a fixed calendar date for every product type. Your savings account statement probably comes out around the fifteenth of each month. But if you have an installment loan through Synchrony, that statement could drop on the third or the twenty-second depending on when the account was opened. I once thought I'd missed a payment because I was expecting my loan statement on the same schedule as my savings, and it wasn't there yet. Checking the "Messages" center inside the portal revealed the statement had posted three days early. The notification email also went to a secondary inbox I'd forgotten about. Setting up a forward rule for synchrony.com emails to your primary address now prevents that problem entirely. Two-factor authentication is mandatory but configured differently depending on how you signed up. Some accounts push to an authenticator app by default. Others rely on SMS codes. The setup screen tells you which method is active, but it doesn't make clear that you can add a second method afterward. I switched from SMS to an authenticator app after my phone number changed, and the portal allowed both methods to remain active simultaneously during the transition period. That overlap window matters if your old number gets recycled quickly. Keep both methods enabled for at least thirty days after any change.
Customer support through the portal chat operates during unusual hours for this industry. Most banks close live chat around nine PM Eastern. Synchrony keeps it running until midnight, sometimes later on weekdays. I've called on a Saturday at eleven-thirty Eastern and actually reached a real person instead of a bot loop. The tradeoff is that response quality drops noticeably after ten PM. Answers become templated and escalations take longer. If your issue is complex, schedule the call earlier in the evening. Direct deposit setup requires routing and account numbers that the portal displays under the account details page. The routing number is standard across all Synchrony savings and deposit products. But the account number format changed recently for newer accounts. If someone sent you a PDF guide that still shows the old twelve-digit format and your new account has a longer string, the direct deposit will reject. The portal reflects your actual account number on the details screen. Don't trust archived documentation from forums or older blog posts. Always verify against what the portal shows right now. The dispute resolution process for transactions is another area where expectations don't match reality. Synchrony handles disputes differently depending on whether the charge came through a retail financing transaction or a standard bank transfer. Retail charges route through a third-party mediation process that can take forty-five to sixty days. Standard disputes move faster, usually resolved within fifteen business days. When I disputed a duplicate billing error on a financed appliance purchase, the agent on chat didn't clarify which track my case was on until I asked directly. It was on the slower track. I wouldn't have accepted that timeline if I'd known upfront. Ask which dispute category your issue falls into before you start the process. It changes how long you wait significantly.
Get the Full Details

One feature that genuinely works well is the automated savings round-up tool. It links to an external checking account and sweeps spare change into your Synchrony savings on a daily basis. The yield on those small balances is better than most big-box banks offer, though the rate fluctuates with the federal funds rate. Setting it up takes about eight minutes. Linking the external account requires micro-deposit verification, which adds two to three business days to the process. I recommend starting this setup early if you want the round-ups active before the end of a billing cycle, because the synchronization delay means your first sweep won't happen until the external account is fully verified. The biggest frustration with the platform is its search function inside the message center. It's essentially broken for anything older than six months. If you're looking for a specific correspondence about a rate change or a policy update from last winter, typing keywords won't reliably surface it. The workaround is to use the statement download feature instead, pulling the PDF directly, or to request assistance through chat and ask the agent to pull up the specific message reference number. It's not ideal but it gets the job done without requiring a phone call during business hours. Overall the platform covers the essentials adequately. It's not elegant. Certain workflows require workarounds that should be built in. But for managing a high-yield savings account and handling retail financing on the same login, it does what it needs to without excessive friction once you know where the bumps are.


