The Structure Behind Symmetry Financial Group
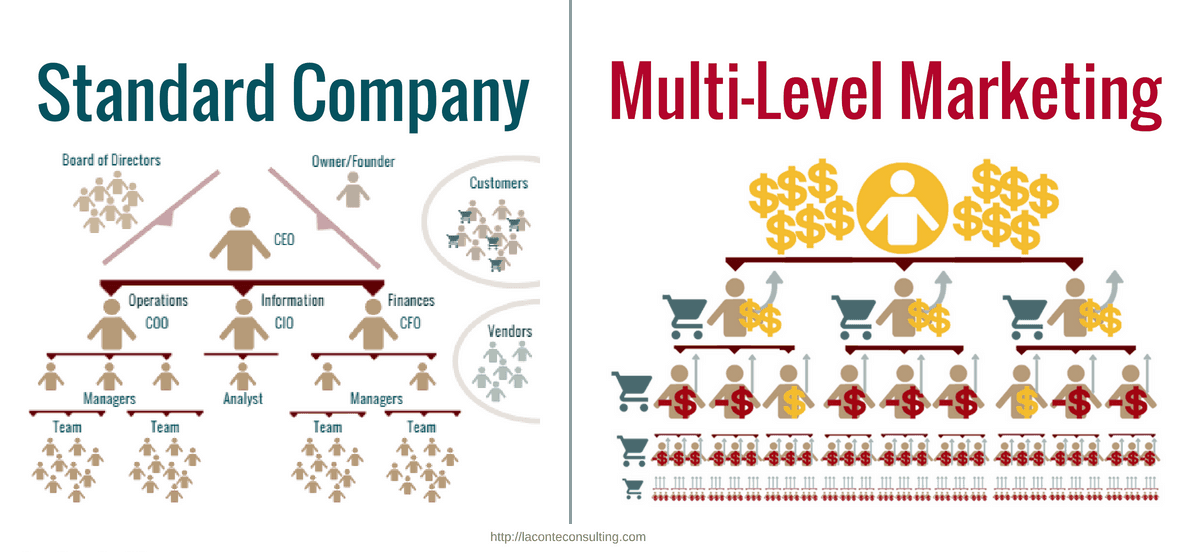
Most people who ask about Symmetry Financial Group are trying to figure out if they should join as a distributor or avoid it entirely. The answer depends on whether you understand how the compensation structure actually works before signing anything. Symmetry Financial Group operates as a direct sales organization for financial products. Independent agents or distributors sell life insurance, annuities, and other financial products to clients. The company provides the licensing support, training materials, and product access. What makes people call it an MLM is the referral-based compensation model where distributors can earn overrides from the business they recruit.
Symmetry Financial Group Mlm Or Not Dissecting The Controversy Structure And Reality Of The Opportunity
Here is the straightforward breakdown. An MLM generates most of its revenue from recruiting new members who pay to join. A direct sales company generates revenue from actual product sales to end consumers. Symmetry Financial Group sits in a gray area that explains the controversy. You do need to purchase training materials and maintain certain requirements to stay active, but the core income comes from selling real financial products with actual commissions. The recruiting component exists, but it functions more like a team-building bonus structure than a pyramid. I spent about two years working closely with agents who were either in Symmetry or considering joining. The ones who made money consistently treated it as a proper insurance and annuity business. The ones who complained usually misunderstood the earning timeline. Commission payouts in this industry are structured differently than most people expect. Your first check does not come from a sign-up fee. It comes when a client policy actually stays in force through the first premium payment cycle, and sometimes longer depending on the product type. The real nuance that almost nobody mentions is the difference between trailing commissions and initial commissions. Initial commissions can range from 40 to 100 percent of the first year premium depending on the product and your agent level. Trailing commissions are much smaller, typically 2 to 5 percent annually, but they stack up over time as your book of business grows. This is where the team override structure matters. If you build a team of active agents, you can earn a small percentage of their trailing commissions. That percentage is usually between 1 and 3 percent, and it only applies if your team members are generating legitimate premium volume.
The edge case I encountered that nobody warns you about involves state licensing. Not every state accepts the same pre-licensing education or continuing education credits across all carriers. I had a distributor in Texas who thought he was set because he completed the Symmetry-provided coursework. He ran into a wall when trying to get appointed with certain carriers because Texas requires specific credit hour breakdowns that the general training program did not cover. The workaround was straightforward but tedious. He identified which carriers he wanted to work with first, pulled each carrier's specific licensing requirements, and then filled the gaps through additional state-approved courses. This took roughly three extra weeks and cost him about four hundred dollars out of pocket. If you are serious about this, do not assume the training package covers every state and carrier combination. Map it out yourself before you start spending money. Another counter-intuitive point: the compensation plan looks generous on paper but the fine print matters enormously. Some override tiers have volume thresholds that are difficult to maintain during your first twelve months. I watched several agents hit a recruitment milestone that would have pushed them to a higher override percentage, only to drop back down because their team members failed to produce enough premium to sustain it. The structure rewards consistency, not recruitment speed. Fast recruiters who cannot convert recruits into productive agents end up exactly where they started financially, minus their initial investment. The downsides are real and worth listing plainly. Your income is irregular, especially early on. You are responsible for your own lead generation unless the company provides it through specific programs that may require additional fees. There is competition from other financial product distributors in your geographic area. The company has faced complaints online about support responsiveness and policy processing delays, which is common in the insurance distribution space but still frustrating when it happens to your clients. And if you are counting on the recruiting bonus as your primary income source, you are likely misreading the opportunity. The recruiting component is supplementary at best for the vast majority of participants.
Get the Full Details
For anyone considering this, I would recommend starting with a clear plan that prioritizes direct client sales over recruitment. Get your licensing sorted for your target states first. Understand the commission schedule for each product category before you present anything to a prospect. Track your actual expenses including licensing fees, continuing education, software subscriptions, and marketing costs against realistic commission projections. Most beginners overestimate their earning potential in the first year by a factor of two or three because they do not account for the ramp-up period or the attrition rate of clients who lapse their policies. If you already have an established book of insurance or annuity business and want a broader product lineup to offer your existing clients, Symmetry Financial Group can be a reasonable option. If you are looking for a quick way to make money with minimal effort through recruitment bonuses, you are better off looking elsewhere. The structure does not support that expectation, and the people who push it that way are usually the ones who did not read the compensation plan carefully enough to understand how it actually works.