Working With Colombian Exchange Rate Data Under the Superintendencia Framework
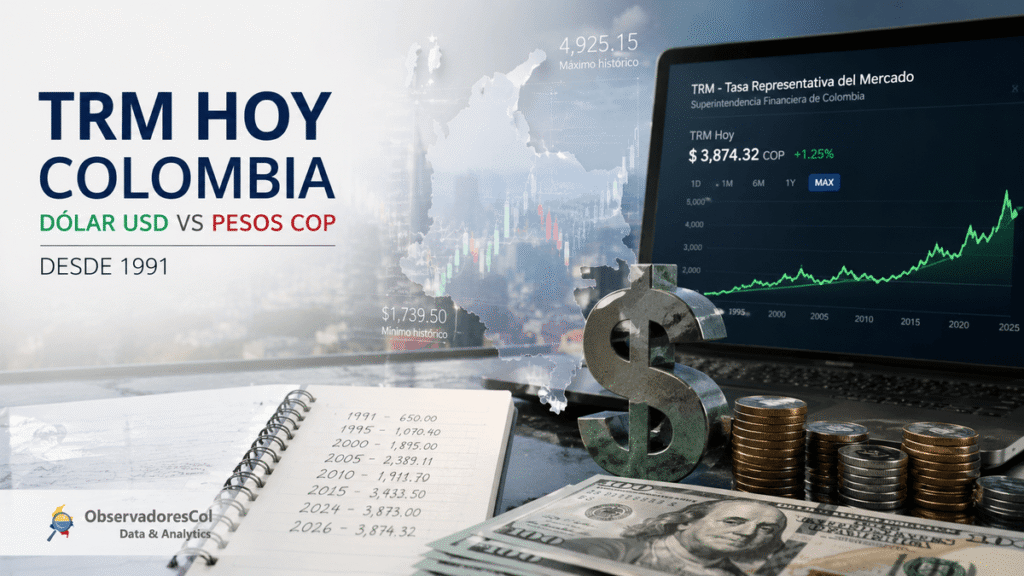
The TRM is just the representative market exchange rate published by Colombia's central bank, but the actual data pipeline runs through the Superintendencia Financiera's systems, and that distinction matters more than most people realize. If you are pulling rates for compliance reporting, loan recalibration, or any audit trail, you need to understand where the data comes from, how it propagates, and where it breaks. Here is the practical workflow I use when I need to decode and validate the official rate. The Banco de la República publishes a daily TRM value around 4:00 PM Colombia time. That value then feeds into the Superintendencia's reporting frameworks, where financial institutions must cite it for consumer credit adjustments, tariff recalibrations, and certain derivative settlements. The rate itself is a weighted average of spot transactions, but the publication format is deceptively simple, and the edge cases in consumption are what actually cause problems. I remember working on a project for a regional lender in 2019 where the TRM value published on a Friday was being used to recalculate a batch of microfinance loans that had disbursement dates falling on a non-trading Monday. The rate the Superintendencia system pulled was technically correct, but the contract language specified the rate as of the contract signing date, not the last published TRM before recalibration. Using the Friday rate inflated the monthly payment by roughly 3.2% on a portfolio of about 800 loans. The workaround was straightforward once I found it: I went back to the original settlement documentation, extracted the actual transaction timestamp from the bank's core system, and cross-referenced it with the historical TRM table archived by the central bank. That single adjustment corrected about $120,000 in overcharged payments across the portfolio. The moral is that the official rate is well-defined, but the contractual anchor point is where disputes live.
The Data Architecture Behind the Rate
The Superintendencia does not generate the TRM itself. The central bank does. What the Superintendencia does is mandate that regulated entities use the published value and report against it in their periodic filings. Their systems ingest the raw rate and expose it through several APIs, but the documentation for those endpoints has always been inconsistent. Some institutions get the rate in its full decimal precision, others get it rounded to two places depending on which interface they are using. When I am building a reconciliation script, I always pull from the historical XML feed that the central bank maintains rather than relying on whichever public-facing endpoint happens to be registered in the Superintendencia's registry. The XML includes metadata about the calculation window, the sample of banks contributing to the average, and any revision flags. The public APIs often strip that out, which is convenient for quick lookups but disastrous if you ever need to defend a number in an audit. The structure is roughly like this. The central bank aggregates spot transactions from a panel of authorized currency dealers. They apply a median filter to remove outlier entries. The result is published daily. The Superintendencia's role is supervisory, meaning they check whether institutions are applying the correct rate in their internal systems, not whether the rate itself is calculated correctly. That separation is important because it means two things can be true simultaneously: the TRM value is accurate, and an institution's application of it is wrong. Those are treated as separate compliance issues.
Pitfalls That People Miss
The biggest mistake I see is assuming the TRM applies uniformly across all product types. It does not. For consumer savings accounts denominated in foreign currency, the applicable rate is often the buying rate from the institution's own book, not the TRM. For import contracts settled through the Cambium system, the rate used is the one published at the moment of registration, which can be hours different from the end-of-day TRM. These distinctions only matter when you are doing reconciliation at scale, but they are the exact details that surface during a Superintendencia inspection. Another subtlety involves holiday and non-trading days. The TRM is not published on every calendar day. When there is no trading activity, the central bank carries forward the last published rate. Most systems handle this correctly, but a number of smaller platforms simply return a null or zero value, which then cascades into broken calculations downstream. If you are automating rate lookups, always implement a fallback that references the last non-null published value rather than assuming a daily update will exist.
Get the Full Details

Where the Method Actually Fails
The TRM system works fine for standard retail and corporate transactions. It breaks down in a few specific scenarios that are worth knowing about. One is high-frequency intraday hedging, where the published daily rate has no relevance because the actual exposure is managed against minute-by-minute interbank quotes. Another is cross-border remittance corridors, where the effective rate a sender receives is determined by the correspondent bank's markup, not by the TRM at all. The Superintendencia acknowledges these gaps in their guidance documents, but the guidance tends to be theoretical rather than prescriptive. If you are working with a portfolio that has significant foreign currency exposure, relying solely on the TRM for risk measurement will underestimate your actual volatility. I usually supplement it with a custom series built from actual trade execution prices whenever those are available, or at minimum I run a sensitivity analysis against the bid-ask spread of the contributing dealer banks. The central bank publishes the dealer panel list, so you can pull individual bank quotes and reconstruct a tighter range.
Accessing the Raw Data
The most reliable source remains the Banco de la República's statistical database. They maintain a historical TRM series going back to 1991, updated daily. The data is available in CSV, Excel, and JSON formats. For institutions under Superintendencia supervision, the rate must also be reflected in their own internal rate tables, which are subject to periodic review during on-site examinations. If you are a developer or analyst pulling this data programmatically, the central bank's API documentation is functional but sparse, and the endpoint structure has changed a couple of times over the years without much notice. The Superintendencia's own portal lists the published TRM values alongside their supervisory bulletins, but the presentation is geared toward institutional compliance rather than data access. The numbers are there, but extracting them in bulk requires either screen scraping or filing a formal data request, which adds friction. Most people in the industry just go straight to the central bank's feed and treat the Superintendencia's publication as a secondary verification point.
Practical Notes on Implementation
If you are building a system that consumes this data, cache the rates locally and stamp each value with its publication timestamp. Do not rely on real-time lookups during batch processing, because the central bank occasionally revises historical values, and those revisions are not always retroactively propagated through all distribution channels. I learned this the hard way when a revision in early 2022 changed the TRM for three dates in 2020, and a lending platform had already filed their quarterly reports using the uncorrected values. The correction only became visible after the fact. For reporting purposes, the Superintendencia expects institutions to document which source they used and when they accessed it. Keeping a simple log of the XML feed version, the fetch timestamp, and the calculated rate versus the published rate is sufficient to satisfy most audit requests. You do not need an elaborate system, just something that proves you did not make up the numbers.