How Summer IRS Payment Deposit Timing Actually Works
The IRS doesn't deposit payments on a fixed schedule. They trigger deposits based on batch processing cycles, and during the summer months those cycles shift because everyone's trying to get ahead of the fall filing season or because prior-year corrections are being processed. Most taxpayers think their payment was delayed when it just sat in a queue waiting for the next available batch run. I've seen this play out repeatedly. Last summer, a client was waiting on a make-the-deposit refund from a prior-year amended return. The system showed it as "approved" for nearly three weeks before it actually moved. The trigger wasn't the approval date; it was the next available direct deposit run, which for refunds during that period happened on Tuesdays and Thursdays between 9 AM and 11 AM Eastern time.
Summer IRS Pfd Deposits Timing Triggers And What Taxpayers Need To Know
Here's the breakdown of what actually drives deposit timing during summer and what you can do about it. The IRS runs automated deposit cycles twice per week for most electronic payments. During summer, the primary triggers are: These schedules aren't published anywhere the public can easily find. They're internal processing windows. What you see on "Where's My Refund" is a status indicator, not a deposit confirmation. A deposit might appear as "Payment Sent" in the system but not actually land in your account until the next business day because of ACH settlement times.
I learned this the hard way with a client who had an Additional Child Tax Credit payment scheduled for mid-July. The portal showed it was approved on a Wednesday. She called on Friday expecting the money. It wasn't there. The deposit had been triggered on the Wednesday batch but the ACH settlement hadn't completed by Friday afternoon. The money hit her account Monday morning. I now tell every client: if the IRS says a deposit was sent, don't expect it until at least the next business day, and probably two days out for summer processing.
Get the Full Details
Common Pitfalls That Delay Summer Deposits
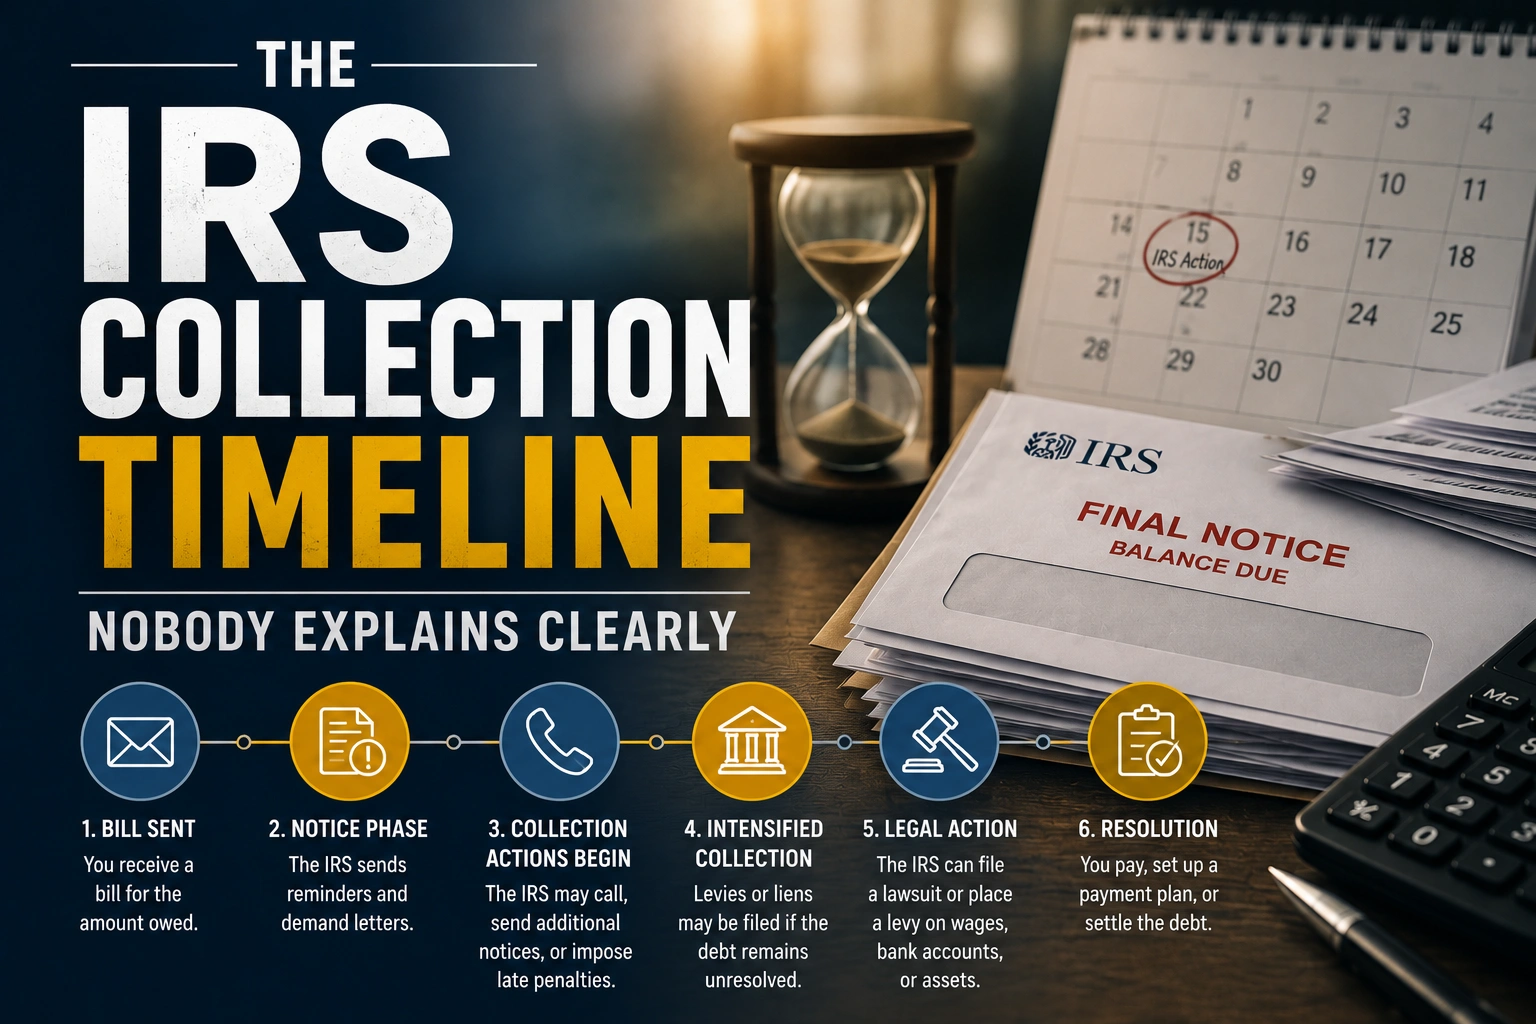
There are several reasons summer deposits take longer than expected, and most of them have nothing to do with the IRS intentionally holding money. Bank verification delays. If you've changed accounts recently or the bank flags a deposit for review, the IRS payment will sit in ACH limbo. This is more common in summer because banks are dealing with higher volumes of account updates during open enrollment seasons. A client of mine had her $4,200 stimulus deposit held for four days because her bank had flagged the routing number as mismatched with her account history. The IRS had no control over this. She had to call her bank directly to clear it. State tax refund synchronization. Some credits that appear as IRS deposits are actually reimbursements from state programs that flow through the IRS treasury. These often get queued differently and can add three to five business days to your timeline. This is particularly relevant for states that process their own refundable credits independently and then coordinate with federal disbursement.
Income verification holds. If your filing triggers an automated review — say, a W-2 that doesn't match what the SSA has on record, or a dependent that wasn't claimed last year — the deposit gets held until the match resolves. The review timeline during summer averages eight to twelve business days, sometimes longer if the IRS is backlogged from peak season carryover.
What You Can Control
You can't speed up the IRS deposit triggers. But you can influence when your payment actually hits your account. Use direct deposit. Paper checks during summer take 7 to 14 calendar days from the trigger date to arrive by mail. Direct deposit typically adds one to two business days to the ACH window, but it eliminates mailing delays entirely. For anything over $1,000, the difference between check and direct deposit is usually three to five business days. Check your IRS account online, not just the refund tracker. The "View Your Account" portal shows you the actual trigger date and batch number. If you see a deposit listed with a "Sent Date" that's more than three business days old and the money isn't in your account, contact your bank first. If the bank says nothing, then you call the IRS. Going the other direction wastes time.
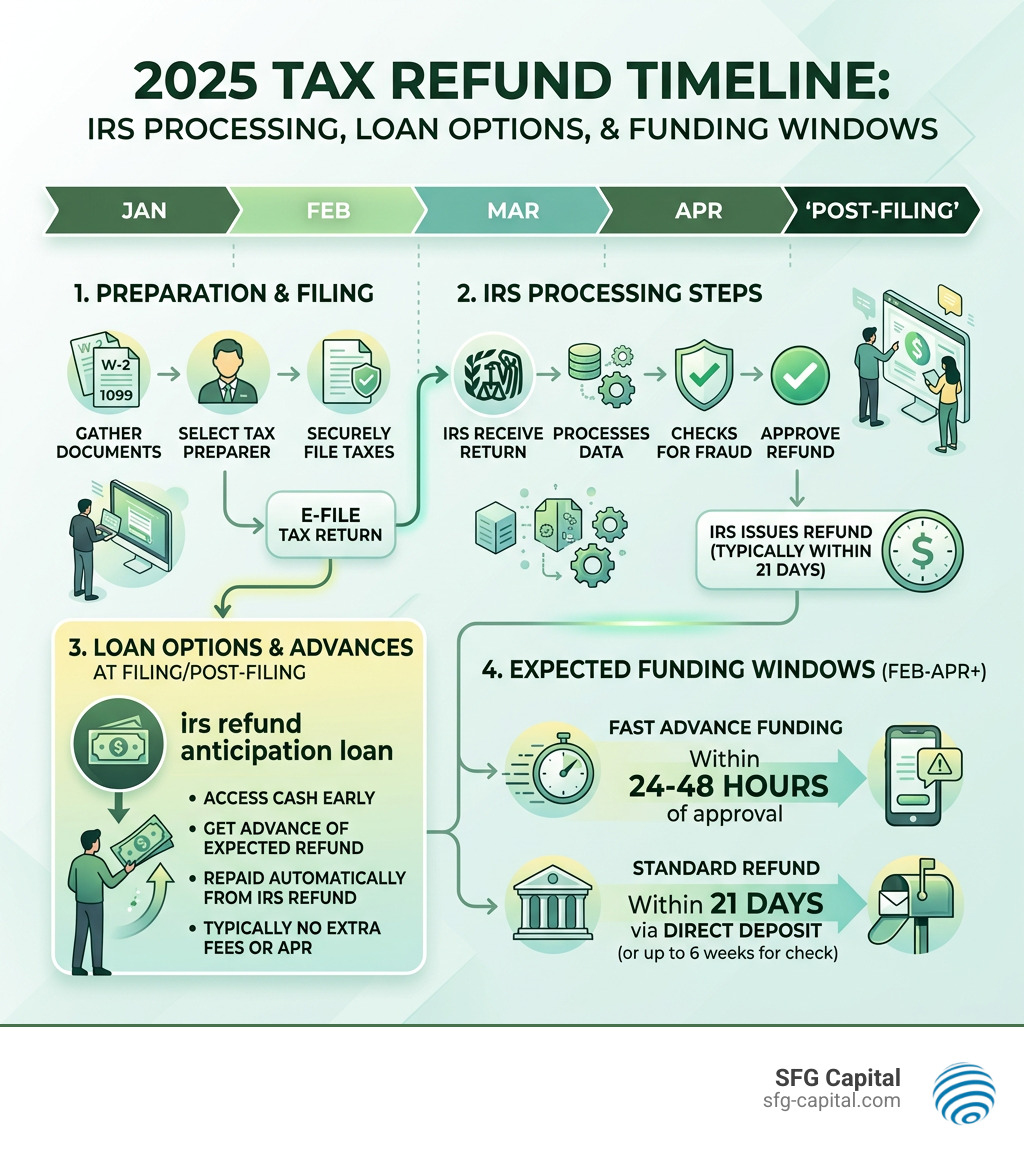
File early if you're expecting a summer credit. Credits like the Child Tax Credit or Earned Income Credit that carry over into summer filings tend to process faster if your return was accepted before June 15. The IRS treats mid-year filings differently from late-year filings in their batch scheduling, and June acceptances generally land in the Wednesday-Friday deposit window by late July.
The Edge Case That Breaks Everything
There's one scenario where summer deposit timing becomes completely unpredictable, and it involves the IRS's Offset and Treasury Cross-Reference system. If you owe past-due child support, federal student loans, or state tax obligations, your refund or credit payment can be intercepted and redirected. The intercept happens at the deposit trigger point, not after. So you might see the deposit as "Sent" in the IRS system, but it lands in a different account or gets withheld entirely. I dealt with a case last August where a taxpayer saw his $2,800 deposit shown as processed on a Wednesday. By Friday, the account was empty. The IRS had offset it for a state tax liability that had been filed but not yet reconciled in their system. The state eventually released the hold, but it took six weeks. The workaround here is to call the IRS refund offset hotline at 1-800-304-3106 and ask specifically whether your payment was subject to an offset. If it was, you'll get the program name and can start the dispute process immediately. Waiting for the money to reappear usually means waiting 30 to 60 days.
When to Stop Waiting and Take Action
If a deposit hasn't appeared five business days after the "Payment Sent" date on your IRS account, that's when you should start making calls. Before that point, you're usually just adding to the queue noise. The IRS call centers during summer are understaffed relative to demand, and a call placed before the five-day mark typically results in a hold and callback you won't get for two weeks. For deposits over $5,000, consider filing Form 1350 if the payment never arrives within ten business days. It's a claim for refund that gets expedited processing. Most people don't know this form exists, and even fewer use it. It's available on the IRS website and requires a brief explanation of the missing payment along with your account information.