How Home Buying Actually Works When You Strip Away the Sales Pitch
The residential real estate market runs on friction. That friction is deliberate. Agents make money on commissions, title companies have layers of processing fees, and lenders will happily upsell you on services you don't need if you don't push back. The people who buy homes without losing sleep or thousands of dollars aren't lucky. They've just learned to navigate the actual process instead of the marketed version. I spent eight years working residential transactions — mostly on the buyer side, some on the seller side, a few as a translator when both sides got confused. The difference between a stressful close and a smooth one rarely comes down to the house itself. It comes down to paperwork timing, inspection knowledge, and not signing anything you don't understand before you sign it. I've seen buyers walk away from deals after inspection because the foundation report showed signs of movement they didn't catch themselves. I've also seen buyers get burned because their agent told them "everything looks fine" without reading the actual inspection summary.
Straightforward Home Buyers Your Quick Guide To A Stressfree Buying Experience
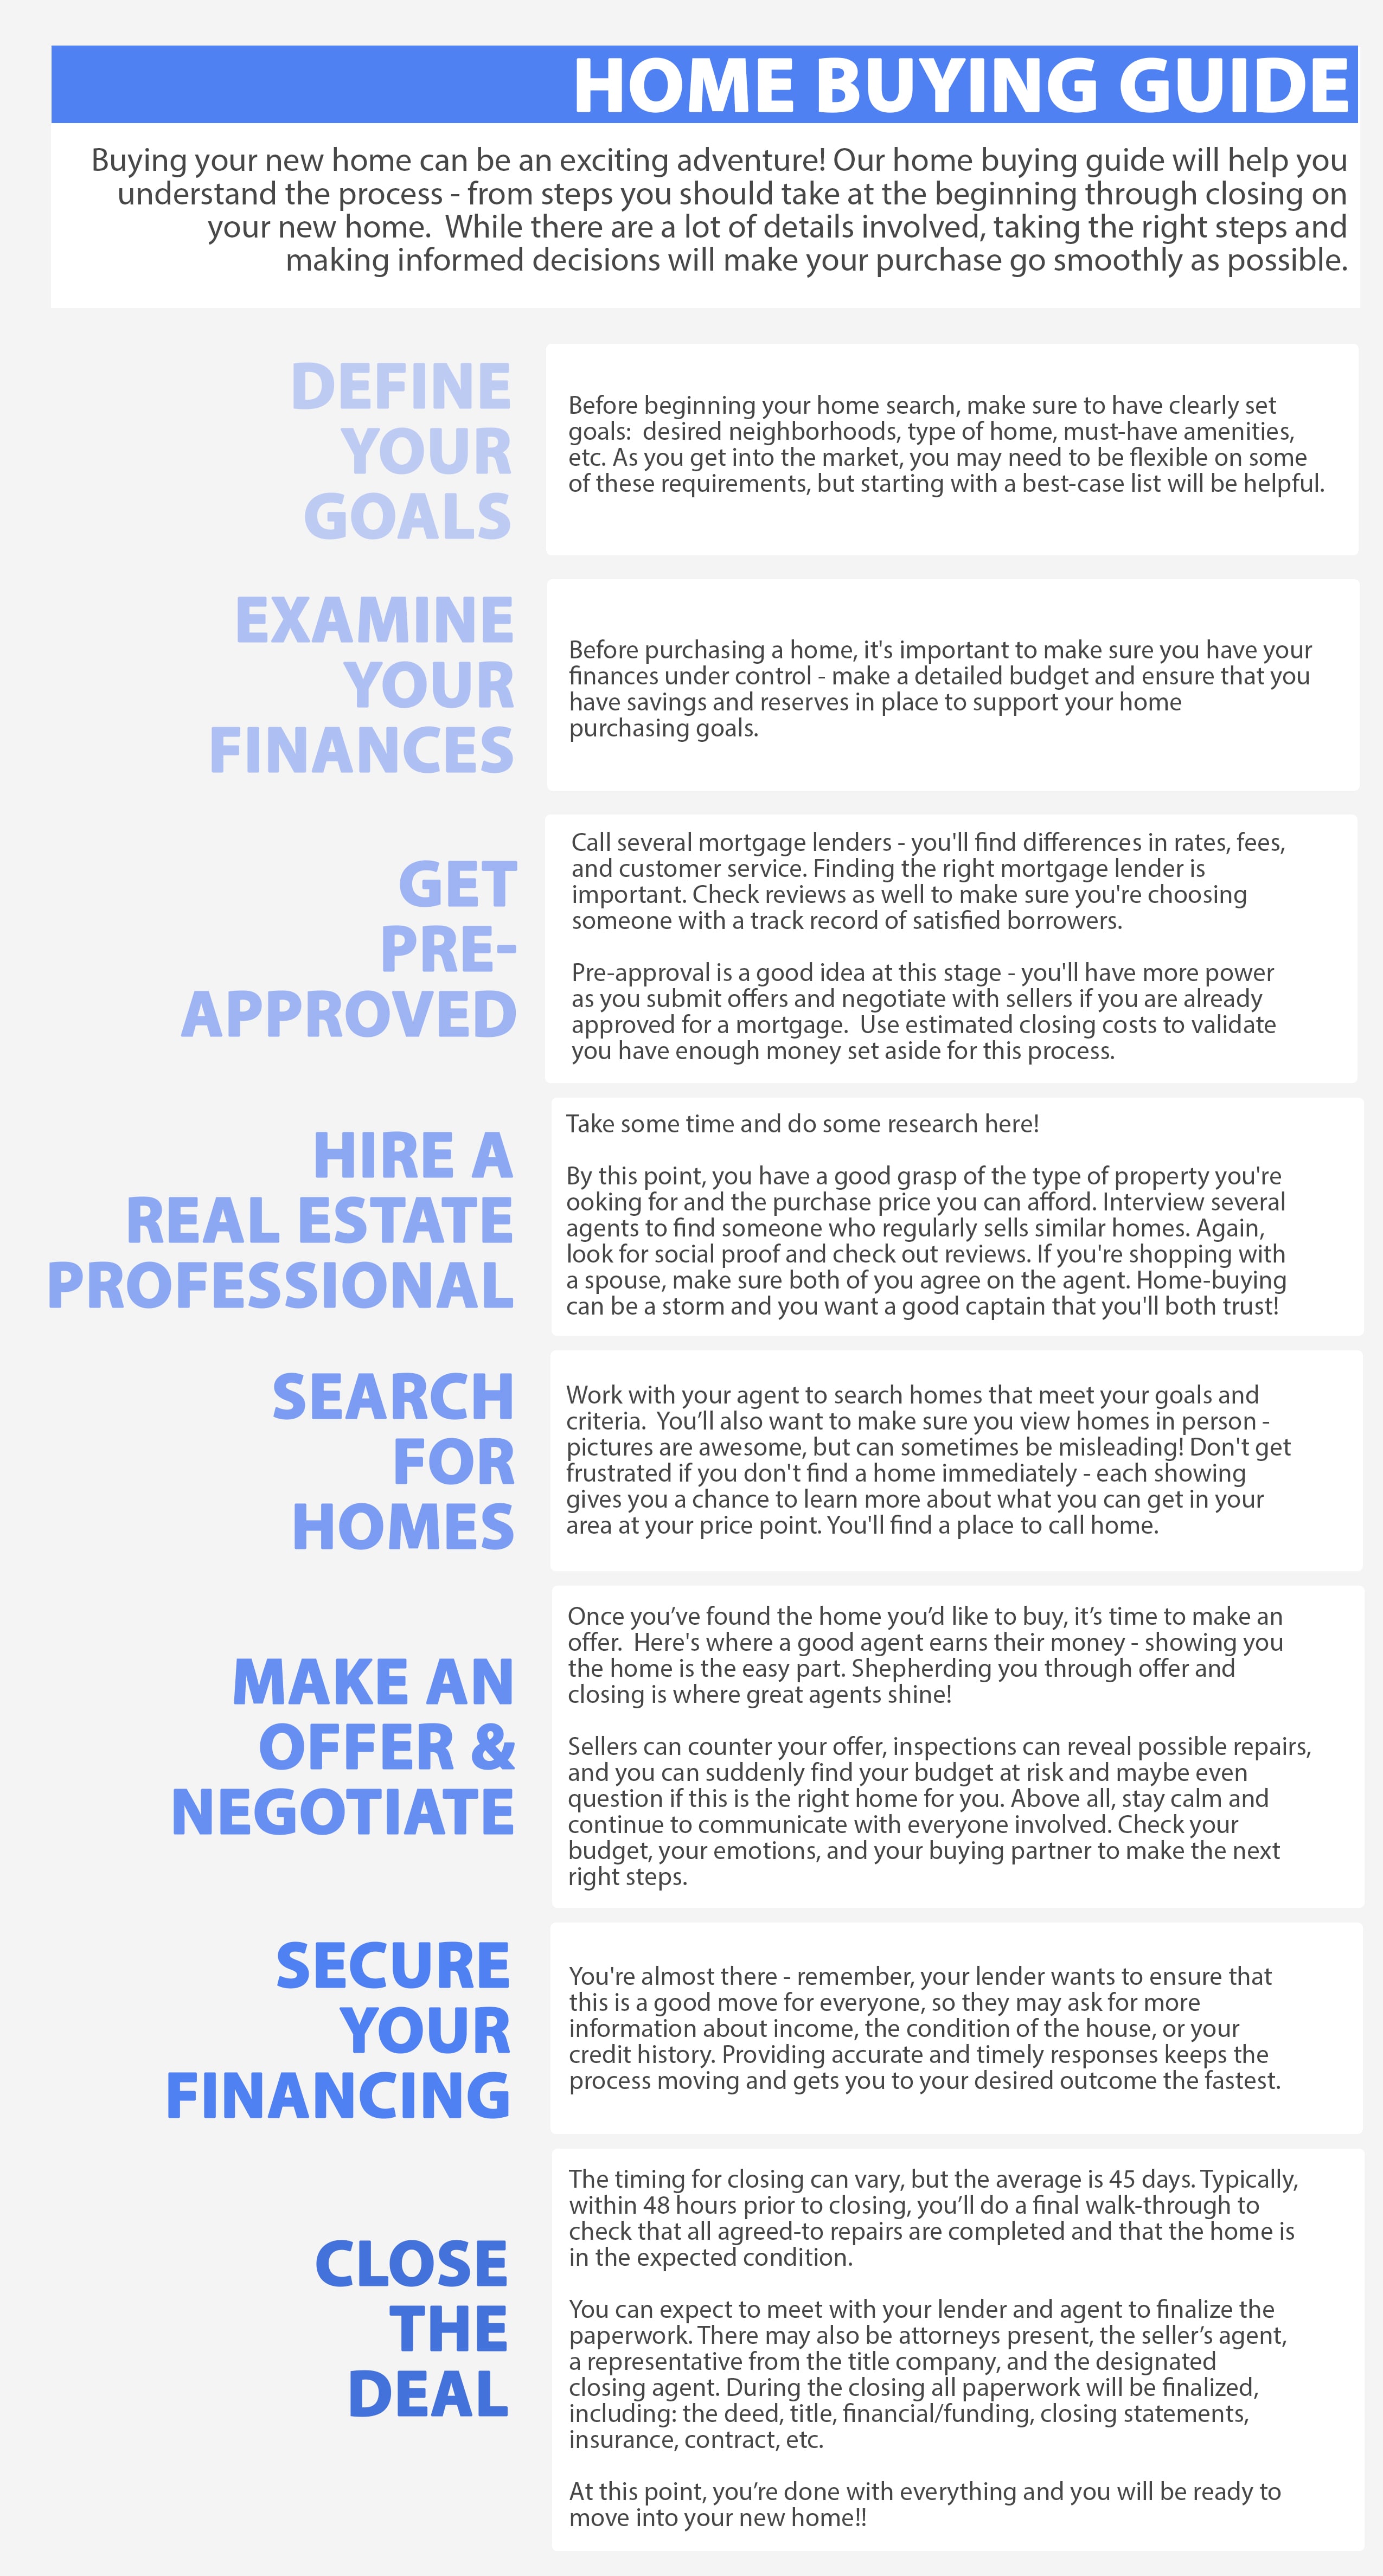
The core of buying a home without losing your mind starts before you look at a single property. You need a pre-approval letter from a lender, not a pre-qualification. Pre-qualification is a soft conversation. Pre-approval means a underwriter has reviewed your credit, income, and assets and given you a dollar amount they stand behind. Sellers take pre-approval letters seriously. They reject pre-qualification letters constantly. This distinction matters in competitive markets where multiple offers are normal. Once you have that, you pick an agent. Here's what most guides won't tell you: the best agent for your situation isn't necessarily the one with the most listings. It's the one who has closed transactions in the specific neighborhood you're targeting within the last six months. Local knowledge beats general experience every time. I once worked with a buyer who had an agent who'd been in the business for twenty years but had never closed a deal in the zip code they were looking at. That agent missed red flags on a property that a younger agent with local experience would have caught immediately. When you find a house, don't fall in love with it. That sounds harsh but it's the single most important mindset shift. You're making the largest financial decision of your life. Your emotions should not be driving that decision. The moment you attach yourself to a property, you lose negotiating leverage. Sellers can sense desperation. They'll hold out longer, ask for more, and make concessions harder to get.
The inspection phase is where most first-time buyers get hurt. I've watched people skip inspections to "move faster" or accept an agent's suggestion that "it's probably fine." One buyer I worked with in 2019 skipped the roofing inspection because the house looked new from the street. Three weeks after closing, the roof leaked during a rainstorm. The repair ran $8,400. The inspection would have cost $450 and would have identified the problem clearly. The math doesn't work the other way around. Here's a specific edge case that trips people up constantly: appraisal gaps. You offer $425,000 on a house. The appraisal comes in at $395,000. Your lender will only finance based on the appraised value, not your offer price. That means you either bring $30,000 extra to closing out of pocket, renegotiate the price down to $395,000, or walk away. I had a buyer in 2022 who had to decide this within 48 hours while also dealing with a competing offer the seller was entertaining. The workaround was simple if you know it ahead of time: negotiate an appraisal gap clause into your contract that specifies exactly what you'll do if the appraisal comes in low. That way you're not scrambling under pressure. Close-out logistics are where things fall apart for people who haven't planned ahead. You need to schedule the final walkthrough 24 hours before closing, not on the day of. You need to verify the seller hasn't moved out fixtures that were supposed to stay — chandeliers, window treatments, sometimes even the refrigerator. I've seen sellers drain hot tubs and carry them away at the last minute. The walkthrough catches that. Title work needs to clear. HOA documents need to be reviewed if there's a homeowners association. All of these things create a checklist that looks manageable until you're three days from closing and one item is stuck in limbo.
Get the Full Details
Some things about this process are genuinely harder than they should be. The system is designed so that every party involved has an incentive to slow things down or add fees. Title companies charge research fees, recording fees, settlement fees, and courier fees. Many of those fees are negotiable or waivable if you ask. Lenders charge origination fees, application fees, and processing fees that often have zero real cost behind them. I've seen buyers save $1,500 to $3,000 at closing simply by asking for a lender credit in exchange for a slightly higher interest rate. That's a real trade-off that requires you to understand the math, but it's one worth understanding. The biggest pitfall I see isn't technical. It's emotional. People buy houses they can barely afford because they're afraid of missing out. They overextend themselves, then struggle through the first year of ownership when the real costs hit — property taxes that are higher than expected, a water heater that needs replacing at month eight, landscaping they weren't prepared to maintain. The rule of thumb most advisors give is the 28 percent rule: your housing payment should not exceed 28 percent of your gross monthly income. The smarter rule is 25 percent. Leave room for the things that go wrong. There's also a common misconception that you need 20 percent down. That's not true for most loan types. Conventional loans start at 3 percent down. FHA loans at 3.5 percent. VA and USDA loans at zero percent. The trade-off is typically private mortgage insurance or similar premiums, which add to your monthly cost but don't require a large cash outlay upfront. If you have family who can gift you the down payment, most lenders will accept that as long as it's properly documented with a gift letter. Don't assume you can't qualify because you don't have a massive savings account.
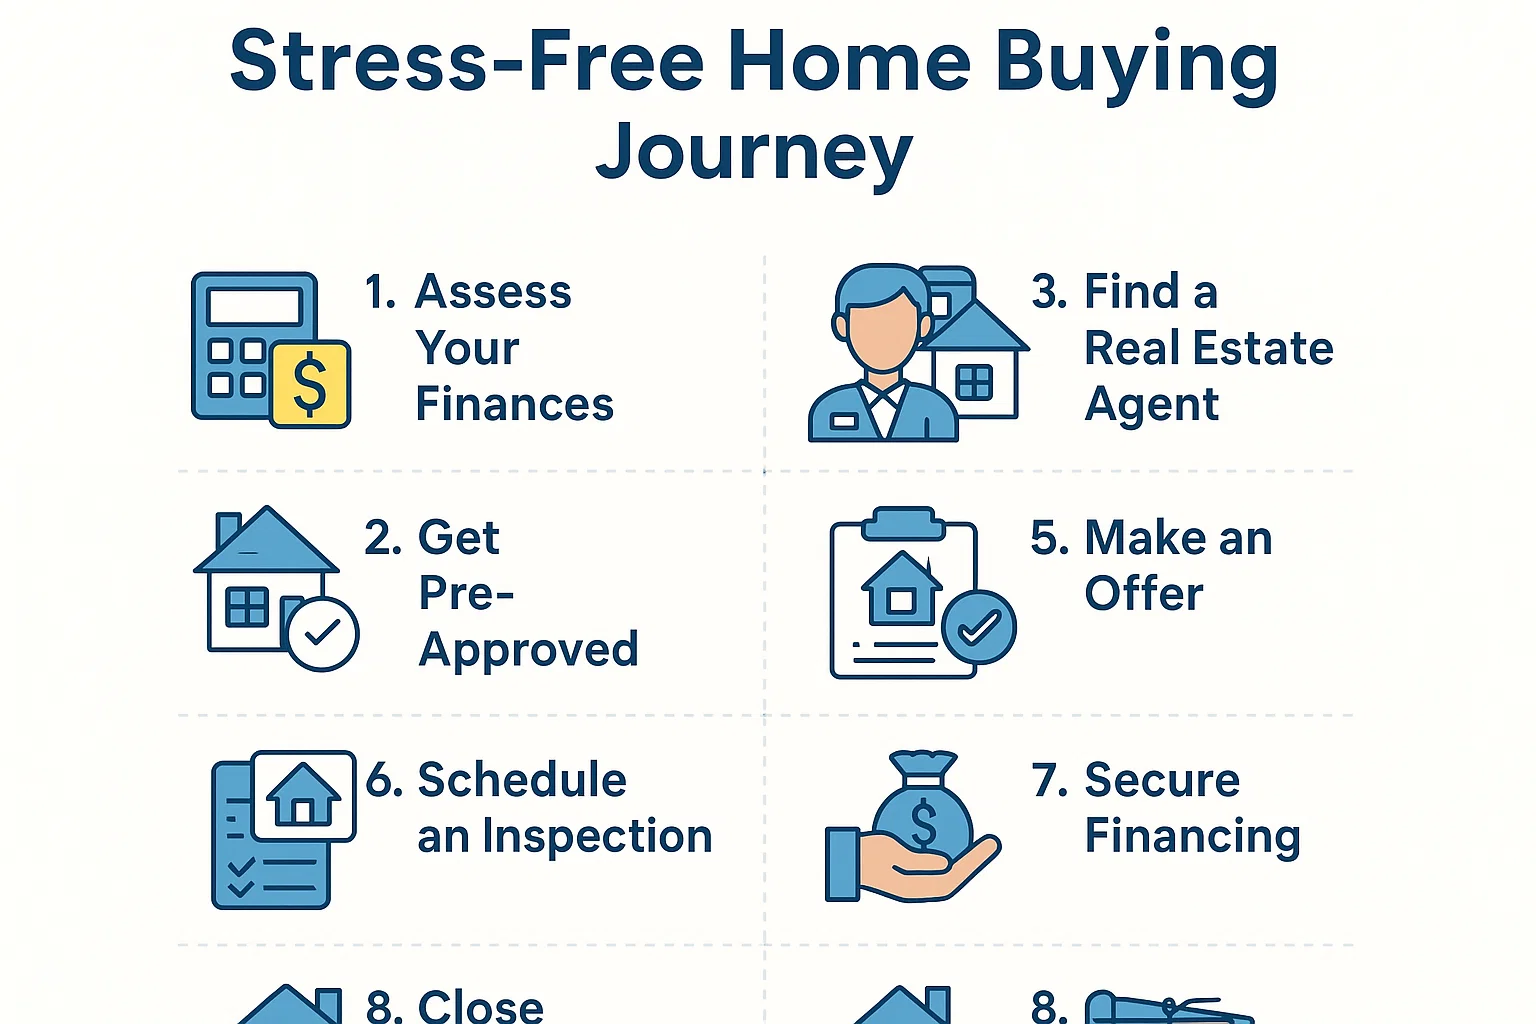
When you're ready to start, the first practical step is pulling your credit report. Not just checking your score — pulling the full report from annualcreditreport.com. Review it line by line for errors. I've seen buyers denied or pushed into higher rates because of incorrect late payments or accounts that weren't theirs. Disputing errors takes time, sometimes weeks, so do it before you start house hunting. A thirty-point score difference can change your interest rate by half a point or more, which translates to hundreds of dollars per month over the life of the loan. The second step is getting pre-approved, not pre-qualified. Bring your W-2s, your most recent pay stubs, your bank statements, and your tax returns if you've changed jobs in the last two years. The lender will pull your credit and run the numbers. If something comes up — a large deposit you can't explain, a job gap, a debt you forgot about — you'll know before you make an offer instead of after. Everything after that is a series of decisions made under deadlines. Offers, inspections, negotiations, appraisals, underwriting, closing. The people who move through this smoothly are the ones who treat it like a project with milestones, not a emotional journey. That doesn't mean you shouldn't enjoy finding your house. It means you should keep your expectations in check and your wallet protected while you're doing it.
One thing the industry doesn't want you to know: you can often negotiate the agent commission. The standard 5 to 6 percent split between buyer and seller agents is not set in stone. In slower markets, especially, sellers will accept a lower commission to get their house listed and moving. I've seen listings go with a 4 percent total commission and still sell within the typical timeframe. That's thousands of dollars staying in your pocket. Ask your agent directly if there's flexibility. If they act offended, that's your answer about whether they're worth working with. Keep your documents organized from day one. Folder on your phone, folder on your computer, physical binder if you're old school. Every email from your lender, every inspection report, every disclosure, every text message from your agent that mentions a deadline — save it. Years from now, when someone asks you how you bought your house, you'll be able to show them the timeline. More importantly, if a problem surfaces later, you'll have paper trail evidence. The process is long. It's tedious. It involves more signatures than most people realize. But it's also completely repeatable and well understood by anyone who's done it before. The people who have done it before are the ones you want on your side — the ones who can tell you what will go wrong before it goes wrong, not after. That's the actual value of experience in this market. Not knowing every house on the block. Knowing where the paperwork breaks down and how to prevent it from breaking you.