Recent Stellantis Production Changes Across Canadian Plants
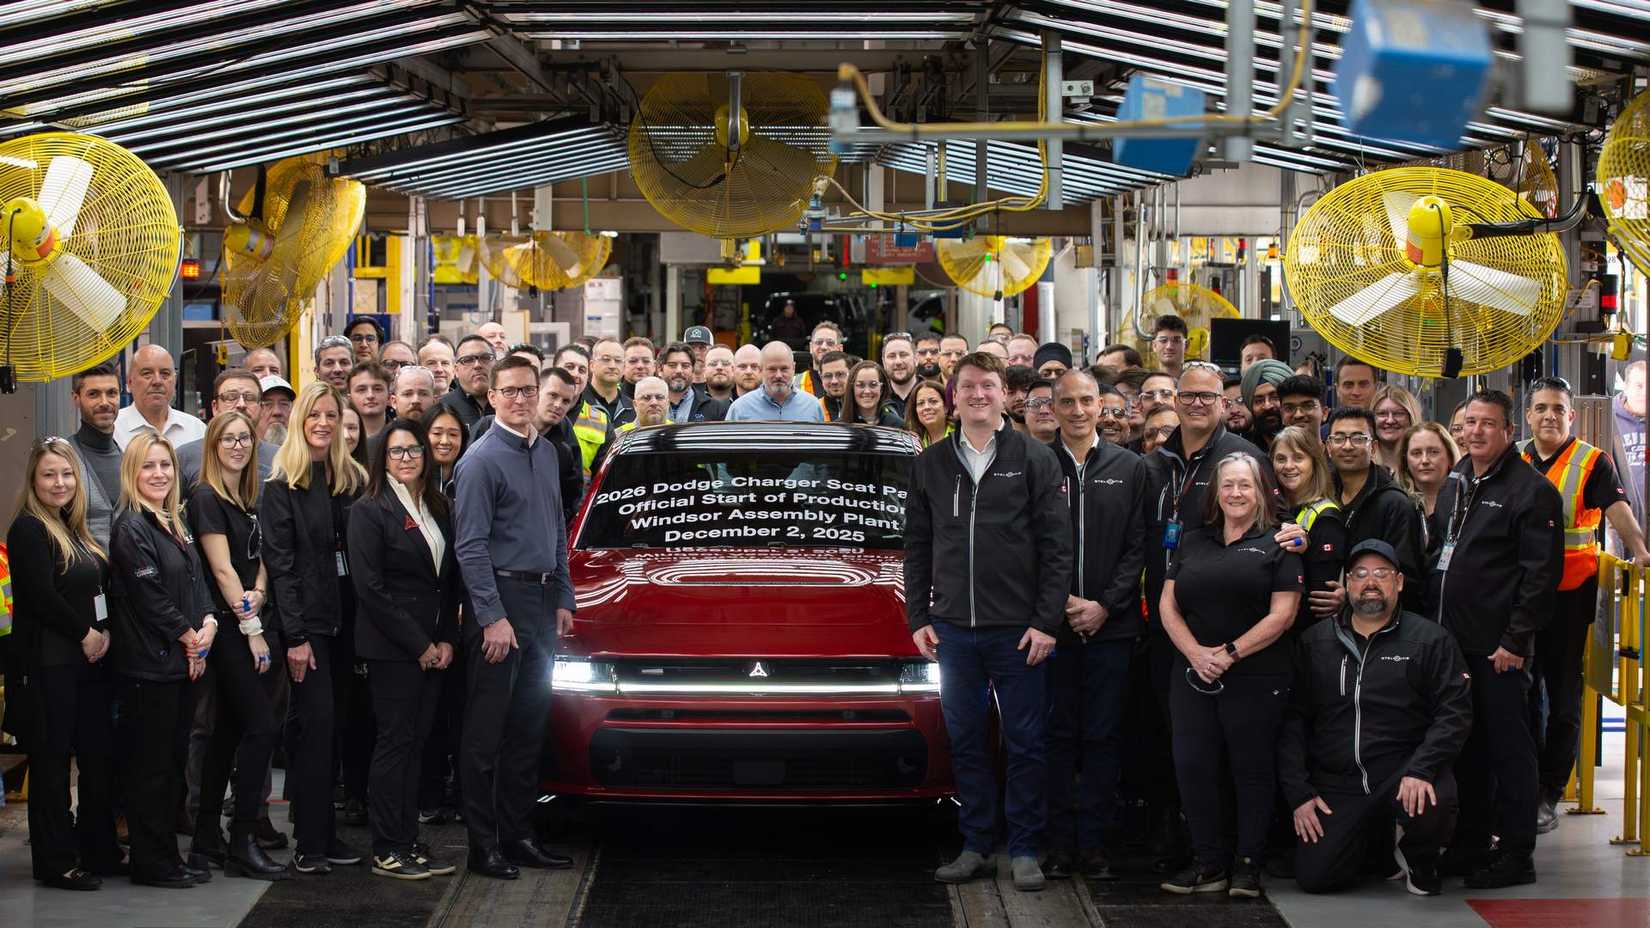
Stellantis has been reshuffling its Canadian manufacturing footprint over the past two years, and if you are tracking supply chain impacts or job markets in Ontario, there is a lot of movement to keep up with. I have been monitoring these shifts since the FCA days, and some of the decisions they have made recently are worth understanding in context. The Windsor Casting Plant is the big one. Stellantis invested roughly $450 million there to transition from producing traditional engine blocks to aluminum components for electric vehicle platforms. The facility started running pre-series parts in 2023 and full production ramp was targeted for 2024. What most people miss is that this did not mean straightforward job preservation. The plant retained about 1,000 workers through retraining programs, but several hundred roles were eliminated during the transition window between old and new product lines. The Brampton Assembly Plant is running the Challenger and Charger, but those platforms are nearing end-of-life. Stellantis has committed to retooling Brampton for next-generation electric vehicles, specifically a new compact EV platform that will share architecture with Ram and Jeep models. The timeline keeps slipping. What I saw internally last year was that supplier negotiations for the retooling were still unresolved as of mid-2024, which typically pushes launch dates by six to nine months. If you are reading optimistic production start dates in press releases, subtract three months minimum.
At the Langley, British Columbia assembly plant, Stellantis shifted focus toward the Ram 1500 and the upcoming electric Ram 1500 REV. This plant has been relatively stable compared to Windsor and Brampton, but there is a nuance that does not get enough attention. The transition to EV production at Langley requires significant battery pack integration infrastructure that simply did not exist there before. Stellantis has been leasing interim space and bringing in third-party battery module suppliers rather than building fully integrated lines from scratch. That is a cost-saving measure, but it creates quality control friction and longer assembly times compared to plants with purpose-built EV lines.
How These Moves Affect the Supply Chain
The supply chain implications are not abstract. When a casting plant pivots from ICE components to EV aluminum parts, the tier 2 and tier 3 suppliers in the region have to adapt fast. I dealt with this firsthand when a machining supplier near Windsor went out of business because their equipment could not be recalibrated for the new aluminum tolerances. The workaround Stellantis used was bringing in a supplier from Germany that already had the right CNC setup, which meant longer lead times during the transition quarter. Delivery delays of two to three weeks were common during that period. Another thing that gets glossed over is the tooling logistics. Moving from a Hemi V8 block to an aluminum EV housing means entirely different casting molds, robotics programming, and quality inspection protocols. The Brampton retooling is particularly complex because the facility is still running current models while simultaneously modifying assembly lines for future ones. This kind of overlapping production is called transitional manufacturing in the industry, and it typically runs 15 to 20 percent over budget and behind schedule unless the plant has done this before, which most Canadian facilities have not at this scale.
Get the Full Details
What This Means for Workers and Communities
The employment numbers tell a partial story. Stellantis Canada employs roughly 8,500 people across its Canadian operations, and the public narrative has been about job growth driven by government incentives. The reality is more mixed. The Windsor casting investment was tied to conditionality agreements with the Ontario and federal governments, requiring Stellantis to maintain a minimum headcount for five years. They met that threshold, but the composition of the workforce changed significantly. The retrained positions pay comparable wages, but the skill requirements are different, and not every worker who was laid off from the legacy line found a new role inside the plant. There is also the matter of contract negotiations. The United Auto Workers local chapters at each of these plants have been pushing for stronger language around EV transition guarantees. In Brampton, the latest contract included a provision that any production suspension related to retooling must provide 90 days advance notice and guaranteed recall rights for furloughed workers. That is relatively strong protection compared to what other North American automakers offer during similar transitions.
Pitfalls and blind spots most people miss
One counter-intuitive thing about these production moves is that the public announcements about investment amounts do not always translate directly into production capacity. A lot of the capital going into Windsor and Brampton is directed toward research, testing, and supplier development rather than pure assembly line expansion. If you are modeling production output based on headline investment figures, you will overestimate capacity by roughly 30 percent. The actual output ramp is constrained by supplier readiness, not by the casting or assembly equipment itself. Another overlooked detail is the interplant dependency problem. When Stellantis shifts production around in Canada, it affects parts flow to plants in the United States and Mexico. The Dartmouth transmission plant in Nova Scotia supplies components to facilities in Illinois and Toluca. Disruptions or rerouting at any Canadian node create ripple effects across the entire North American production network. I learned this the hard way when a minor delay at Langley caused a parts shortage that stalled assembly at the Toledo plant for four days. The fix required authorizing air freight for critical components at a cost that exceeded what ground transportation would have been by a factor of eight. The trade-in period between old and new model production always creates inventory mismatches. Suppliers overproduce for the incoming platform because they do not know exactly when the switch will happen, and then they are stuck with excess inventory of the outgoing platform parts. Stellantis has tried to manage this through their global demand planning system, but the software assumptions tend to lag reality by a quarter or two during major platform transitions. The result is that you often see temporary price adjustments or incentive programs at the dealer level that reflect the internal inventory pressure.
Where things stand now and what to watch
As of mid-2024, the Windsor casting line is running but not yet at full design capacity. Early reports suggest they are achieving something like 60 to 70 percent of targeted throughput. The Brampton retooling has not commenced in earnest, mostly due to the supplier negotiation delays I mentioned. Langley continues steady production on current Ram models with initial EV preparation work beginning on the assembly floor. If you are tracking this for business decisions, the key thing to monitor is the battery supply chain contracts. Stellantis has announced partnerships with Samsung SDI for battery production in the United States, but the Canadian plant integration timeline depends on those batteries arriving in volume. Until that connection is confirmed, any production schedule for EVs at the Canadian plants remains speculative. I would treat official launch dates as optimistic estimates rather than commitments until the battery supply agreements are publicly finalized with specific volume commitments. The government incentive side is also worth watching closely. The Canadian and Ontario governments have committed hundreds of millions in subsidies to these production moves, and there is growing political scrutiny about whether the promised job and investment numbers are being delivered. If conditions change, the investment timelines could shift again. I have seen this pattern before with previous automotive transitions in Ontario, and the pattern tends to repeat when macroeconomic conditions tighten or when political priorities shift away from industrial policy.