Understanding What Your Illinois Paycheck Actually Looks Like in 2024
Most people in Illinois have no idea how much of their salary disappears before it hits their bank account. I ran payroll for a mid-size firm for nearly a decade, and I still get questions from employees who are genuinely shocked when they see the net difference between their gross and their take-home. The state has its own quirks that trip people up every single year.State Illinois Salary Breakdown 2024 Compensation Trends Taxes And Purchasing Power
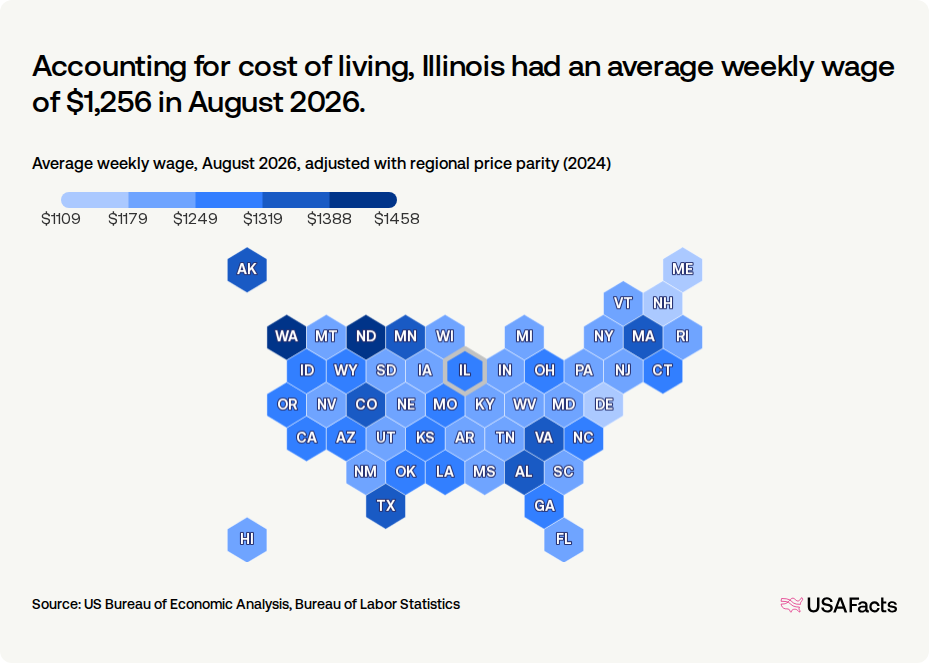
The Illinois income tax rate is flat at 4.95% across the board. That means a $60,000 salary and a $200,000 salary are taxed at the same percentage on the state side. Federal withholding sits in progressive brackets, of course, which is where the real variation comes in. If you are making $75,000 annually and filing single, you can expect roughly $3,712 in federal income tax, $4,587 in Illinois state tax, $4,650 in Social Security and Medicare combined, and another $275 or so toward unemployment insurance depending on your employer's rate. That leaves you with approximately $58,776 in annual gross pay going to about $48,500 after those standard deductions. Your actual number will shift based on pre-tax contributions like a 401(k) or HSA. Compensation trends in 2024 tell a slightly different story than the tax numbers. The Bureau of Labor Statistics data for Illinois shows average annual wages sitting around $68,420, up roughly 4.2% from the prior year. Chicago metro areas run higher at about $74,800 on average, while downstate positions cluster closer to $59,000 to $62,000 depending on industry. Tech and healthcare continue to push median salaries upward, while manufacturing and retail lag behind inflation. The gap between what employers offer and what employees actually receive in purchasing power is the part most people overlook. Purchasing power in Illinois varies wildly by region, and that matters more than any tax calculation. A $65,000 salary in Springfield goes substantially further than the same salary in Chicago. The Midwest Census Bureau's cost-of-living index puts Chicago at about 118% of the national average, meaning you need roughly $11,800 more in income just to maintain the same standard of living someone enjoys in a city like Peoria or Champaign. Springfield sits closer to 91% of the national average. Downstate regions like Rockford and Decatur fall in the low 90s. This is not theoretical. I watched a former colleague move from a $82,000 job in Oak Brook to a $71,000 role in Bloomington and end up financially better off because his rent dropped from $2,100 a month to $1,100 and his commute cost halved. The raw salary number looked worse. His actual disposable income improved by roughly $14,000 annually.
There are a few specific tax nuances that catch people off guard in Illinois. First, the state does not allow a standard deduction on your Illinois return in the same way the IRS does. You claim either the federal standard deduction or itemize, but Illinois only lets you subtract a portion of your federal standard deduction if you are not itemizing. For a single filer in 2024, the Illinois standard deduction is roughly $2,450, which is significantly lower than the federal amount of $14,600. This means your Illinois taxable income is almost always higher than your federal taxable income, even if everything else is identical. Second, property taxes in Illinois are among the highest in the nation and they do not show up on your W-2 at all. A homeowner in Cook County paying $8,000 annually in property taxes is effectively losing another $667 per month that never appears in any salary breakdown. That number can easily double in suburban communities with older tax bases. When someone tells me their salary feels insufficient, I usually ask about their property tax bill before I say anything else about their income tax bracket. Here is a practical example that actually happened. A client came to me in early 2024 with two offers. Offer A was $78,000 in downtown Chicago with a company-paid transit pass worth about $2,400 annually. Offer B was $72,000 in Naperville with no commute benefit but a smaller expected property tax exposure since she did not own a home yet. Her first instinct was to pick Offer A because the number was higher. I ran both through a full breakdown including estimated housing costs, transit versus car expenses, state and federal taxes, and her employer's 401(k) match structure. Offer B actually left her about $3,200 more in discretionary income after accounting for everything. The Chicago salary looked better on paper but the cost of living ate the difference and then some. She took the Naperville offer and had no regrets six months later. The 2024 compensation picture for Illinois also includes changes to retirement contribution limits. The 401(k) elective deferral limit rose to $23,000, up from $22,500. Catch-up contributions for those over 50 stayed at $7,500. Health savings account limits moved to $4,150 for self-only coverage and $8,300 for family coverage. These pre-tax contributions reduce your federal taxable income dollar for dollar and your Illinois taxable income as well, which makes them doubly valuable in a flat-tax state. If you are not maximizing your 401(k) contribution, you are leaving money on the table every single payday. I have seen this play out repeatedly with employees who hesitate at the monthly reduction in their take-home pay only to realize at tax time that they overpaid by several thousand dollars in combined federal and state taxes.
Federal tax changes in 2024 also matter. The standard deduction increased to $14,600 for single filers and $29,200 for married couples filing jointly. Tax brackets stayed mostly the same with slight inflation adjustments. The childcare tax credit remains expanded through 2025 under current law, which affects families significantly. If you qualify, the maximum credit for one child is $3,600 and for two or more children it is $3,000 per child, though the actual amount phases out at higher income levels. This credit is refundable, meaning you can receive it even if you owe no federal tax. Several of my clients in the Chicago area used this to offset a significant portion of their annual childcare expenses without having to make any special elections or paperwork beyond their standard tax return. Self-employed individuals in Illinois face a different set of calculations entirely. There is no employer to split the FICA tax with, so you pay the full 15.3% yourself, though you can deduct the employer-equivalent portion on your federal return. The self-employment tax savings from deducting half of that FICA obligation typically reduce your effective self-employment tax rate to about 14.13% rather than a blunt 15.3%. On the Illinois side, self-employed income is subject to the same 4.95% flat rate. Net profit from a side business or freelance work gets folded into your overall state tax calculation. Estimated quarterly payments are required once you expect to owe $1,000 or more in tax for the year. I have watched too many people skip the quarterly schedule and then get hit with underpayment penalties that total several hundred dollars. Setting up a simple calendar reminder for the 15th of April, June, September, and January avoids this entirely. If you want to model your own numbers without relying on a generic online calculator, here is the method I use. Start with your gross annual salary. Subtract any pre-tax deductions like 401(k) contributions, health insurance premiums paid through payroll, and HSA or FSA amounts. The result is your federal taxable wage base before the standard or itemized deduction. Apply the 2024 federal tax brackets to that number. Then take your gross salary again and subtract the Illinois standard deduction of approximately $2,450 for a single filer. Apply the flat 4.95% rate to that figure. Add back your Social Security tax at 6.2% on earnings up to the $168,600 wage base and Medicare tax at 1.45% with no cap. That gives you a reasonably accurate estimate of your total annual tax liability. Divide by 26 for biweekly pay or 2,080 for hourly equivalent to see what each check should reflect. The numbers will not be exact because of variations in local municipality taxes in some Chicago-area suburbs and employer-specific wage base differences, but they will be close enough to catch any major discrepancies on your pay stub.
Get the Full Details
The biggest mistake I see people make is comparing salaries across Illinois regions without adjusting for cost of living. A $90,000 salary in Chicago might provide less actual purchasing power than a $78,000 salary in Aurora or Joliet when you factor in housing, transportation, and local tax exposure. Run the numbers yourself before turning down an offer just because the headline number is lower. Conversely, do not accept a Chicago salary simply because it looks impressive on paper. The city adds a 2.4% local income tax on top of everything else if you work within city limits, which is another layer most people forget until they see it on their first paycheck. That municipal tax alone costs roughly $2,160 annually on a $90,000 salary and it does not apply to suburban or downstate employers. Always check whether your job address falls within the Chicago city boundaries before you sign anything. The difference is not trivial. For anyone looking to dig deeper into official data, the Illinois Department of Revenue publishes annual tax rate tables and deduction amounts at illinois.gov/revenue. The Bureau of Labor Statistics maintains regional wage data at bls.gov, and the Federal Reserve Bank of Chicago produces quarterly household debt and cost-of-living reports that are useful for longer-term planning. None of these sources give you a personalized breakdown, but they provide the baseline figures that all legitimate calculators depend on. I prefer to pull the most recent year's data directly from those sites rather than trusting third-party articles that may be using outdated rates. Tax law changes frequently enough that a guide written in early 2023 may already be wrong by mid-2024. The bottom line is that Illinois compensation in 2024 requires attention to three separate layers: federal withholding, state flat tax, and local municipal tax if applicable, plus the invisible drag of property taxes and regional cost of living. Most people focus only on the first two and ignore the rest. If you want to actually understand your purchasing power, you have to account for all of them together. A detailed spreadsheet that tracks every deduction and cost factor will give you a far more accurate picture than any single salary number ever will.