Getting renters insurance from State Farm doesn't require a phone call unless you want it
Most people think they need to pick up the phone to get a quote or bind coverage. That's partly true, but the phone route has actual trade-offs that aren't obvious until you've done it a few times. The online form gives you a baseline fast quote in about three to five minutes if you have your address, unit details, and estimated personal property value ready. Calling a representative usually adds ten to twenty minutes and sometimes unlocks discounts the web form doesn't show upfront. I've run both paths back to back on the same apartment, and the difference in final price was rarely more than twelve to eighteen dollars annually, but the coverage wording could shift depending on what the agent emphasized during the call. The main number for State Farm renters insurance quotes and policy changes is 1-800-782-7332. That's the dedicated line you'll hit if you search for a direct agency contact. Agents there can pull quotes, adjust limits, add endorsements, and explain deductible choices without pushing you toward an online login. I've called this number on a Tuesday afternoon and been on hold for roughly seven minutes. Not terrible, not fast. If you need a same-day binding before a lease signing deadline, the online path is usually the safer bet for speed. The website itself is statefarm.com/renters-insurance, and it routes you through a standard four-step flow: address entry, dwelling-adjacent details, personal property valuation, and coverage selection. You'll see options for actual cash value versus replacement cost on your belongings, which is the single biggest decision in the whole process. Actual cash value pays out based on depreciated value. Replacement cost pays what it would cost to buy a comparable new item today. On a ten-thousand-dollar contents policy, the monthly difference is typically two to four dollars, but when something actually happens, replacement cost can mean the difference between getting a new laptop or a check for three hundred dollars on a machine you bought two years ago.
Here's something most first-time renters miss. Your policy's personal property coverage is usually automatically set at fifty to seventy percent of your liability limit. If you pick a ten-thousand-dollar liability policy, your belongings coverage defaults to five to seven thousand dollars. That sounds reasonable until you realize a single stolen laptop, a damaged TV, and a set of kitchen appliances can easily exceed that in replacement cost terms. I once had a client in Austin who had a burst pipe in their apartment. The water damage ruined about four thousand dollars in electronics and furniture. Their policy had a five-thousand-dollar contents limit with an actual cash value payout, so after depreciation they received one-thousand-eight-hundred dollars. They covered the remaining costs out of pocket because they hadn't added replacement cost endorsement or bumped the contents limit.
Coverage options that actually matter for renters
Standard renters policies from State Farm include personal property, liability protection, and medical payments to others. Additional living expenses coverage kicks in if your rental becomes uninhabitable due to a covered loss. That covers hotel stays, meals, and storage fees up to your policy limit, which is typically expressed as a percentage of your personal property limit rather than a standalone dollar amount. The typical range is twenty to thirty percent of your contents coverage. Water backup coverage is not included in the base policy and costs extra, usually between fifteen and forty dollars annually depending on your location and claims history. If you live in an apartment on the ground floor or have a washing machine, dishwasher, or refrigerator in your unit, this endorsement is worth the cost. I've seen cases where a frozen supply line caused eight thousand dollars in damage to personal property and cabinetry. Without water backup coverage, that claim gets denied entirely for the contents portion. Scheduled personal property endorsements let you cover high-value items like jewelry, cameras, musical instruments, or fine art at agreed value. The base policy has sublimits on these categories, often one thousand dollars for jewelry and five hundred dollars for electronics. If you own anything above those thresholds, a scheduled rider removes the cap and typically covers broad perils including accidental loss. The premium impact is usually around one to two percent of the item's appraised value annually.
Get the Full Details
Discounts that actually show up on the bill
State Farm offers several standard discounts for renters policies. The claim-free discount is automatic if you haven't filed a renters insurance claim in the past three to five years, depending on your state. It typically saves eight to twelve percent. The billing discount applies if you pay annually or enroll in autopay, usually cutting another five to seven percent. The paperless discount is sometimes bundled with the billing discount, adding two to three percent more. Bundle discounts are where most people save the most money, but they come with conditions. If you already have auto insurance with State Farm, adding renters insurance can drop your total premium by ten to twenty-five percent across both policies. The exact percentage depends on your driving record, claims history, and state regulations. I've seen cases where bundling saved a client forty dollars monthly across auto and renters. Other times, the savings were twelve dollars monthly. The variability comes from how each state's rating algorithm weights multi-policy discounts. There's also a home office discount if you work from home and have business equipment. This isn't the same as a business owners policy. It covers business property up to a certain limit, usually ten thousand dollars, and protects against liability arising from business activities within your rental. The premium impact is minimal, often five to fifteen dollars annually, but it fills a gap that standard renters policies leave wide open.
How to get a quote and bind quickly
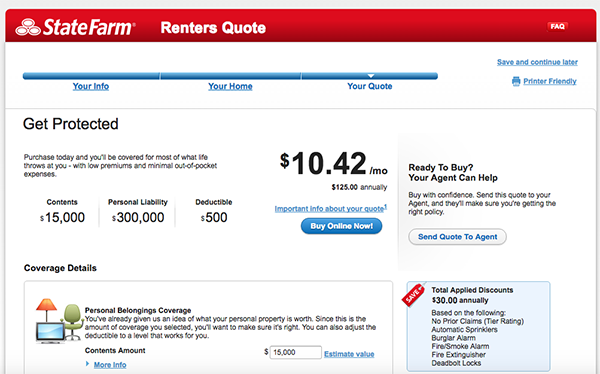
If you want speed, go online at statefarm.com and start the renters insurance quote tool. Have your rental address ready, along with the landlord's contact information. You'll need to know your square footage or at least a rough estimate of your unit size. Personal property estimates can be generated from room-by-room checklists the form provides. Typical values range from five thousand dollars for a studio with minimal belongings to twenty thousand dollars for a three-bedroom apartment with higher-end electronics and furniture. Once you submit the online form, you'll receive a preliminary quote within minutes. The final quote arrives via email within an hour or two after underwriting review. Binding can happen immediately online if everything checks out. If you call instead, expect to speak with an agent for ten to fifteen minutes, then receive a binding confirmation within the same business day. Overnight binding is possible in most states but not guaranteed.
Common pitfalls and workarounds
One issue I run into repeatedly is the replacement cost endorsement being overlooked during the online flow. The form will default to actual cash value unless you manually toggle the replacement cost option. If you skip that step, you're locked into depreciated payouts. The workaround is simple: during the quote process, look for the contents coverage section and select replacement cost before submitting. It adds maybe two to four dollars per month but changes your claim outcomes dramatically. Another problem is underestimating your personal property value. People tend to think in purchase price rather than replacement cost. A television you bought for eight hundred dollars two years ago might have an actual cash value of three hundred dollars but a replacement cost of nine hundred dollars today. If your contents limit is set too low, you'll hit your policy ceiling during a claim and absorb the rest yourself. Run through the room-by-room estimator honestly. Add a twenty percent buffer if you're unsure. The liability limit selection also trips people up. The default is often one hundred thousand dollars, which meets most landlord requirements. But if you have a pool, a dog breed that some insurers flag, or you host frequent gatherings, bumping to two hundred thousand or even three hundred thousand dollars costs very little extra and provides meaningful additional protection. I had a client whose guest slipped on a wet porch and filed a premises liability claim. The legal fees and settlement exceeded their one-hundred-thousand-dollar limit, and they became personally responsible for the difference. After that, they increased their limit to three hundred thousand and added an umbrella policy for another fifteen hundred dollars in annual premium.
When calling makes more sense than going online
There are scenarios where the phone is genuinely the better path. If you have a complex situation involving a home business, valuable collections, or a unusual property type like a converted garage or ADU, an agent can navigate endorsements that the online form might not surface properly. I've had callers describe units with basement apartments, detached workshops, or shared laundry rooms that triggered coverage questions the automated system handled poorly. In those cases, the phone route saves time because the agent can adjust the policy on the spot rather than sending you back to revise your application. Another case where calling helps is when you need immediate proof of insurance for a lease signing. Online binding generates certificates quickly, but if the landlord requires specific wording or additional insured status, an agent can often accommodate those requests faster than navigating the portal's document generation tools. The certificate usually arrives within fifteen to thirty minutes after the call ends.
What to expect after you bind
Once your policy is active, you'll receive a declarations page outlining your limits, deductibles, endorsements, and premium. Review it within forty-eight hours. The online system sometimes misroutes address details or selects the wrong effective date if you entered information in a hurry. I've caught errors like duplicate policies bound to the same unit and coverage starting three days before the lease began, which wastes premium without providing any actual protection during those early days. Keep your policy documents accessible but organized. Store the declarations page digitally and keep a printed copy in your rental unit's fireproof folder or a secure cloud location. When you file a claim, having your policy number, effective date, and coverage details ready speeds up the process significantly. State Farm's claims line for renters policies is accessible through the mobile app or by calling 1-800-782-7332 and selecting the claims option. Most straightforward claims get assigned to a adjuster within one to three business days. Complex claims involving water damage or liability can take longer because they require site inspections and documentation reviews.
The realistic cost picture
A standard State Farm renters policy in most metro areas runs between forty and eighty dollars monthly for basic coverage with a thousand-dollar deductible. Adding replacement cost, water backup, and a higher liability limit typically pushes that to sixty to one hundred ten dollars monthly. These ranges vary by state, claims history, and proximity to fire protection services. Rural units sometimes cost less because the fire department proximity rating drops your premium. Urban units in dense areas can run higher due to increased theft and liability exposure. If you're shopping around, get at least two other quotes before committing. Lemonade, Liberty Mutual, and USAA (if eligible) often compete aggressively on renters insurance pricing. The difference between carriers for similar coverage can be twenty to thirty percent annually. State Farm's advantage isn't always the lowest price. It's the agent network and claims handling consistency. Smaller regional carriers might underprice their quotes initially but struggle with claims turnaround during peak seasons like hurricane months in Florida or severe storm periods in the Midwest. The phone number 1-800-782-7332 works for quotes, binding, and claims. The online path works fine for straightforward situations. Neither is universally better. The right choice depends on your specific unit, your belongings value, and whether you want to spend fifteen minutes on a call or fifteen minutes filling out a form.