What Renters Insurance Actually Covers In Manhattan
Living in a one-bedroom near Upper West Side doesn't mean your stuff is protected just because you pay rent. Most people I talk to think their landlord's policy covers their laptop, clothes, or kitchen appliances. It doesn't. Landlord insurance only protects the building structure, not anything you own. When I had a pipe burst in my apartment back in 2019, I learned this the hard way after my water-damaged records and books weren't touched by the property manager's claim. State Farm Renters Insurance NYC Protecting Your Apartment In The Most Expensive City In The Us is something people shop for differently here than in suburbs. You're paying top dollar for square footage, but your possessions might be worth more than you realize when you actually inventory everything. A decent camera setup, designer clothes, or even furniture from IKEA can add up fast in a city where replacement costs run higher than anywhere else in America.
How The Claim Process Actually Works Here
The digital claims portal is faster than calling an agent, but there are still gotchas. Upload photos within 48 hours if possible. Most policies have a 60-day window, but delay creates friction. When I filed after the burst pipe, the adjuster asked for original purchase receipts I couldn't produce for items bought three years prior. State Farm used actual cash value instead of replacement cost because I hadn't selected the endorsement. That cut my payout by roughly 40 percent on electronics. Add the replacement cost endorsement before you need it. It typically runs $25 to $50 annually on a standard policy, but that difference matters when your TV gets stolen or your apartment floods. Without it, insurers depreciate everything based on age and condition. A five-year-old laptop might yield $200 instead of the $800 you'd pay to replace it today. In Manhattan where rental units are tight and temporary housing costs spike, that gap can determine whether you sleep on a friend's couch or book a hotel.
What Your Policy Actually Excludes
Standard renters policies don't cover floods, earthquakes, or high-value items without special riders. Manhattan basement apartments face flooding risk during Nor'easters, but that's explicitly excluded from base policies. If you live below street level and the sewer backs up, you're responsible for cleanup and replacement unless you added flood coverage through the National Flood Insurance Program or a private carrier. Jewelry, art, and collectibles have sub-limits usually capped at $1,500 to $2,500 per category. A $3,000 watch stolen from your bag qualifies as a personal possession claim, but you'd only recover the policy maximum. Schedule individual items with an endorsement if you own pieces worth more than the blanket limit. The underwriting process requires appraisals for items over $5,000, which adds time but prevents disputes later.
Pricing Realities In New York City
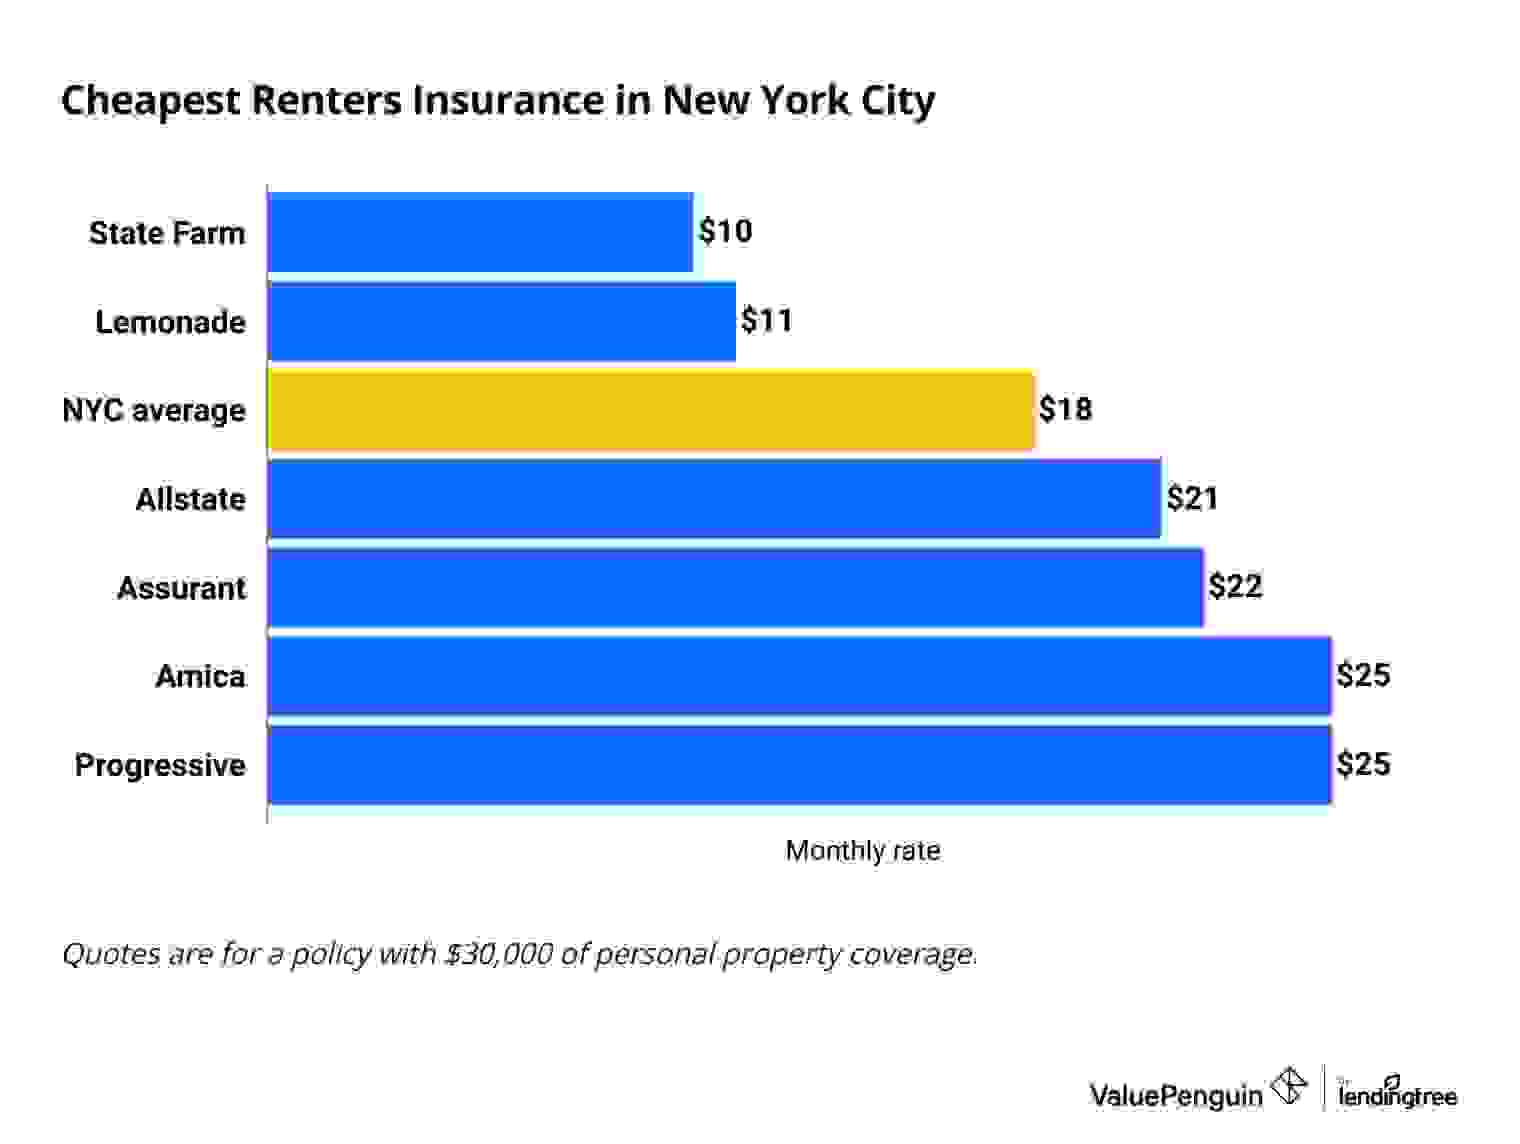
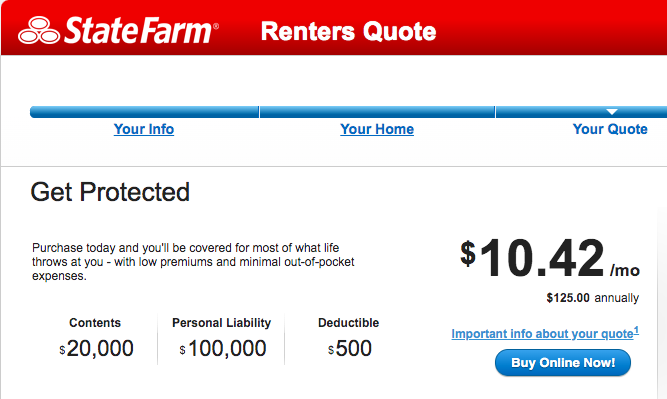
Expect to pay $15 to $30 monthly for a standard policy with $20,000 in personal property coverage and $100,000 in liability. Prices vary by borough, building age, and your claims history. Brownstones in Brooklyn Command higher premiums than post-war walk-ups in Queens because older plumbing and electrical systems increase risk. Your ZIP code matters more than neighbors realize when carriers calculate loss ratios. Bundle discounts apply if you have auto insurance with the same carrier. Combining policies typically saves 10 to 15 percent on both premiums. I reduced my combined cost by $180 annually by switching both to State Farm, but only after comparing quotes from four other carriers first. Some insurers won't write policies in certain buildings if they have frequent water damage claims on record. Check with your property manager about the building's insurance history before applying.
Get the Full Details
When You Absolutely Need Extra Coverage
If you work from home with expensive equipment, verify your policy covers business property. Standard policies exclude commercial use above certain thresholds. Laptops, cameras, and specialized tools used for freelance work might not be covered if the insurer determines you're running a business. Add a home business endorsement for an additional $50 to $100 yearly, or switch to a commercial policy if your gear exceeds $5,000 in value. Roommates create coverage complications even without disputes. If your friend sleeps on your couch during a break and their phone gets stolen, that claim might violate your policy terms. Each occupant should maintain their own renters insurance with listed personal properties. Shared policies create argument potential during settlements when cohabitation isn't disclosed at application. Disclose all residents when you apply, or risk claim denial for material misrepresentation.
The Documentation You Should Maintain
Create an inventory before you move in or right after settling. Photograph every item with serial numbers visible. Store receipts digitally in cloud storage accessible from multiple devices. When I rebuilt my inventory after the flood, spending two evenings documenting everything took longer than expected but prevented gaps in my claim. Without records, insurers default to conservative valuations that favor their position. Keep your policy declarations page with your important documents folder, not buried in email archives. Update it annually or after major purchases. Life changes trigger coverage needs that static policies don't address automatically. A promotion buying better clothes, a holiday gifting electronics, or adopting a pet requiring medical equipment all shift your risk profile. Most people forget to adjust until they file a claim and discover limitations. Liability coverage protects you if someone gets injured in your apartment or you damage another unit. Water damage spreading to the floor below affects more than your own possessions. Medical payments coverage handles minor injuries without requiring fault determination. A guest slipping on your wet bathroom floor qualifies regardless of who caused the condition. This coverage typically costs $5 to $10 extra annually and prevents small claims from becoming litigation.
Additional living expenses coverage pays for hotels and meals if your apartment becomes uninhabitable. Manhattan hotel rates range from $150 to $400 nightly depending on location and season. If a fire renders your unit unsafe for two weeks, your policy might cover $3,000 to $5,000 in temporary housing costs. Verify your daily limit and maximum payout before assuming standard coverage suffices. Some policies cap at 20 percent of your personal property limit, which might not stretch far in midtown hotels. Windstorm coverage operates differently in New York than other states. Coastal flooding from hurricanes isn't included in standard policies, but wind damage to windows or balconies might be. The 2012 Sandy storm exposed gaps in coverage assumptions across the boroughs. Policyholders with water damage from storm surge couldn't claim under renters insurance because flooding exclusions applied universally. Document your building's flood zone status and assess whether separate coverage makes financial sense. Identity theft protection appears in some policies as an added benefit rather than core coverage. Reimbursement for expenses related to fraudulent charges, legal fees, or credit monitoring ranges from $1,000 to $25,000 depending on the carrier. If your laptop gets stolen with tax documents inside, this endorsement covers recovery costs beyond replacing the hardware itself. Compare standalone identity theft services against policy inclusions to determine which provides better value for your situation.
Claims frequency affects future insurability more than individual payout amounts. Filing three small claims within two years might trigger non-renewal recommendations even if total payments stay under your deductible. Self-insure minor losses up to $500 or $1,000 rather than submitting every incident. One adjuster I knew rejected renewal after a policyholder filed five claims for minor damages totaling less than $2,000 combined. The carrier cited loss ratio concerns despite each claim appearing reasonable in isolation. Understanding your deductible structure prevents surprise out-of-pocket costs during settlements. Choosing $1,000 versus $2,500 deductibles shifts monthly premiums by $3 to $8, but that difference compounds annually. Higher deductibles make sense if you maintain emergency savings covering the gap. Lower deductibles suit people who prefer predictable costs over accumulated reserves. Evaluate your cash situation before selecting, then stick with that choice consistently across policy renewals. The claims reporting timeline varies by incident type but generally requires prompt notification. Fire, theft, and vandalism demands immediate reporting within 24 to 48 hours depending on policy language. Gradual damage from slow leaks or pest infestation doesn't qualify because insurers exclude wear-and-tear and maintenance failures. When my bathtub faucet leaked for weeks before causing ceiling damage downstairs, the adjuster denied the claim citing lack of timely reporting and preventable maintenance neglect.

Subrogation rights allow insurers to recover payments from responsible third parties after settling your claim. If a contractor causes damage while repairing your building, your carrier might pursue reimbursement from their liability policy. This process doesn't typically affect your claims history or future premiums because subrogation recovers what the insurer paid rather than creating new losses. Understanding this mechanism helps explain why carriers emphasize identifying responsible parties during investigations. Policy cancellation triggers specific notification requirements that differ from non-renewal procedures. Insurers must provide 10 to 30 days written notice before cancelling active policies, depending on state regulations and cancellation reasons. Non-payment, fraud, or increased risk exposure justifies cancellation, while claims filing alone usually doesn't. If your carrier cancels mid-term, you'll need alternative coverage immediately to avoid gaps that complicate future insurability. Review your policy annually regardless of renewal timing. Life changes, market shifts, and carrier adjustments create coverage drift that goes unnoticed until claims expose gaps. A promotion increasing your income might warrant higher liability limits. Renovation adding expensive fixtures requires scheduling individual items. Market conditions shifting premiums upward could make switching carriers worthwhile during renewal windows. Most people skip annual reviews and discover problems during stressful claim situations.
Mitigation duties require reasonable steps to prevent further damage after an incident occurs. If a pipe bursts, shutting off water and removing valuables from affected areas qualifies as expected action. Leaving damaged property exposed to additional harm through neglect might reduce settlement amounts. I learned this after failing to tarp a roof breach following hail damage, allowing rain to worsen ceiling deterioration beyond the initial impact area. The adjuster apportioned responsibility accordingly when calculating final payment. Proof of loss documentation varies by carrier but generally requires detailed written statements describing damaged or stolen property. Standard forms ask for item descriptions, values, acquisition dates, and circumstances surrounding losses. Providing complete information upfront prevents delays and disputes during adjustment. Incomplete submissions trigger requests for additional documentation that extend settlement timelines by weeks or months. Prepare inventories and supporting materials before incidents occur rather than assembling records under pressure. Appraisal clauses provide dispute resolution mechanisms when you and your insurer disagree on settlement amounts. Independent appraisers examine damages and determine fair value, with each party selecting one umpire who makes final decisions. This process costs time and potentially money but avoids litigation for contested claims. Use appraisal provisions sparingly since they work best for legitimate valuation disagreements rather than coverage interpretion disputes where policy language clearly applies.
Extended replacement cost coverage addresses inflation and construction cost increases beyond standard policy limits. Building material price spikes and labor shortages can push reconstruction expenses past original estimates, particularly in expensive markets like New York. Some carriers offer 125 to 150 percent of dwelling coverage automatically, while others require endorsements. Verify your policy includes adequate protection if you rent from owners rather than management companies handling replacements independently. Ordinance or law coverage handles increased rebuilding costs due to updated building codes following damage. Older Manhattan buildings might require electrical, plumbing, or structural upgrades when repairing storm or fire damage, adding expense beyond original construction values. Standard policies exclude code compliance costs unless specifically endorsed. If your landlord's policy lacks this coverage, verify your renters policy addresses potential gaps in protection for shared responsibility scenarios. Water backup endorsements cover sewer and drain overflow damage explicitly excluded from base policies. Basement apartments and ground-floor units face higher risk during heavy rainfall events common in Northeastern storms. The endorsement typically costs $50 to $150 annually but prevents catastrophic out-of-pocket losses from backed-up lines. Assess your unit's flood vulnerability based on elevation, proximity to water mains, and historical storm damage patterns in your neighborhood before deciding whether the premium justifies the protection.
Service line coverage protects underground utilities connecting your unit to main systems outside the building envelope. Water, gas, and electrical service lines running through shared walls or foundations create liability questions when damage affects multiple units. Determine responsibility for repair costs based on lease terms, building agreements, and applicable insurance policies before incidents create disputes. Clear documentation prevents confusion during emergency situations requiring immediate repairs.
Practical Steps Before Applying
Walk through your apartment documenting everything with photographs and video. Open closets, cabinets, under beds, and storage areas where items accumulate out of sight. Record serial numbers on electronics, appliances, and valuable possessions. Estimate replacement costs using current retail prices rather than original purchase amounts, since inflation affects reimbursement calculations. This process takes two to three hours but creates records that simplify claims by months or years. Compare quotes from at least three carriers before selecting coverage. Price variations for identical coverage levels can exceed 30 percent depending on underwriting algorithms and local loss data. Online calculators provide quick estimates, but speaking with agents clarifies coverage details and discounts you might miss online. Ask about bundling opportunities, claims-free discounts, and protective device rebates for installed smoke detectors or security systems. Read the actual policy language before relying on agent summaries or marketing materials. Definitions of covered perils, exclusions, and limits appear in sections people rarely review during purchasing decisions. Pay attention to special limits on electronics, jewelry, firearms, and business property that apply automatically regardless of stated coverage amounts. Endorsements modify standard terms, so verify selected additions appear on declarations pages before premiums process.
Choose deductibles based on your ability to pay out-of-pocket rather than minimizing monthly costs alone. Higher deductibles reduce premiums but require cash reserves when claims occur. If $1,000 represents two weeks of groceries or gas money for you, that deductible might create financial strain during stressful claim situations. Balance affordability with practicality, selecting amounts you could cover without delaying essential expenses while waiting for settlements. Maintain communication records with agents, adjusters, and customer service representatives throughout your policy term. Email confirmations, claim numbers, and correspondence dates help resolve disputes that arise months or years after transactions. Written documentation trumps verbal agreements in most claim controversies. Save copies of applications, endorsements, payment receipts, and correspondence in organized digital folders accessible from multiple devices.
Common Mistakes That Void Coverage
Leaving apartments vacant beyond policy-specified periods without notification creates coverage gaps. Most policies require occupancy or regular inspection visits every 30 to 60 days, varying by carrier. Extended absences for travel, work assignments, or seasonal living without disclosure might void claims for vandalism, theft, or freeze damage occurring during unmonitored periods. Notify your insurer if you'll be away longer than standard allowances before problems arise. Failure to report material changes in risk profile when applying or renewing policies invalidates coverage retroactively. Renovations adding hazardous equipment, business operations exceeding home use thresholds, or rental arrangements with short-term guests all change risk characteristics. Undisclosed modifications give insurers grounds to deny claims based on misrepresentation. Report changes promptly rather than assuming minor alterations fall below reporting thresholds. Neglecting maintenance responsibilities that contribute to damage creates coverage disputes during settlements. Slow leaks, peeling paint, malfunctioning appliances, and deteriorating fixtures represent preventable conditions insurers exclude from protection. When damage results from ignored maintenance rather than sudden accidents, carriers deny claims citing avoidable cause. Regular inspection and repair of building systems and appliances protects both your possessions and your coverage eligibility.
Storing valuables in uninsurable locations like unattended vehicles or outdoor spaces creates coverage limitations. Jewelry left in glove compartments, cameras stored in car trunks, or laptops abandoned on patio furniture fall outside standard policy protections. Theaters, museums, and safety deposit boxes provide secure alternatives for high-value items requiring specialized coverage. Consult your agent about scheduled personal property endorsements if you possess items exceeding standard sub-limits or requiring enhanced protection. Assuming coverage extends to damage affecting business property or professional activities creates unexpected gaps. Home offices with client meetings, freelance operations exceeding casual use thresholds, or inventory stored for commercial purposes might violate standard renters policy terms. Business interruption, equipment breakdown, and professional liability require separate coverage through commercial policies or specialized endorsements. Verify your activities qualify under personal policy language before relying on assumed protections.

What Happens During A Claim Investigation
Adjusters examine damage scenes, review documentation, and determine coverage applicability based on policy language and circumstantial evidence. Processes typically take 7 to 14 days for straightforward claims but extend to 30 days or longer for complex disputes involving multiple parties or extensive damage. Communication during investigations maintains transparency about progress and expected timelines, though specifics depend on carrier workload and claim complexity. Independent inspection reports support your position when documenting damage extent and cause. Photographs, videos, and written descriptions created immediately after incidents provide evidence adjusters reference during evaluations. Professional assessments from contractors, electricians, or plumbers documenting repair estimates and cause analysis strengthen claims requiring technical explanations beyond visual inspection capabilities. Maintain all documentation throughout the claims process regardless of settlement timing. Settlement calculations consider actual cash value or replacement cost depending on policy selections and applicable endorsements. Depreciation deductions reduce payouts for aged items under actual cash value provisions, while replacement cost endorsements eliminate depreciation calculations for eligible losses. Selecting appropriate valuation methods at policy inception determines settlement amounts without negotiation during claims, making this decision more important than most buyers realize during purchasing.
Payment distribution follows carrier procedures typically processing within 5 to 10 business days after settlement approval. Electronic transfers, checks, or direct deposits vary by carrier preference and claimant selection. Partial payments address immediate needs while final settlements resolve remaining balances after complete documentation review. Multiple installments Appeals processes address disputed claim determinations through internal reviews or external arbitration depending on policy provisions and state regulations. Carriers reconsider denials when additional documentation or evidence emerges supporting coverage applicability. Formal appeals require written requests detailing disagreement points and supporting materials within specified timeframes, typically 30 to 60 days from denial notification. Successful appeals modify original determinations but don't guarantee favorable outcomes in all cases. Subrogation recovery efforts by carriers pursuing responsible third parties don't typically affect claimant obligations or reimbursement responsibilities. Insurers handle legal proceedings and associated costs separately from policyholder responsibilities during normal claims administration. Your cooperation might include providing documentation, statements, or access to damaged property, but financial recovery actions remain carrier responsibilities once coverage applies and settlements process.
Long-Term Policy Management Strategies
Annual policy reviews identify coverage gaps, discount opportunities, and market conditions warranting carrier changes. Premium comparisons across providers reveal pricing variations that accumulated savings justify switching decisions. Coverage adequacy assessments ensure protection levels match current asset values and liability exposures as circumstances evolve. Document review findings and action plans for addressing identified deficiencies before annual renewal periods arrive. Claims history management influences future insurability and premium calculations across multiple carriers. Three or more claims within five years typically triggers non-renewal considerations or surplus market placement requiring specialized brokers. Understanding this dynamic helps explain why self-insuring smaller losses sometimes proves economically rational compared to claiming through insurance systems. Maintain claims-free status when possible by addressing preventable conditions through maintenance and risk mitigation strategies. Documentation preservation beyond policy termination periods supports future claims, audits, or legal proceedings requiring historical coverage evidence. Some jurisdictions mandate retention periods of three to seven years for insurance records, while practical considerations suggest keeping documents as long as statute of limitations periods apply to potential claims. Organized storage systems prevent document loss during moves, renovations, or technological transitions that might otherwise destroy irreplaceable records.
Estate planning coordination ensures coverage continues appropriately during life transitions involving property transfers, inheritance, or relationship changes. Divorce, marriage, death, and adoption all affect insurance needs and beneficiary designations requiring policy updates. Coordinate with attorneys, financial advisors, and insurance agents to ensure coverage continuity during transitional periods when gaps might otherwise occur between old and new arrangements. Technology integration with policy management platforms simplifies documentation storage, claim reporting, and communication with carriers. Mobile apps enable photo documentation, claim filing, and payment tracking from smartphones rather than requiring computer access or paper forms. Digital organization reduces administrative burden while improving accessibility during emergency situations requiring immediate policy information or claim status updates. Evaluate platform features before committing to carriers offering inferior technological support.
City-Specific Considerations For NYC Renters
Co-op and condo buildings operate differently than rental apartments regarding insurance requirements and coverage expectations. Shareholders often must maintain specific coverage levels mandated by board requirements beyond standard renters policies. Master policies covering building structures might leave gaps for interior elements, fixtures, and improvements requiring individual shareholder policies addressing responsibility distinctions. Understand your building's insurance architecture before selecting coverage ensuring no protection gaps exist. High-rise living introduces unique risks including wind damage through windows, water damage from upper-unit failures, and elevator-related injuries affecting liability exposures. Building maintenance quality directly impacts individual unit risk profiles, making property management reputation relevant to coverage decisions. Insurance carriers sometimes decline policies for buildings with frequent claims histories or deferred maintenance patterns affecting overall risk assessments. Subway and transit proximity creates theft and vandalism risks distinct from suburban environments. Ground-floor apartments near stations face higher incident rates affecting premium calculations and coverage availability. Security system installations, window treatments, and entry point reinforcements reduce risk profiles sometimes qualifying for discount adjustments during policy renewals. Document protective measures when applying for quotes to ensure appropriate pricing reflecting actual risk characteristics.
Pest infestations from rodents, cockroaches, and other organisms represent maintenance issues excluded from standard coverage but common in aging urban buildings. Damage from infestations requiring extermination, repair, and replacement falls outside insurance protection requiring landlord responsibility or tenant maintenance obligations depending on lease terms and local regulations. Understanding responsibility allocations prevents confusion during incidents requiring immediate attention and resolution. Street noise, odor, and environmental factors from busy corridors might affect habitability without constituting insurable events. Coverage for additional living expenses requires uninhabitable conditions meeting policy definitions rather than discomfort or annoyance from normal urban living characteristics. Distinguishing between nuisance conditions and actual damage helps set realistic expectations about coverage applicability during claim discussions with carriers and adjusters. Seasonal weather variations from summer humidity to winter freezing temperatures create distinct risk categories affecting prevention strategies and coverage considerations. Freeze damage from unheated units, storm damage from hurricane season, and heat-related appliance failures each require different protection approaches. Understanding seasonal risk patterns helps implement appropriate preventive measures and ensures coverage addresses region-specific hazards rather than generic perils only.
Tenant rights and landlord obligations under local housing codes create insurance implications beyond standard policy language. Emergency repair responsibilities, habitability requirements, and security standards might affect coverage availability or premium calculations depending on building code compliance status. Understanding regulatory requirements helps ensure both tenant and landlord protections align with legal obligations while maintaining appropriate insurance coverage levels.
Final Thoughts On Protecting Your NYC Apartment
Renters insurance in Manhattan requires more attention to detail than suburban policies due to higher values, denser populations, and unique urban risks. Policy selection involves balancing cost, coverage adequacy, and carrier reliability while understanding exclusions and limitations affecting claim outcomes. Documentation, maintenance, and proactive communication with carriers throughout policy terms create stronger positions during claims than reactive approaches relying on hope for favorable outcomes. The investment in proper coverage typically returns multiples during actual claims through protection of assets worth far more than annual premiums. Comparing options, reading policy language, and maintaining organized records prevents surprises during stressful claim situations requiring quick decisions and documentation. Understanding how claims actually work based on policy terms rather than assumptions creates realistic expectations and better outcomes when incidents requiring coverage occur.
