State Farm Business Insurance Guide For Small And Mediumsized Businesses
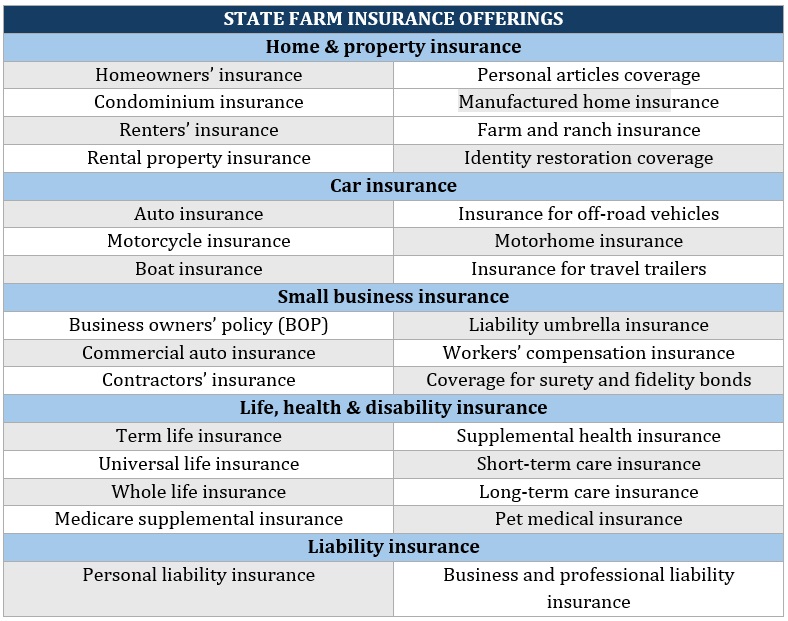
The State Farm Business Insurance Guide is basically a structured approach to figuring out what coverage your company actually needs. Not the marketing page version, the real version where you sit down and map your operations against policy types. I've watched a lot of business owners breeze through these guides and come out with either too much coverage or the wrong kind entirely. The guide itself walks you through identifying risks, selecting policies, and understanding how they layer together. Here's how I'd actually use it if you're running a small operation and don't want to overpay or underinsure. First, you need to understand that State Farm doesn't offer a single "business insurance" product. They package several lines together, and the guide helps you pick which ones apply. The main pieces are general liability, commercial property, workers' compensation, commercial auto, and professional liability depending on your line of work. There's also a businessowners policy (BOP) that bundles some of these for smaller businesses at a discounted rate.
Working Through the State Farm Business Insurance Guide For Small And Mediumsized Businesses
The process starts with an inventory of your physical assets. Not just the building, but equipment, inventory, furniture, and any leased improvements. I learned this the hard way when a client had a solid property policy that covered the structure but excluded equipment installed after the policy was written. They had new CNC machines that cost $40,000 between them, and those weren't on the schedule. Took two weeks and a lot of paperwork to get them added, and during that window, we were technically uncovered. Always make sure your guide includes a machine schedule that you update whenever purchases happen. Next step is evaluating your liability exposure. This is where most people shortchange themselves. General liability covers things like a customer slipping in your store or you accidentally damaging someone else's property. But if you're providing advice or professional services, that falls under professional liability, sometimes called errors and omissions. State Farm's guide separates these clearly, and the premium difference between them can be significant. A general liability policy alone won't touch a professional negligence claim. If you have employees, workers' compensation is going to be the biggest line item after your payroll. Every state has different thresholds. Some require coverage from the first employee, others don't kick in until you hit five or ten. The guide has state-specific tables, but don't just fill them in and move on. Verify with your state's labor department because the rules change and the guide might be slightly behind on recent legislative updates. I've seen outdated references in these materials, particularly around independent contractor classifications which affect whether you need to cover them.
Commercial auto is another area where people get tripped up. If your business owns vehicles, you need a commercial policy. Your personal auto insurance will explicitly exclude business use, and if you get into an accident while working, your personal policy could deny the claim entirely. The guide walks you through rating your fleet, which depends on the type of vehicles, how they're used, and the drivers. One nuance that bites people: if an employee uses their personal car for work occasionally, you need hired and non-owned auto coverage. It's cheap to add but easy to forget. I once had a consulting firm that ran a site visit in an employee's personal SUV without this coverage. The employee was at fault in an accident, and the client's legal team came after the business because they should have had that protection. It cost them $18,000 out of pocket because the exclusion was in their policy. Business interruption coverage deserves its own attention. This isn't optional insurance, it's the coverage that keeps you solvent if your location gets damaged and you can't operate. State Farm's guide explains it as covering lost income and extra expenses during the restoration period. The tricky part is setting the right limit. A lot of business owners pick a arbitrary number, maybe six months of revenue. The problem is that some recoveries take longer. A flood or fire can put you out for a year or more, and if your limit is six months, you're on your own after that. I recommend calculating based on at least twelve months of gross earnings plus ongoing fixed expenses, then adding a margin. The guide has formulas for this, but don't just copy-paste from last year. Inflation and business growth change your actual exposure. There are some edge cases in the guide that aren't obvious. Cyber liability is one. State Farm offers it as an endorsement or a separate policy, but the coverage varies widely depending on which option you get. Basic endorsements often have low limits and exclude certain types of attacks. If you handle customer data, payment card information, or even just email with sensitive business communications, you should look at a dedicated cyber policy rather than riding on a businessowners policy endorsement. I encountered a situation where a small retail shop had a minor data breach through a phishing email, and their basic cyber endorsement had a $25,000 limit with a $5,000 deductible. The incident response and notification costs alone exceeded that. They ended up with a gap that cost them roughly $34,000 in out-of-pocket expenses including legal fees and credit monitoring for affected customers.
Get the Full Details
Another counter-intuitive point: having multiple policies from State Farm doesn't automatically give you broader coverage than a single BOP. Sometimes bundling actually creates gaps because each policy has its own exclusions and conditions. The guide mentions this briefly, but it bears repeating. A standalone general liability policy might have better terms than the GL portion of a BOP. You need to compare the actual policy language, not just assume the bundled version is fine. The same goes for property. Sometimes a scheduled floater or inland marine policy covers items better than the standard property form in a BOP. When you're filling out the guide, be specific about your operations. Vague descriptions like "retail store" or "consulting" can lead to misclassification. If you sell products online and also have a physical location, that's two exposures, not one. If you do both retail and contract work, you may need two different policy structures. State Farm agents are supposed to help with this during the quoting process, but they're often handling dozens of leads at once. Come in with your own notes. Write down every business activity, every location, every vehicle, every employee category. The more detail you provide upfront, the fewer surprises come out during a claim. One practical thing the guide doesn't emphasize enough: your policy should name additional insureds where appropriate. If you lease space or work with subcontractors, they might request additional insured status on your general liability policy. State Farm allows this through endorsements, but you have to request it. It's usually a small premium increase, maybe $25 to $75 per endorsement depending on the situation. Not doing it can delay projects or cause contract disputes. A few years back I dealt with a client who was bidding on a commercial renovation job, and the general contractor rejected their certificate of insurance because it didn't list the GC as an additional insured. The bid was already open, and by the time they got the endorsement sorted, they'd lost the job to a competitor who had done it right from the start. That was a lost contract worth approximately $47,000.
The review process matters too. Don't set your policy and forget it. At minimum, do an annual review with your agent, but really you should review after any significant change: hiring staff, buying equipment, opening a second location, changing service offerings, or even major renovations. The guide has a checklist for this, and it's worth using. I keep a simple log for my own business policies where I note the date of each review, what changed, and what adjustments were made. It takes about ten minutes and prevents the kind of situation where you find out you're underinsured because something shifted and nobody updated the paperwork. Cost-wise, a typical BOP for a small business with modest revenue and a single location usually runs between $500 and $2,000 annually. Workers' comp varies wildly by industry and payroll size, but expect it to be your largest line. A small office with three employees might see $3,000 to $8,000 a year. Commercial auto adds $1,000 to $3,000 per vehicle depending on usage and driver history. Professional liability for a consulting business could run another $1,000 to $4,000 annually. These are rough numbers from what I've seen across a range of clients. The exact premiums depend on your location, claims history, coverage limits, and deductibles you choose. If State Farm's offerings don't fit your situation, especially for higher-risk industries or businesses with complex operations, it's worth shopping other carriers. State Farm is solid for straightforward small business needs, but they're not the best fit for everything. Contractors in certain trades, restaurants, healthcare providers, and tech companies sometimes get better terms and broader coverage from specialty carriers. The guide mentions this implicitly by outlining where each policy type applies, but it doesn't tell you when to look elsewhere. Trust your own assessment of the risk. If something feels off about the coverage gaps, it probably is.
Getting started is straightforward. You can download the State Farm Business Insurance Guide For Small And Mediumsized Businesses directly from their website, fill it out at home, and bring it to an agent appointment. Or you can skip the paper and go straight to an agent who will walk you through the same questions. Either way, come prepared. The guide is useful, but it's a framework, not a substitute for thinking through your actual business operations. The people who get the best outcomes are the ones who treat it like a planning document rather than a form to check off.