Getting Started With Equipment Financing When You Have No Track Record
The biggest problem most first-time founders run into is showing up to a lender with nothing but a pitch deck and expecting to walk out with $50,000 for a CNC machine. It doesn't work that way. Equipment financing is one of the more straightforward funding avenues because the asset itself serves as collateral, which reduces the lender's risk compared to unsecured working capital loans. But "straightforward" does not mean easy if your business has less than two years of revenue history. I learned this the hard way when my first venture tried to finance a fleet of delivery vans at eight months old. We were approved for half what we needed, at an annual percentage rate that felt punitive, and the loan came with a personal guarantee clause that basically tied my house to the payments. That experience taught me enough about how these deals actually work to help someone else avoid the same mistakes. At its core, startup equipment financing involves borrowing money specifically to purchase business assets, with the equipment serving as the collateral. If you default, the lender repossesses the equipment. This is fundamentally different from a general business loan where the lender may also place a lien on your accounts receivable or other assets. With equipment financing, the underwriting focus stays primarily on the asset's value and its expected useful life. Lenders will appraise what the equipment is worth today and what it will likely be worth at the end of the loan term. That depreciation schedule directly influences how much they are willing to finance and over what period.
Startup Equipment Financing Your Complete Guide To Powering Growth With Precision Capital
Before you fill out any applications, you need to understand the three main structures available to startups and small businesses, because each one plays differently against your cash flow. A standard equipment loan works the way most people imagine it. The lender pays the vendor directly, you make monthly payments including principal and interest over a set term, and once the balance reaches zero, you own the equipment free and clear. Typical terms range from three to seven years for most small business equipment. The loan amount usually covers between eighty and one hundred percent of the equipment's purchase price. Anything above eighty percent typically requires stronger financials or a larger down payment. Equipment leasing operates differently. You are essentially renting the equipment with an option to purchase at the end of the lease term. There are two main varieties worth knowing about. A capital lease transfers ownership to you at the end, similar to a loan but structured as a lease for accounting purposes. An operating lease treats the payments as a rental expense and does not result in ownership. Operating leases are more common for technology equipment that becomes obsolete quickly, while capital leases are better suited for long-lasting machinery like industrial generators or commercial kitchen equipment.
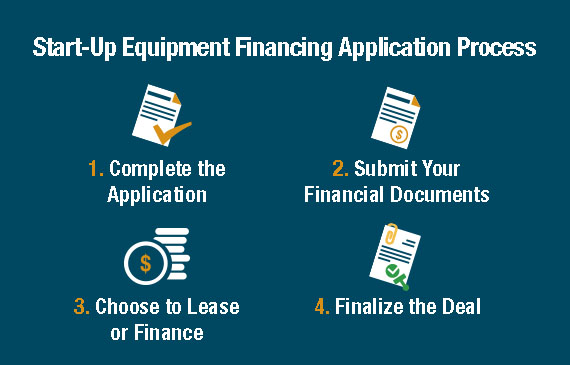
lease-to-own programs sit somewhere between these two. You make monthly payments and have the option to buy the equipment at a predetermined price at the end of the term. These programs are often more flexible with credit requirements but carry higher effective interest rates than traditional equipment loans. I used a lease-to-own arrangement for a medical practice's imaging equipment once because the lender wanted eighty percent of the purchase price upfront as a down payment through a traditional loan. The lease-to-own structure let us keep eighty percent of our cash reserve intact while still getting the equipment running within two weeks. SBA 504 loans deserve a mention even though they are harder to qualify for at the startup stage. These are government-backed loans specifically designed for purchasing real estate and heavy equipment. The advantage is significantly lower interest rates and longer repayment terms, sometimes up to twenty-five years for real estate portions. The tradeoff is a much longer application process, more documentation requirements, and strict eligibility criteria around business size and use of proceeds. For a startup trying to move fast, an SBA 504 might not be practical unless you have at least three years of operating history and substantial collateral to support the application. The application process itself typically requires several documents that go beyond what you need for a regular business credit card or line of credit. You will need your business plan, at least twelve months of financial statements if available, personal tax returns for the past three years, a detailed equipment quote from the vendor, and information about your personal credit history. Some lenders will also ask for a statement of purpose explaining exactly how the equipment supports your business operations. Having this packet organized before you approach any lender cuts the initial review time from roughly two weeks down to about five business days.
Get the Full Details
What Most Startups Get Wrong About Equipment Financing
The most common mistake is overborrowing. Founders see that a lender will finance up to one hundred percent of the equipment cost and assume they should take the maximum available. This creates a payment obligation that strangles your operating budget during the earliest and most fragile phase of the business. A better approach is to finance only what you genuinely need and put down a meaningful portion yourself, even if it means delaying the purchase slightly. A twenty percent down payment demonstrates commitment to the lender and often results in better terms, lower monthly payments, and a shorter amortization period. Another frequent error is ignoring the total cost of ownership beyond the financing payments. Equipment requires maintenance, insurance, software updates, and eventual replacement parts. An MRI machine, for example, might have monthly financing payments of four thousand dollars but could require thirty thousand dollars in annual maintenance contracts. The financing terms look reasonable in isolation, but the ongoing costs make the overall commitment significantly larger than the monthly payment suggests. Always factor in at least ten to fifteen percent of the equipment cost annually for maintenance and operational expenses when modeling your cash flow. Prepayment penalties are another hidden cost that catches people off guard. Many equipment loan agreements include clauses that charge a fee if you pay off the loan early. These penalties typically range from one to three percent of the remaining balance and can persist for the first two to three years of the loan. If you have a path to generating excess cash within the first year, seek out lenders that do not impose prepayment penalties. The slightly higher interest rate on a no-penalty loan is almost always cheaper than paying a one-time penalty fee later.
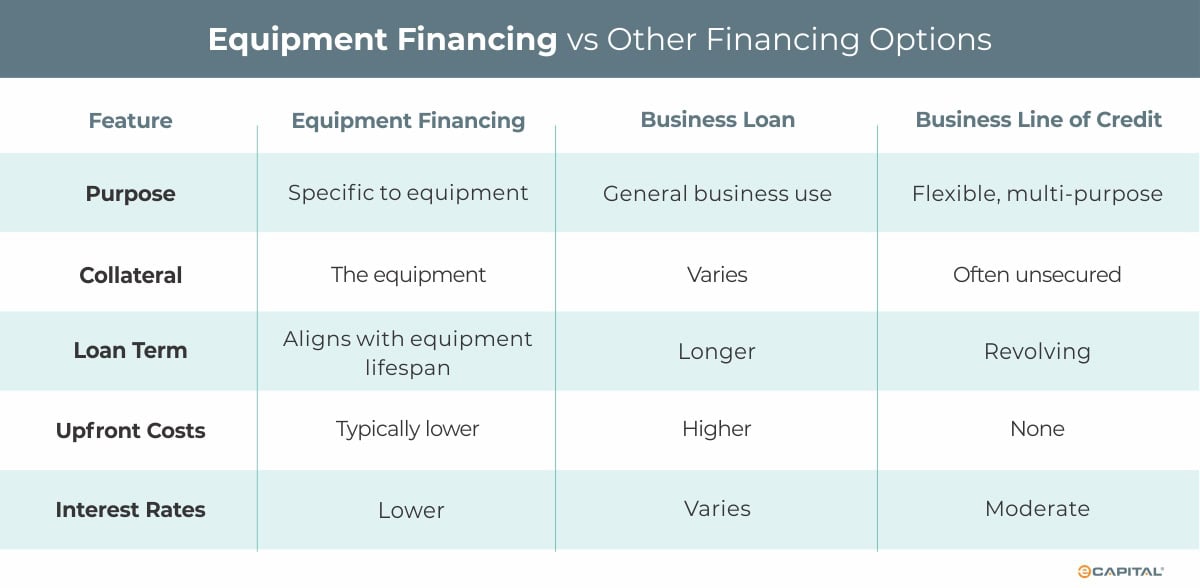
Credit requirements vary significantly across lenders, and the spread is wider than most founders expect. Community banks and credit unions often have more flexible underwriting standards than national online lenders. A national online lender might require a minimum credit score of six hundred eighty and two years of revenue. A regional credit union working with your local Small Business Development Center might approve the same application at a credit score of six hundred twenty with only six months of revenue history. The online lender's process will be faster, sometimes within forty-eight hours, while the credit union route might take three to four weeks. Speed and accessibility are not always aligned with the best terms available. There is also the question of whether equipment financing makes sense compared to alternative funding sources. If the equipment you need is relatively inexpensive, under ten thousand dollars, and generates immediate revenue that easily covers the payments, a business credit card or a short-term line of credit might be more efficient. The administrative overhead of an equipment loan application, with its documentation requirements and underwriting timeline, can be disproportionate to the financing amount. For equipment above fifteen thousand dollars, the dedicated equipment loan structure almost always provides better terms and clearer cash flow management than general business financing products.
Working Through a Real Application Scenario
I was advising a client who wanted to finance a fleet of twenty refrigerated vans for a grocery delivery startup. The equipment quote came to roughly two hundred fifty thousand dollars. The traditional approach would have been to apply for an equipment loan covering the full amount. Instead, we structured the deal differently. We financed twelve vans through a equipment loan at a seven-year term with a nine and a half percent interest rate, covering ninety percent of each van's cost. The remaining eight vans were acquired through a lease-to-own program with a five-year term and a slightly higher effective rate of eleven percent. The lease-to-own structure was chosen because those specific van models had been discontinued and the lender viewed them as higher risk due to uncertain resale values. Splitting the financing across two structures allowed us to secure better terms on the core fleet while accommodating the risk profile of the newer models. The application for the equipment loan portion required the usual documentation plus a detailed fleet utilization plan showing projected delivery volume and revenue per van. The lease-to-own program required fewer financial documents but moved through underwriting faster, partly because the lessor was more comfortable with shorter commitment periods for the higher-risk vehicles. Together, the combined approach reduced our average monthly payment by approximately twelve percent compared to financing all twenty vans through a single equipment loan at standard terms. The practical takeaway here is that you do not need to commit to a single financing structure for your entire equipment purchase. Mixed financing arrangements are common and often produce better overall terms. However, mixing structures adds administrative complexity. You will have two sets of payment schedules, two points of contact, and potentially two different documentation renewal cycles. Factor in that additional management overhead when deciding whether splitting your financing is worth the savings.
Key Negotiation Points That Lenders Expect You to Ask About
Interest rates on equipment financing for startups typically range from eight to eighteen percent depending on creditworthiness, the equipment type, and the lender. Most borrowers accept the first rate offered without negotiation. This is unnecessary. Equipment financing rates are not fixed prices. They are negotiated based on your risk profile and the lender's willingness to compete for your business. Getting two or three quotes from different lenders is standard practice and can lower your rate by one to three percentage points. On a one hundred thousand dollar loan over seven years, that difference translates to roughly four to twelve thousand dollars in total interest savings. Loan terms are another point where negotiation matters. The standard seven-year term is a baseline, not a ceiling. If your equipment has a longer useful life, such as industrial manufacturing machinery that may last ten to twelve years, you can request a longer amortization period. A ten-year term on the same one hundred thousand dollar loan at eight percent would reduce your monthly payment by approximately three hundred dollars compared to the seven-year structure. The total interest paid increases, but the monthly cash flow relief can be critical for a startup operating on thin margins. Personal guarantees are a reality of startup equipment financing. Most lenders will require at least one personal guarantee, often from the founder with the highest net worth. This is not optional in most cases and is not a sign that the lender does not believe in your business. It is standard practice for any loan where the business itself lacks sufficient credit history. What you can negotiate is the scope of the personal guarantee. Some lenders will accept a partial guarantee limited to a percentage of the loan balance rather than the full amount. Others may release the personal guarantee after two years of on-time payments. Getting this clause in writing before you sign is essential.
Covenants attached to equipment loans can create unexpected problems. Financial covenants requiring you to maintain certain debt service coverage ratios or minimum revenue thresholds are common. If your startup experiences a seasonal dip or a slower than expected ramp-up, missing a covenant can trigger a default even if you are current on your payments. Request covenant packages that align with realistic startup performance trajectories rather than established business benchmarks. A lender who insists on mature business covenants for a two-year-old startup is a red flag that they do not understand your market. Insurance requirements are another area where costs can surprise you. Lenders will require you to maintain comprehensive insurance on the financed equipment, including property damage and liability coverage. The minimum coverage amounts are set by the lender, not by you. These minimums can be significantly higher than what you might choose on your own. Understand the insurance requirement before you sign and obtain quotes from your insurance provider early in the process. The combination of loan payments and required insurance premiums can increase your total monthly equipment cost by twenty to thirty percent compared to the base loan payment alone.
When Equipment Financing Is the Wrong Choice
There are scenarios where pursuing equipment financing actively works against your interests. If you are financing consumer electronics or technology equipment with a rapid depreciation cycle, such as computers, tablets, or software hardware that becomes obsolete within three years, leasing through an operating lease structure is usually more appropriate than a loan. Ownership of rapidly depreciating equipment leaves you holding assets worth a fraction of their original cost while still owing the full balance. An operating lease lets you upgrade to newer equipment at the end of the lease term without the burden of selling or disposing of outdated assets. Another scenario where equipment financing fails is when the equipment does not generate sufficient revenue to cover the payments within a reasonable timeframe. I worked with a bakery startup that financed a commercial oven at twelve thousand dollars with monthly payments of two hundred eighty dollars. The oven was functional and beautiful, but the location had such low foot traffic that monthly revenue barely covered rent and utilities. The oven payments went unpaid for four months before the business closed. Equipment financing amplifies your fixed costs, which is dangerous when revenue is uncertain. Only finance equipment if you have validated demand or contractual revenue that covers the payments with a comfortable margin. A third situation to avoid is using equipment financing as a substitute for understanding your business model. Some founders take out equipment loans to purchase assets they believe will solve operational problems without first confirming that the assets address real bottlenecks. A delivery van fleet does not help if you have no customers ordering deliveries. Equipment financing should fund expansion into proven demand, not fund speculation about future demand. Validate your revenue model independently of the financing decision before committing to any equipment purchase.
Practical Steps to Execute Your Equipment Financing Plan
Start by documenting exactly what equipment you need, the specifications, and the current market price from at least three vendors. Having competing quotes gives you leverage during negotiations and prevents vendors from inflating prices knowing you are financing the purchase. Next, pull your personal credit report and review it for errors. Disputing and correcting any inaccuracies before you apply can improve your credit score by ten to thirty points, which directly impacts the rates available to you. This step typically takes one to two weeks and should be done before any formal application. Prepare your business financial package including twelve months of profit and loss statements, balance sheets, and cash flow projections for the next twenty-four months. If you are pre-revenue, include detailed market research and customer acquisition plans that demonstrate how the equipment will generate revenue. Lenders prefer projections backed by research over optimistic estimates without supporting data. Include a equipment utilization schedule showing expected hours of operation per day and revenue generated per hour of equipment use. This level of detail distinguishes serious applications from speculative ones. Apply to at least three lenders simultaneously. Start with your existing banking relationship if you have one, then approach a community bank or credit union in your area, and finally submit an application to a reputable online equipment financing lender. Each application will generate a hard inquiry on your credit report, so consolidating your applications within a fourteen to thirty-day window minimizes the impact on your credit score. Most credit scoring models treat multiple inquiries for the same type of loan within this period as a single inquiry.
Once offers arrive, compare them using the total cost of ownership rather than just the monthly payment or interest rate. Calculate the total amount you will pay over the full term including all fees, insurance minimums, and any prepayment penalties. Compare this total across all offers. The lowest monthly payment is not always the best deal if it comes with higher fees, longer terms that increase total interest, or restrictive covenants that limit your operational flexibility. A slightly higher monthly payment on a cleaner loan structure often proves cheaper and less risky over the life of the financing. After signing, set up automatic payments from your business checking account to avoid missed payments and late fees. Track the equipment's condition and maintenance schedule diligently. Proper maintenance preserves the equipment's resale value, which matters if you need to refinance, sell, or upgrade before the loan term ends. Equipment that is well-maintained retains thirty to forty percent of its value after five years, while neglected equipment may retain only ten to fifteen percent. This difference in residual value affects your options if circumstances change and you need to exit the financing arrangement early. The equipment financing process for a typical small business startup takes between two and six weeks from initial application to funds disbursed, depending on the lender and the complexity of the equipment. Equipment that requires specialized appraisal or certification, such as medical devices or heavy industrial machinery, can extend the timeline to eight to twelve weeks. Plan your purchase schedule accordingly. Do not wait until the week before you need the equipment to begin the financing process. Ordering equipment before financing is secured is a common pattern that leads to rushed decisions and acceptance of unfavorable terms simply to avoid delays.