Using St. Louis Community Credit Union for Everyday Banking
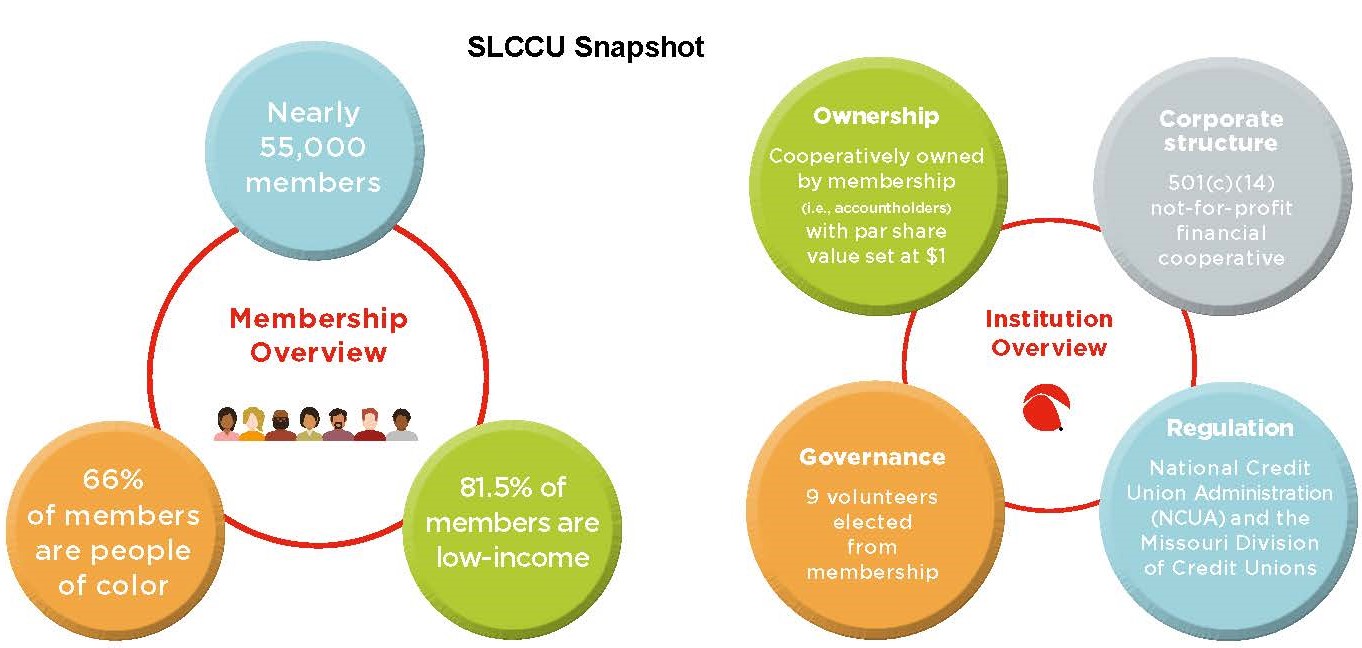
I've been navigating credit union banking for years now, and St. Louis Community Credit Union keeps coming up as a solid option for people who want something different from the big national banks. Let me walk through how it actually works in practice, including the stuff the marketing page doesn't really highlight. The credit union operates out of Missouri and serves a broad membership base. They offer checking accounts, savings products, personal loans, auto loans, and home lending. The typical draw is lower fees and better rates than what you'd get at a conventional bank, which makes sense since they're not answering to shareholders. But "better rates" is vague without context, so let's get specific. Their Share Savings account is one of the more competitive options in the region. I've seen APY rates consistently above 4% in recent years, which compares favorably against most large bank offerings that often sit under 1%. The tradeoff is minimum balance requirements. You need a certain threshold to unlock the best advertised rate, and if you drop below it, the rate recalculates daily. That can catch people off guard if they're not tracking their balance closely.
The online and mobile banking platform is functional but not particularly polished. I had a situation last year where I tried to set up a recurring automatic transfer between two of my accounts using the app. It kept failing silently, meaning the transfer never executed despite my confirmation screen saying it was scheduled. It took three business days and two phone calls to get it sorted out. Their support line eventually walked me through doing it via web instead, and it worked fine. The workaround is to avoid scheduling transfers through the mobile app and use the full website version instead. The UI is more cluttered on desktop, but the feature actually works there.
Getting Started and What Actually Matters
To open an account you need a $5 minimum deposit, a government-issued ID, and your Social Security number. Membership is open to anyone who lives, works, or worships in certain Missouri counties or is a member of affiliated organizations. The eligibility requirements are reasonable and fairly easy to satisfy for most people in the area. One thing beginners miss about credit unions is the dividend structure. Unlike interest on a bank account, dividends are technically distributed from the credit union's earnings. That means they can fluctuate quarter to quarter based on how well the institution is performing. It rarely drops to zero, but it's not guaranteed either. If you're budgeting around expected earnings from your savings, build in a small buffer rather than assuming a fixed annual rate. Another counter-intuitive detail: credit unions are insured by the NCUA, not the FDIC. The coverage is identical at $250,000 per depositor per account ownership category, but the backing comes from a federal agency rather than the bank insurance fund. For practical purposes this makes no real difference to you as a customer, but it matters if you ever hear someone arguing that credit unions are less safe than banks. They aren't. The insurance is equally solid.
Get the Full Details
Their loan products tend to have fewer hidden fees than big bank offerings. I reviewed a personal loan application where the APR was clearly quoted with no origination fee, which is unusual. Many larger lenders charge 1 to 5 percent upfront just to process the loan. St. Louis Community Credit Union typically does not do this, which effectively lowers your cost of borrowing. That said, their rates are not always the absolute lowest in the market. If you have excellent credit and you're shopping for an auto loan, you might find a better rate at a direct lender or an online credit union with a larger scale. But the difference is usually marginal, maybe a quarter point or so, and the local relationship aspect often compensates for it.
Practical Limitations to Keep in Mind
Not every product is available everywhere. Their digital offering is solid for standard transactions, but if you need specialty services like international wire transfers, investment management, or business banking with advanced treasury tools, you'll probably outgrow them. They have basic business checking, but it's entry-level. If you run a business with payroll complexity or multi-entity accounting, a traditional bank or fintech solution might serve you better. ATM access is another realistic constraint. They participate in the CO-OP network, which gives you thousands of surcharge-free ATMs across the country. But if you live in an area where that network isn't well-represented, you might end up paying out-of-network fees anyway. It's worth checking the CO-OP locator before you commit if you travel frequently or live in a rural area. Their branch footprint is limited to Missouri. If you need in-person service while traveling or after relocating, you're out of luck. This is a common credit union limitation, not unique to them, but it's worth factoring in if your life involves frequent moving or remote work in other states.
Customer service quality varies by branch and time of day. During peak hours, wait times can stretch to 20 or 30 minutes on the phone. In person, some branches can be slow on Fridays. I learned this the hard way when I needed to deposit a check right before a bill due date and the local branch was running understaffed. Their phone support eventually routed me to a representative who processed everything quickly, but the initial hold time was frustrating. If timing matters, call midweek midmorning or go in person on a Tuesday.

When It Makes Sense and When It Doesn't
St. Louis Community Credit Union works well for everyday banking if you value lower fees, competitive savings rates, and straightforward loan terms. The lack of origination fees on loans alone is worth considering if you're in the market for financing. Their checking accounts don't carry monthly maintenance fees as long as you meet the typical direct deposit or minimum balance requirement, which removes a common pain point from big bank accounts. It falls short if you need extensive business banking tools, international services, or nationwide branch access. You also need to be comfortable managing potential dividend fluctuations and working through occasional technical hiccups in their digital platform. These are real constraints, not hypothetical concerns. People who don't research them tend to get surprised later. For most individuals and families in the St. Louis area looking for a reliable primary banking relationship, this credit union is a practical choice. It's not flashy, it's not perfect, but it does the core banking functions well and charges less for them than most alternatives. That's usually what matters in the long run.