What Sparkasse Actually Is
Most people in Germany use Sparkasse without really understanding what it is. It is a network of publicly owned local banks, not a single corporation. EachStadt or district has its own Sparkasse with separate management, slightly different fees, and varying levels of service quality. The brand is unified, but the reality on the ground depends entirely on which branch you are dealing with. The term "local banking excellence" sounds like marketing copy, but there is something practical underneath it. Sparkasse branches are everywhere, even in towns where Deutsche Bank and Commerzbank have completely closed their doors. You can walk into a Sparkasse in a village with fewer than 2,000 residents and actually speak to a human being who knows your name. That does not happen with the big private banks anymore. Here is how the system works when you actually need to use it. You open an account at your local Sparkasse, which means you walk into a branch with your passport or ID card and proof of address. They will ask what type of account you want, usually a Girokonto for everyday transactions. You fill out paperwork, sign a few things, and within two weeks your EC-Karte and PIN arrive in the mail. Simple enough, but the complications start once you are actually inside the system.
I had a situation a few years back where I needed to set up a standing order for a utility company that only accepted SEPA direct debit from certain banks. My local Sparkasse kept rejecting the setup because the creditor ID format did not match their internal validation rules. The online banking interface would not let me proceed, and the branch staff initially told me it was impossible. After about twenty minutes of me pushing back and asking to speak with someone who understood SEPA compliance rather than just reading from a script, they found a workaround: they processed it manually through the backend system instead of the standard online form. This took about ten minutes once you got past the initial resistance. The lesson here is that Sparkasse staff vary enormously in competence depending on which branch you visit and who happens to be on shift.
Online Banking and the Sparkasse App
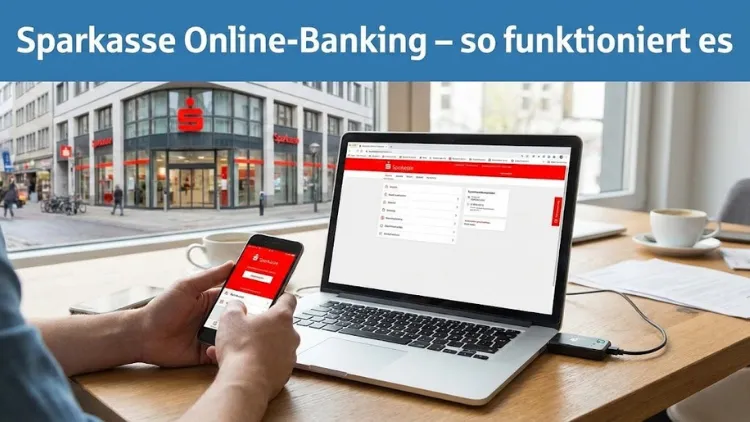
The online banking platform is called smartCash or mySPK depending on which region you are in. The apps themselves are functional but not particularly elegant. Transaction history loads slowly, the interface feels cluttered, and search functionality is basically nonexistent. If you need to find a specific payment from six months ago, expect to spend five to ten minutes scrolling through pages of transactions. For most daily banking tasks, the apps handle transfers, balance checks, and card blocking adequately. Setting up recurring payments works fine once you figure out which menu item actually does it, since the options are buried under several layers of navigation. Bill Pay, the feature that lets you upload PDF invoices and have the bank process them automatically, is genuinely useful if you have a lot of bills to pay each month. It cuts down monthly admin time significantly, probably from an hour to fifteen minutes if you batch everything together. The catch is that Sparkasse's online infrastructure is not built for power users. There is no API access, no bulk transaction tools, and spreadsheet import is limited compared to what newer digital banks offer. If you are managing finances for a small business or have complex investment needs, you will hit walls pretty quickly. The interface assumes you are a regular person with a salary account and a savings plan, nothing more complicated than that.
Get the Full Details
Fees and Pricing Structure
Sparkasse pricing varies by location, which is one of those things that drives people crazy. Your local Sparkasse sets its own fee schedule within broad guidelines from the cooperative umbrella organization. One Sparkasse might charge zero monthly fees for basic accounts while the one twenty kilometers away charges eight euros per month for the same product. You need to check the current fee schedule, known as the Preis- und Leistungsverzeichnis, before opening an account. It is usually available on the branch website or by request. The standard model involves a monthly basic fee, charges per cash withdrawal at non-Sparkasse ATMs, and fees for certain paper statements or branch services. Some regions offer account packages that bundle checking and savings with discounts on other products like credit cards or insurance. Whether these bundles actually save you money depends on whether you use all the included features. Most people do not. ATM access is where Sparkasse has a genuine advantage. Their network of girocard-compatible machines is extensive, and withdrawals at your own bank's ATMs are typically free. Withdrawals at other banks' machines usually cost between one and two euros depending on your region. This matters more if you rely heavily on cash, which a surprising number of Germans still do despite the push toward contactless payment.
Customer Service Realities
Phone support exists but getting through to a human can be tedious. The automated menus are standard German bank fare, and wait times during business hours range from five minutes on a quiet Tuesday afternoon to thirty minutes on a Monday morning. Branch appointments are increasingly necessary for anything beyond basic transactions. Walk-in service is available at larger branches but you will likely wait twenty to forty minutes, sometimes longer during peak periods like pension payment days at the end of the month. The people who work in branches are generally competent but overworked. Staff turnover is moderate, and training quality varies. I once dealt with a teller who processed a block on my debit card as a cancellation instead, which meant I had to call customer service and then visit the branch again to get it reissued. That cost me roughly three hours spread across two days. The same issue resolved itself in ten minutes at a different branch with a more experienced teller. The product is the same, the backend systems are identical, but the human variable creates enormous differences in experience.
When Sparkasse Makes Sense and When It Does Not
Sparkasse is a solid choice if you value physical branch access, do not need advanced digital banking features, and want a bank that will not disappear from your town due to corporate restructuring. The public mandate means they serve rural and small-town populations that private banks have abandoned. This is not an accident, it is the design. It is a poor choice if you are a frequent traveler who wants no foreign ATM fees, a tech-forward user who expects seamless mobile experiences, or someone who manages investment portfolios and needs sophisticated trading tools. For those cases, a direct bank like ING or Consorsbank or a neobank like N26 or Vivid will serve you better. Sparkasse is not competing in those segments and should not be judged by those standards. The hybrid approach that many people end up using is keeping a Sparkasse account for local transactions and branch access while moving most of their money to a higher-yield savings account elsewhere. Some Sparkassen offer decent interest rates on sparkassenSparen accounts, but the rates are usually below what online-only competitors pay. The difference is small on modest balances but adds up over time.
There is also the question of security culture. Sparkasse uses the girocard system primarily, which is German-specific and less internationally versatile than Visa or Mastercard. If you need a card that works reliably abroad, you will likely get a Visa or Mastercard co-branded card anyway, which may come with additional fees depending on your region. The core Girokonto remains solid for domestic use, and that is what most customers actually need day to day. Opening an account requires a brief visit to the branch with identification, though some regions now allow preliminary online applications that still require an in-person finalization. Processing takes one to two weeks for card delivery, and activating the online banking credentials usually happens simultaneously via post. Everything arrives in a single package with your card, PIN mail, and TAN method, whether that is photoTAN or smart TAN depending on your region's current system. The overall picture is of a bank that is reliable, ubiquitous, and adequately functional for standard personal banking. It is not exciting, it is not cheap everywhere, and it is not optimized for anyone who finds traditional banking cumbersome. But for the segment of the population that simply wants a local bank they can walk into, it remains the default choice for a reason. The alternatives have their own problems, and Sparkasse has not lost its position by accident.