How Toyota Financing Actually Works in Practice
I have been working in the automotive finance space for a long time, long enough to see the same questions come up month after month. People want seamless car ownership. They want the paperwork done right, the rates to make sense, and the whole process to not feel like pulling teeth. Toyota Finance handles millions of accounts, and they have systems in place that generally work well. They are not perfect. Nothing in this industry is. This guide covers what Toyota financing actually involves from the point of view of someone who has dealt with the backend of these transactions. Not the showroom sales pitch. The real process. The most common mistake I see is people walking into a dealership without knowing what rate they qualify for. They sit at the desk, negotiate the vehicle price, and then get hit with a financing rate that is higher than what they could have locked in beforehand. It costs you nothing to get pre-approved through Toyota Financial Services before you even look at a car. You submit a soft credit inquiry, get a rate range, and walk in with leverage. The deal structure changes completely when you already know your numbers.
I had a client once who was trying to refinance a used Camry. The dealer wanted to run a hard pull first, then offer them a subprime rate because their credit had taken a small hit from a recent credit card application. We pulled the Toyota Finance pre-approval first. The rate came back nearly four points lower than the dealer's backup offer. It was not even close. The lesson here is straightforward: your pre-approval is a contract, not a suggestion. Use it before anything else.
Understanding the Actual Loan Structure
Toyota Finance offers several product types. The standard retail installment contract is the most common. You pick a term, usually between thirty-six and seventy-two months, and the rate is fixed for the life of the loan. There are also lease options through Toyota Motor Credit, which is the leasing arm. Then there are specialty programs like Toyota Special Finance rates, which tend to be promotional and require good to excellent credit to qualify. Here is something most people do not realize: the monthly payment you see quoted is not always the total cost. Toyota occasionally bundles things like extended warranties, VIN-etched glass packages, and gap insurance into the financed amount. These are profit centers for the dealership. They are legal. They are also often unnecessary if you already have adequate insurance coverage. I have seen finance amounts inflated by two to three thousand dollars simply because the salesperson ran the numbers with add-ons included before showing the base payment. Always ask for a breakdown of every line item on the gross profit worksheet before you sign anything.
Get the Full Details
The Payoff and Refinancing Question
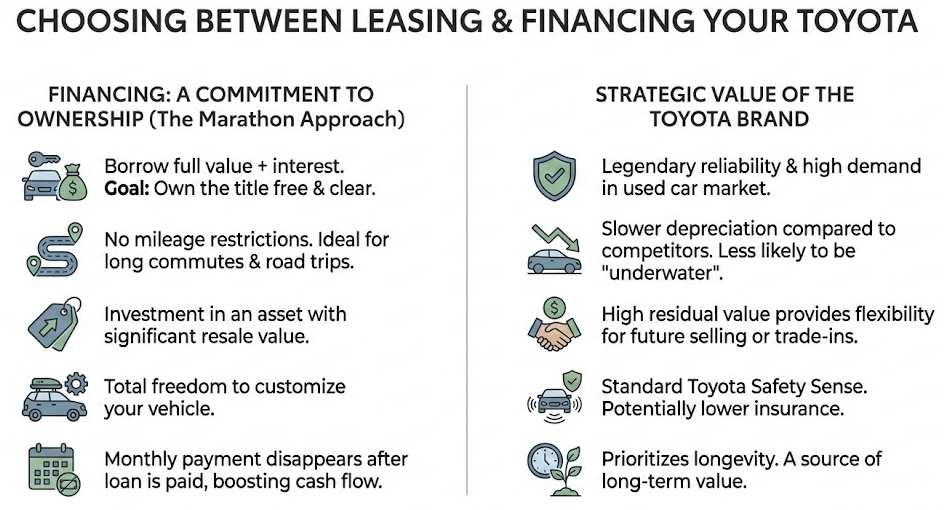
People assume Toyota Finance has no prepayment penalty. In most cases, that is true. Their standard contracts allow early payoff at any time with no fee. But the math behind refinancing is where things get tricky. If you are in the first twelve months of a loan, refinancing rarely makes financial sense. You will pay closing costs or lender fees that outweigh the interest savings unless your credit profile has improved dramatically. I usually tell people to wait until they have at least eighteen months of payments under their belt and a credit score increase of thirty points or more before even looking at refinancing options. One edge case I dealt with recently involved a customer whose vehicle was totaled in an accident. The insurance company cut the check payable to both the owner and Toyota Finance. The payout did not fully cover the remaining loan balance because depreciation had eaten into the equity. This is where gap insurance matters. Without it, the owner was still on the hook for roughly eleven hundred dollars. With it, that balance disappeared. If you are financing or leasing, gap coverage is not optional advice. It is a protective measure that pays for itself in exactly one scenario and does nothing in a hundred other scenarios. That is how insurance works.
Managing Your Account After the Sale
Once the deal is done, you get access to the Toyota Finance online portal. It is functional but not particularly intuitive. You can set up automatic payments, view your payoff quote, request a payoff statement, and update your address or insurance information. The portal also lets you download your year-end tax documents, which is useful if you are financing a vehicle for business purposes. A practical tip that most people miss: you can request a payoff quote directly from the portal at any time. Some dealerships will give you a payoff number over the phone, but the automated system gives you a more accurate figure because it accounts for daily accrual. If you are shopping for a refinance or preparing to sell the vehicle, pull that number yourself from the portal rather than relying on a third party to give you an estimate.
What Happens When Things Go Wrong
Not every experience is smooth. Payment processing errors do happen. A missed autopay posting, a bank transfer that fails on the due date, a billing cycle that runs longer than expected. Toyota Finance generally has a grace period of about ten days before they report a late payment to the credit bureaus, but that is not written in stone and varies by contract. If you know a payment will be late, call them before the due date. An active communication record is better than a silent missed payment on your credit report. I had a situation where a customer's payment was applied to the wrong account due to a data entry error by the dealership during the funding process. It took four weeks and three separate calls to Toyota Finance's customer service line to resolve. The workaround was filing a formal dispute through their online portal, which triggered an investigation. The funds were returned to the correct account within ten business days of the dispute submission, but you lose five weeks of your life dealing with it. Keep every confirmation email, every reference number, and every date you called. It makes the resolution process significantly faster.
Common Pitfalls to Avoid
Down payment requirements vary by credit tier. If your score is below six hundred, expect to put down at least ten percent. Some promotions require zero down, but those rates come with shorter terms or higher monthly payments that offset the benefit. Rolling negative equity from a trade-in into a new Toyota Finance loan is another trap. You end up owing more than the vehicle is worth, and if the car is totaled, you are in the gap insurance scenario I described above. It is a cycle that is hard to break out of. The warranty package is another area where buyers overspend. The basic Toyota warranty covers the vehicle for thirty-six months or thirty-six thousand miles on new cars. The extended service contract they push at the desk is convenient but expensive. You can often find the same coverage through third-party providers at a lower cost, though you lose the convenience of handling claims through the dealership network. It is a tradeoff between price and ease of service.
The Bottom Line on Seamless Ownership
Seamless car ownership through Toyota Finance is achievable if you go in prepared. Get pre-approved first. Know your rate before the dealer mentions it. Read every line on the contract. Request payoff quotes directly from the portal. Keep your payment records organized. These steps remove the friction that most people complain about. The system works well when you understand how it works. It falls apart when you let the dealership handle everything without your own verification.