Stress Testing Financial Systems When Everything Is Moving
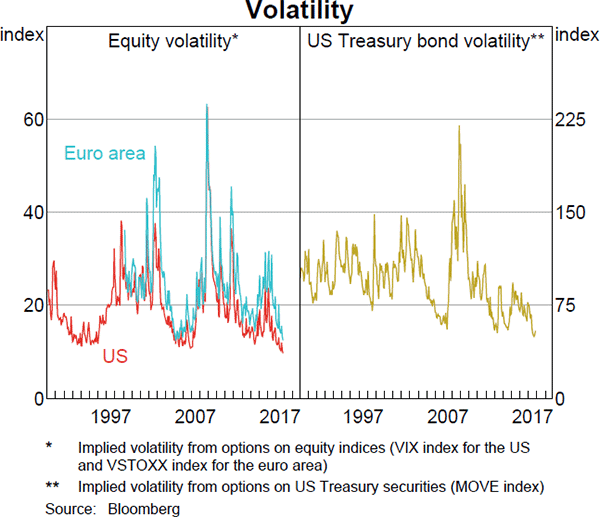
The last couple years have made it obvious that traditional stability metrics don't capture what actually happens when volatility spikes across multiple asset classes at once. I spent most of 2022 watching banks and hedge funds run their models and find that the numbers looked fine on paper while real positions dissolved in two days. That gap between theoretical solvency and actual liquidity is where most of these conversations end up anyway. The core idea isn't especially new. You take a portfolio, you introduce controlled disturbances, and you measure what breaks first. The trick is making the disturbances realistic enough to matter. Most people run historical simulations using 2008 or 2020 data. Those work for directional risk but they miss the compounding effects you see when correlation structures shift mid-event. I learned that the hard way during a repo market stress episode in March 2020. My initial model showed manageable haircuts across the book. It didn't account for the fact that when everyone is selling simultaneously, the collateral you thought was liquid becomes unusable because no one will take it. The workaround was running a synthetic stress scenario where I forced correlation coefficients between asset classes to converge toward 0.9 across a rolling 5-day window. That's when the real margin calls appeared on the spreadsheet. There's a reason practitioners don't just plug in a volatility parameter and call it a day. Market volatility doesn't arrive as a single number. It arrives as a sequence. First you get elevated realized volatility in equities. Then credit spreads widen. Then funding markets start pricing in tail risk through repo rates and commercial paper spreads. Then counterparty credit assessment changes. Each layer compounds the last. A static model that looks at one slice of that chain will tell you the system is stable. A dynamic model that links those slices together will tell you something different. The difference matters when you're deciding whether to hold or to raise cash.
One thing beginners consistently miss is that volatility testing isn't about predicting the future. It's about identifying which exposures become fragile under certain conditions. The output should be a map of failure modes, not a probability score. I've seen firms treat a VaR number like it was a verdict. It isn't. It's a single point estimate from a distribution that assumes normality. Markets don't cooperate with that assumption when they're stressed. Another counter-intuitive point: higher volatility doesn't always mean more risk in the short term. Sometimes volatility compressions are the dangerous part. When markets go quiet for weeks or months, leverage builds up invisibly. Positions get crowded. The system looks solid because nobody is testing it. Then something happens. The 2010 flash crash and the 2021 bond market selloff both had that pattern. Quiet first, then instantaneous repricing across dozens of instruments. The volatility spike at the end was the symptom, not the cause. When I run these tests now, I use a combination of historical scenario overlays, Monte Carlo simulations with correlated shock paths, and manual gap analysis for illiquid positions. The process takes about a week for a mid-size book if you're doing it properly. Automated tools can do it faster but they tend to smooth over the edges that actually matter. I keep a manual layer on top specifically for that reason. It catches the things the models can't express in numbers.
Limitations exist and they're significant. Stress testing assumes you can define the scenarios you're worried about. You can't. Black swan events are black swans for a reason. The 2020 pandemic wasn't in anyone's historical dataset. Climate-related financial shocks aren't modeled in traditional frameworks. Geopolitical events don't fit in correlation matrices. So you test what you can and accept that the gaps will matter when they matter. The alternative is doing nothing and pretending your model is complete, which is worse. If you're looking to build this out, start with a clean balance sheet and trace each line item through a series of shocks. Interest rate changes. Credit spread moves. Equity declines. FX swings. Then layer them together in sequences that reflect how crises actually propagate. Funding gets tight first. Then collateral values drop. Then counterparty risk rises. Then fire sales begin. That's the order. Models that skip steps tend to underestimate the damage. There are open-source frameworks you can build on. Some people use R packages like stressTesting or PerformanceAnalytics. Others write custom Python scripts with numpy and scipy. I prefer a hybrid approach where the back-end calculations are scripted but the scenario design happens in a structured spreadsheet so the logic is visible and auditable. That's mostly because when you present this to someone who isn't a quant, they need to see where the numbers come from. Black box answers don't convince risk committees.
Get the Full Details

The broader point is that global financial stability isn't a single metric you can track on a dashboard. It's a network of interdependent relationships. When volatility hits one node, the rest feel it through funding channels, collateral chains, and counterparty exposure. The testing process is just a way to make those connections visible before they become problems. It won't prevent a crisis. It will at least tell you where you'd be standing when one arrives.