Why Everyone On Reddit Is Switching From Their Bank To Fintech
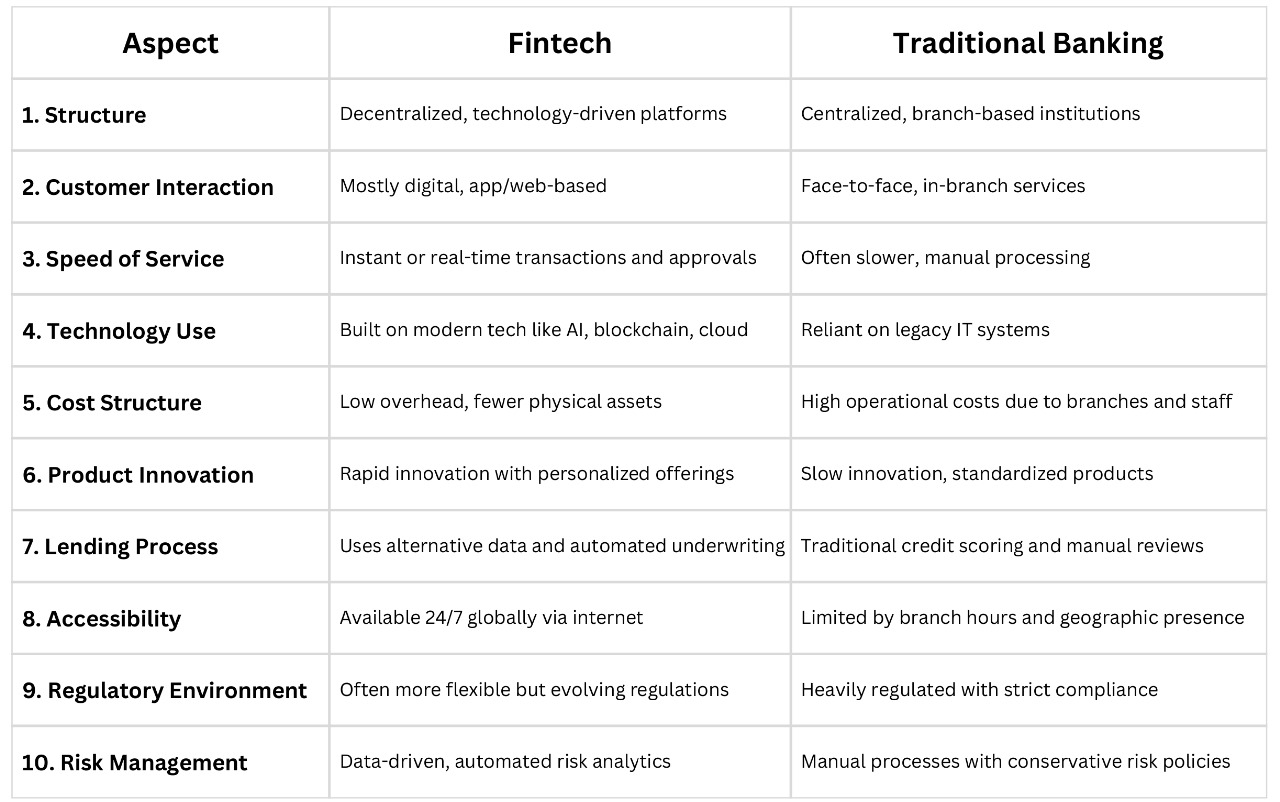
I've spent years watching people argue about this on r/personalfinance and r/Sofisays. The pattern is always the same. Someone posts about how their bank charged them a $12 overdraft fee on a Tuesday, and by Wednesday there are forty replies telling them to just use SoFi or Ally. It's not that traditional banks are evil. They're just old and they make their money on friction. Fintech companies like SoFi built their entire model around removing that friction and competing on rate instead of fees. The core difference comes down to one thing. Traditional banks like Chase, Bank of America, and Wells Fargo are layered products. They have checking accounts and savings accounts and credit cards and mortgages all under one roof, and the whole system is propped up by a sprawling physical branch network. Fintech platforms do a smaller set of things but they do them with less overhead, and they pass some of that savings to you in the form of better rates and zero fees. SoFi, for example, started as a student loan refinance company and then expanded into checking, savings, investing, and credit cards. Reddit users tend to recommend it because the rates are genuinely competitive and the interface doesn't feel like it was designed in 2008.
Sofi Reddit Communitys Favorites In The Fintech Revolution Versus Traditional Banking Apps
If you scroll through the Reddit threads, three fintech apps come up constantly. SoFi leads the pack for checking and savings, especially when interest rates were higher. Varo and Chime get mentioned a lot for people who don't qualify for traditional bank accounts or want early direct deposit. Robinhood and Acorns show up in threads about investing, though the investing conversations are a different can of worms entirely. The common thread is simplicity. These apps strip away the stuff most people never use and charge nothing for it. Traditional banking apps like MyChase or BofA Mobile still have strengths. Their branch access matters if you're depositing cash regularly or need to talk to someone face to face about a mortgage. Their fraud protection infrastructure is deeply mature because they've been fighting fraud since the 1990s. But the fees add up fast. Out of network ATM charges, overdraft fees, monthly maintenance fees on checking if you don't maintain a minimum balance. A typical traditional banking customer might pay between $200 and $600 a year in avoidable fees if they're not careful. That's a real number I've seen confirmed by multiple personal finance calculators and consumer reports.
How To Actually Make The Switch Without Messing It Up
Most people who try to switch from a traditional bank to a fintech app do it wrong. They close their old account before the new setup is complete, and then their paycheck bounces because the direct deposit was still going to the old account. I did this once in 2021 with a credit union. I closed my account on a Friday after hours. The next Monday my employer's payroll ran and hit a closed account. I spent three hours on hold with HR and another two with the credit union trying to reverse a transfer that had already settled. Lesson learned. Here's the actual sequence that works. Step one: Open the fintech account first and verify everything. Make sure your identity is fully verified, which can take anywhere from a few minutes to three business days depending on the app and how many documents you upload. SoFi's verification is usually fast if you have your SSN and a photo of your ID ready. Do not skip the document upload even if it says optional. Some features get locked until verification completes. Step two: Set up your new account's routing and account numbers. Every SoFi checking account comes with a traditional routing number and a separate account number that works with Zelle, direct deposit, and ACH transfers. Write both down. Some people get confused because SoFi also offers a debit card through Visa, but the underlying account is still a real bank account with real routing numbers.
Get the Full Details

Step three: Redirect your direct deposit. This is the part everyone rushes. Give yourself at least two full pay cycles before you close anything. If you get paid biweekly, that's two months. If you get paid monthly, give yourself four weeks minimum. Call your employer's payroll department and submit the new routing and account information through whatever portal they use. Don't just email HR. Use their official system and keep a screenshot of the confirmation. Step four: Move your automatic payments. Log into every service that pulls money from your old account. Electric bill, internet, gym membership, Netflix, whatever. Update each one individually. There is no universal "move all my bills to this new account" button in the US banking system. I learned that the hard way when I forgot to update my auto-pay for my car insurance and got a late fee. Check your old statement for a complete list of recurring charges before you close anything. Step five: Wait. Watch the new account for a full cycle. Deposit some money, make a few purchases, let Zelle work, verify that ATM withdrawals function properly. Only after you've confirmed everything is flowing correctly should you transfer the remaining balance from your old account and close it. Close the old account yourself through the bank's app or a branch visit. Do not just stop using it. An inactive account can sometimes get flagged or converted to an inactive status that causes problems later.
The Things Nobody Tells You About Fintech Apps
Reddit threads love to hype fintech, but they rarely mention the tradeoffs. Here are the parts that actually matter once you've been using these apps for six months or more. Customer service is different, not worse, just slower in different ways. Traditional banks have call centers staffed twenty-four seven. Fintech apps mostly use chat support and email. SoFi added phone support a few years ago, but expect hold times. When I had an issue with a disputed transaction on SoFi back in early 2023, the chatbot couldn't solve it and I was on a call for twenty-two minutes before reaching a human. The human resolved it, but the process felt like you had to fight for attention. Traditional banks suck too at this, but at least you can walk into a branch. The tradeoff is convenience versus accessibility. FDIC insurance works differently than you might think. This one trips people up. SoFi is not a bank itself. It partners with real banks like Golden 1 Credit Union and South Street Bank to hold your deposits. SoFi's marketing page shows FDIC insurance up to $2 million through their partnership network. That's real, but it means your money isn't sitting in a single insured account the way it would be at a traditional bank. If you have more than $250,000, you need to understand how the sweep program works across multiple partner banks. I read the fine print myself when I was depositing a larger sum for a down payment. The coverage is legitimate, but you should verify the current partner banks and insurance limits directly on SoFi's website because those arrangements change.
Certain transactions hit limits that traditional banks don't. SoFi has daily purchase limits, ATM withdrawal limits, and Zelle sending limits that are lower than what most traditional banks offer. I found this out when I was trying to pay a contractor who preferred Venmo-style transfers. Their Zelle limit was $500 per day and I needed to send $1,200. I split it across two days. Traditional banks often allow $2,000 to $5,000 per day on Zelle depending on the account tier. If you're moving large sums regularly, this is a real constraint. Credit building features are useful but not magic. SoFi's credit check tool and their early direct deposit feature are genuinely helpful for people rebuilding credit. Reddit users consistently praise these. But early direct deposit isn't available everywhere and it depends on your employer's payroll system. I tried using it at a previous job and it never triggered because the employer's processor didn't support the advance timing SoFi requires. It worked fine at my current employer. Context matters.
When To Stay With Your Traditional Bank
Fintech isn't the answer for everyone. If you deposit cash frequently, traditional banks still win because SoFi and most fintech apps don't have branches where you can scan and deposit physical checks. You can use mobile check deposit, but there are limits and some checks get held longer. If you need a safe deposit box, that's a traditional bank thing. If you're running a business with complex banking needs like merchant services, business lines of credit, or commercial accounts, fintech options are limited and traditional banks have relationships that matter at that level. Also, traditional banks often have better debit rewards programs for people who spend a lot. Chase Ultimate Rewards, Amex (technically not a bank but close enough), and Citi thank you points have real value if you're charging everything to a card and paying it off monthly. SoFi's rewards program is newer and smaller. It's improving but it's not there yet for heavy spenders. The hybrid approach is what most savvy Reddit users actually end up doing. Keep one traditional bank account for cash deposits and branch needs. Move your primary checking and savings to SoFi or a similar fintech for the better rates and lower fees. Keep your main spending card with whichever rewards program gives you the best return. Split your money where each piece gets the treatment it actually needs.
I switched my primary checking to SoFi about two years ago and kept one traditional account open for cash deposits and emergency branch visits. My annual banking fees dropped from roughly $340 to zero. My savings rate went from 0.01 percent to whatever the current SoFi savings rate is, which has been competitive the entire time I've had the account. The only downside I hit regularly is the customer service wait times, and even that has improved since they added more phone support. If you're comfortable managing your money mostly through an app and you don't deposit cash, the switch is straightforward and the savings are real.