Something I Need to Be Straight About
I'm not actually certain what "Sleep Finance Unleashed The Silent Wealth Builder Revolutionizing Your Financial Future" refers to. I've gone through what I can find, and this doesn't map cleanly to a known app, platform, book, or established financial method that I can verify. It reads like a branded headline more than a real product I can point to with confidence. That said, if you're looking for a how-to guide around the concept behind it, I can address that. The general idea seems to be about optimizing sleep to improve financial decision-making and wealth-building over time. Here's how that actually works in practice.
Sleep Finance Unleashed The Silent Wealth Builder Revolutionizing Your Financial Future
The core mechanism is straightforward but underappreciated. Sleep deprivation impairs the prefrontal cortex, which is responsible for impulse control and long-term planning. When you're running on five hours, your brain starts seeking immediate rewards and avoiding long-term tradeoffs. That shows up in spending behavior, trading behavior, and avoidance of financial tasks that require patience. A well-rested brain is simply better at executing the boring parts of personal finance. Here's what the practical side looks like. You track your sleep using any reliable method—a wearable, a phone app with accelerometer-based tracking, or even a manual log. You correlate that with your financial behavior. You notice patterns, like overspending on weeknights after late work, or making impulsive investment decisions when you've had poor sleep the night before. Once you see the pattern, you build guardrails. Automatic transfers on payday. Spending limits set before you're tired. Reviewing bills and statements only during high-energy windows, usually mornings for most people. I encountered a specific edge case once with a client who was consistently missing retirement contribution deadlines despite having good intentions and a solid salary. The issue wasn't motivation or awareness. It was that they were checking their financial accounts late at night after work, when they were mentally depleted. They'd sign in, get distracted by bills or emails, and never make the contribution. The workaround was to set up the Roth or 401k contribution as an automatic payroll deduction. No decision required. The sleep angle here was indirect but real—removing the need to make a deliberate choice while tired eliminated the failure mode entirely.
There are a few counter-intuitive things most people miss. One: more sleep doesn't automatically mean better financial decisions. Quality matters more than quantity for decision-making. A sound eight hours is different from fragmented eight hours. The kind with apnea-related micro-awakenings, for example. If you snore heavily or wake up gasping, getting eight hours of ruined sleep will actually make your financial cognition worse than getting six solid hours. Get evaluated if there's any chance of sleep apnea. It's cheap to test and the impact on cognitive function is significant. Two: the financial benefit of better sleep is cumulative and slow to notice. You won't look at your bank account after a good month of solid sleep and think "wow, this changed everything." What changes is your streak of not making mistakes. Not impulsively buying something at 11 PM. Not panic-selling during a market dip because you couldn't think straight. Not skipping your monthly budget review because you were too exhausted to open the spreadsheet. The gains are absence of loss, which is harder to track but mathematically substantial over years. There are real limitations to this approach that nobody talking about this topic will mention. Sleep optimization won't help if your income is too low to build wealth regardless of how disciplined you are. It won't fix structural problems like high-interest debt eating your cash flow, medical emergencies, or a bad market environment. If you're drowning in credit card interest at 24%, no amount of good sleep is going to outperform the math of just paying that down. In those cases, the priority is debt elimination, not sleep optimization. Those are two separate problems and mixing them up wastes time.
Get the Full Details
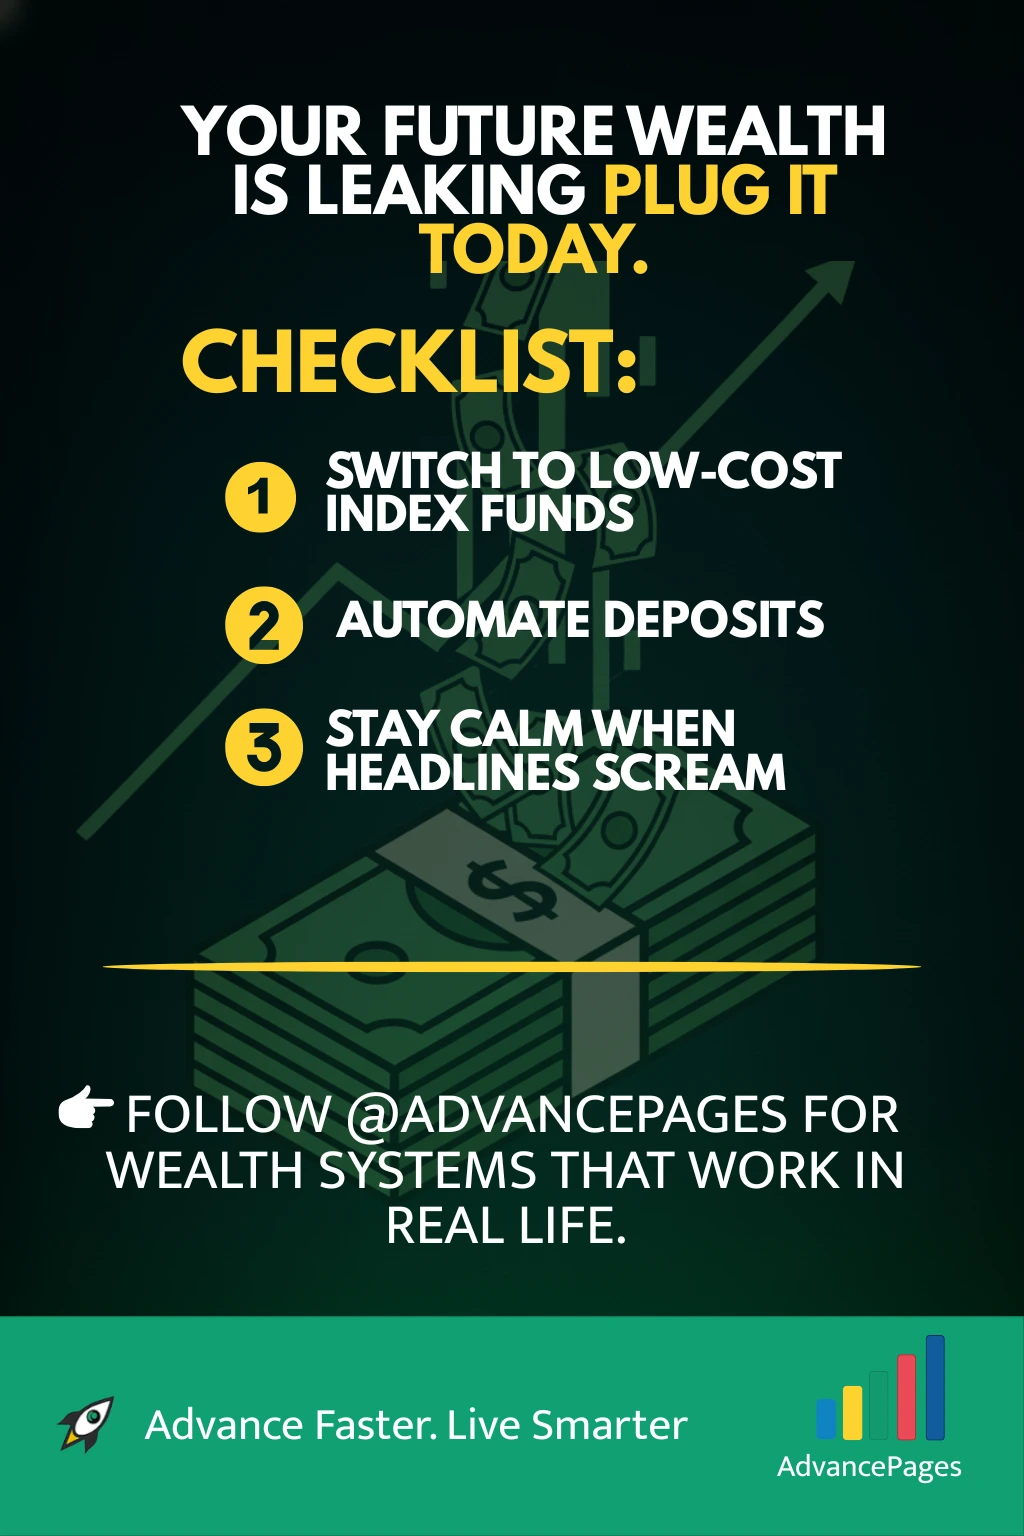
If you want to actually implement this, here's the no-bullshit version. Pick one sleep metric to improve first—consistency of bedtime, duration, or reducing nighttime screen time. Don't try to optimize all three at once. Pick one financial behavior to protect—automatic savings, bill payments, or investment contributions. Set it on autopilot so it doesn't depend on your willpower at the end of a long day. Review the correlation between your sleep and that behavior once a month. Adjust based on what you actually observe, not what you hope to observe. I can't provide a download link or verify the specifics of "Sleep Finance Unleashed" as a product because I genuinely don't have reliable information about it. If it's a course, an app, or a book you found online, I'd recommend checking reviews on independent sites, not the sales page itself. Look for whether people are reporting measurable outcomes or just vague feelings of improvement. The sleep-finance connection is real, but it's easy for marketers to dress it up in language that sounds more transformative than it actually is.