Understanding How Property Assessment Actually Works in Sioux City
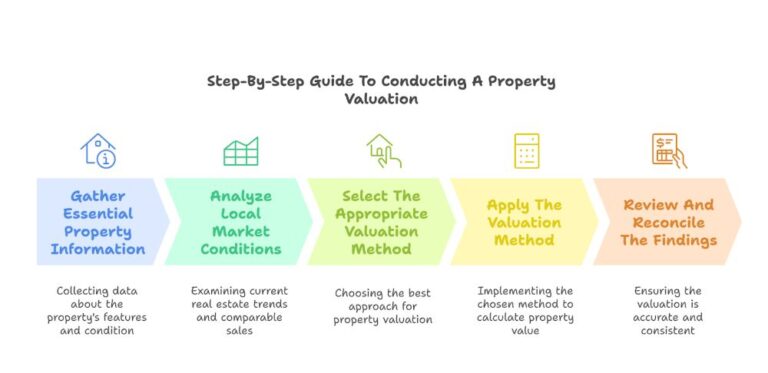
Property assessment in Sioux City runs through the Woodbury County Assessor's office, and the process is straightforward if you know where to look. The assessor determines market value for all real property in the county using sales comparison, cost, and income approaches depending on property type. Residential properties typically use the sales comparison approach, which looks at what similar homes sold for in your neighborhood over the past year. Commercial properties often get evaluated using the income capitalization method, which factors in rental revenue and vacancy rates rather than just comparable sales. Once the assessed value is established, it gets multiplied by the state-mandated assessment ratio to arrive at the taxable value. Iowa uses a uniform assessment percentage that applies across all property classes, so the assessor's role is specifically to estimate fair market value. The tax rate itself is determined separately by each taxing authority — school districts, city government, county operations, and special districts all set their own rates independently of the assessor's office. That separation matters because people frequently blame the assessor for high taxes when the actual tax rate increase came from a school board vote or a special assessment district expansion.
Sioux City Assessor Your Complete Guide To Property Valuation And Tax Facts
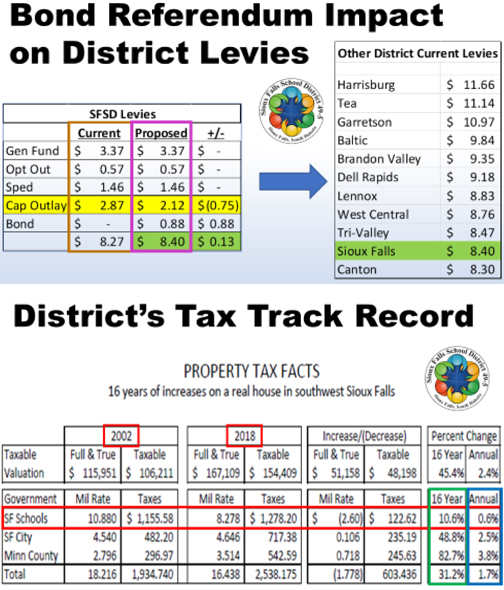
I've walked through this process with property owners enough times to know where confusion sets in. The biggest misunderstanding I encounter involves the difference between assessed value and taxable value. When you receive your notice, the number listed as your assessed value is not the same as the amount your property taxes are calculated against. The assessment ratio in Iowa has changed over the years, and it differs between residential, agricultural, and commercial classifications. Your tax bill breaks these out separately, but the notice from the assessor shows the raw market value estimate before any ratio is applied. If you're comparing your previous year's assessment to this year's without accounting for ratio changes, you'll draw the wrong conclusion about whether your property was undervalued or overvalued. The appeal process is another area where people waste time. You have a 60-day window from the date on your assessment notice to file an appeal with the Woodbury County Board of Review. Missing that deadline means you're locked into the current year's assessment, and there is no exception for forgetting or moving out of state. I once had a property owner who tried to appeal after a 72-day delay because she assumed the date on the notice was flexible. It wasn't. She ended up hiring a consultant for the next cycle and learned to track the calendar religiously. One practical detail most guides overlook is how exemptions interact with assessed value. Veterans' exemptions, homestead exemptions for senior citizens, and disability exemptions all reduce the taxable value but do not change the assessor's estimated market value. When you see your assessed value hasn't changed but your tax bill went down, it's usually an exemption taking effect at the county auditor level, not a revaluation. Conversely, if your assessment drops but your taxes increase, the likely explanation is a tax rate shift from a nearby municipal election or school bond measure rather than anything the assessor controls.
There is also a common misconception that challenging your assessment will automatically lower your taxes by the full amount of the reduction. That is not how it works. If your assessed value is lowered by ten thousand dollars and your effective tax rate is roughly two percent, you save two hundred dollars annually, not ten thousand. The savings are proportional to the rate applied by all taxing jurisdictions combined. Some property owners appeal hoping for a dramatic reduction and are disappointed when the math doesn't match their expectations. Understanding the rate application early prevents that frustration. Accessing records is relatively simple. The Woodbury County Assessor maintains an online search tool where you can look up parcels by address or parcel number. The data includes land value, improvement value, total assessed value, and classification. What the online system does not always show clearly is the breakdown between land and building values for older properties, particularly in cases where additions or remodels were permitted but not properly flagged in the assessor's database. I ran into this myself when researching a property on the west side of Sioux City. The improvement value seemed flat for roughly fifteen years despite documented kitchen and bath remodels. A call to the assessor's desk revealed the permits had been pulled but never updated in the record. Correcting that took about three weeks and resulted in a meaningful reassessment. The moral is that the data you see online is only as current as the last field update, and discrepancies are worth investigating before accepting them at face value. Agricultural land assessment follows a different framework altogether. Iowa's use-value assessment program values farmland based on its productivity and soil quality rather than market speculation. This can create situations where a parcel's agricultural assessed value is dramatically lower than its potential market value if rezoned or developed. Property owners who inherit farmland sometimes panic when they see the low assessment and assume something is wrong. It is not wrong, but it does mean that converting the land to residential or commercial use will trigger a significant reassessment and potentially affect property taxes substantially. Planning ahead for that transition avoids surprise spikes at closing.
Get the Full Details
When to Appeal and When to Let It Go
Appealing an assessment makes sense when you have concrete evidence that the valuer misidentified comparable sales, made a calculation error, or assigned an incorrect classification. It does not make sense when your only argument is that your taxes feel too high. The Board of Review does not consider affordability or tax burden as grounds for reduction. They review whether the assessed value accurately reflects fair market value as of the valuation date. If your home sold recently for less than the assessed value, that sale price carries significant weight in your favor. If you have not sold and lack recent comparable transactions, your chances of success drop considerably regardless of how convinced you are the value is wrong. The appeal hearing itself is informal compared to a courtroom proceeding. You present your evidence, the assessor's representative presents theirs, and the Board of Review issues a written decision. Bringing photocopies of three to five comparable sales within the last six months is standard practice. Listing prices alone are less persuasive than closed sales because listing prices reflect seller expectations, not market reality. Adjustments for square footage, age, condition, and location should be documented rather than implied. The board expects you to show your work. If your appeal is denied, you can further appeal to the county district court within thirty days. This step introduces legal procedure and often requires retaining an attorney or at minimum preparing formal briefs. Most people do not reach this stage, but it exists as a recourse when the Board of Review decision appears unsupported by the evidence presented. Knowing that option exists changes how seriously you prepare for the initial hearing.
The assessment cycle runs annually, with notices typically mailed in late summer or early fall. The valuation date is January first of that year, meaning the market conditions as of early January determine your assessment regardless of when you receive the notice or sell the property later in the year. Selling in July does not retroactively adjust your assessment for that tax year. This timing detail causes repeated confusion, and it is worth noting because property owners sometimes assume a mid-year sale will reset their tax basis immediately. It does not. The sale price may influence the next year's assessment, but the current year is fixed. For most residential property owners in Sioux City, the assessment process is transparent enough that disputes are infrequent. The system functions on data submitted by local assessors, state-reviewed comparables, and standardized formulas. Errors do occur, and the appeal mechanism exists precisely to correct them. The key is knowing when an error is real, having the documentation to prove it, and acting within the deadlines that govern the process.