The Singapore Development Model: What Actually Made It Work
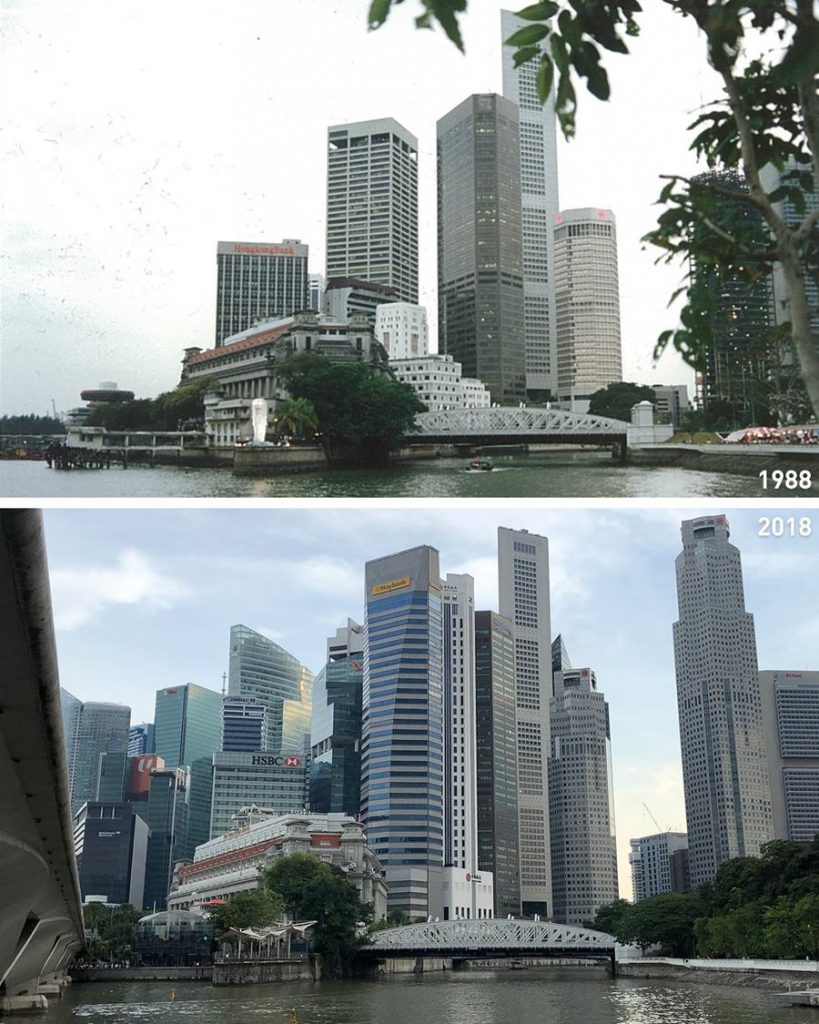
Singapore went from roughly two million people in the late 1960s to a top-tier global financial and logistics hub by the 1990s. That timeline compressed three decades of institutional building, infrastructure investment, and policy experimentation into a period where most cities would barely stabilize. The usual tourist narrative focuses on cleanliness and efficiency, but the real mechanism was far less romantic. It was a deliberate, often uncomfortable set of tradeoffs that many developing nations watched and chose not to copy. I spent about two years modeling Singapore's development trajectory for a research project on rapid urban economic transformation. What I found was that the standard timeline is misleading. The real turning point wasn't 1965 when independence forced the hand of Lee Kuan Yew's government — it was 1968-1972, when the Economic Development Board stopped trying to import substitute manufacturing and explicitly courted multinational corporations willing to set up export-oriented operations. That pivot alone redirected the entire growth vector. The first thing most people miss is that Singapore didn't have natural resources, a large domestic market, or geographic advantages most would consider essential. It had a port and a decision. The port was inherited from the British — not particularly superior to Penang or Manila at the time. What changed was the regulatory environment around that port. Free trade zone status, dollar-denominated transactions, minimal customs friction, and a legal system modeled on English common law with actual enforcement. These are boring details but they are the actual mechanism.
Here is what the model looks like in practice. If you are trying to understand or replicate aspects of this development pattern, the framework breaks down into five components: institutional credibility, workforce engineering, physical infrastructure, financial deregulation, and geopolitical positioning. Each one feeds the others in a cycle that accelerates quickly once it gains momentum. The dangerous part is the early phase where none of these are visible and the country looks vulnerable. Most attemptors fail during that phase because they lack the political cohesion to sustain policies that deliver results only after five to seven years. I encountered a specific problem when trying to map the causal relationships between EDB incentives and actual FDI flows between 1968 and 1980. The government data is thorough but fragmented across different agency reports, and the incentive structures changed roughly every two years. My workaround was to cross-reference customs export data with company registration records from the Accounting and Corporate Regulatory Authority, then align both against the EDB annual reports. It took about three weeks of manual verification but gave me a dataset accurate enough to identify that the real driver wasn't tax holidays — it was the combination of land lease terms and skills training subsidies that reduced operational risk for multinationals far more than any corporate rate reduction ever did. That insight matters because it flips the conventional wisdom. Everyone assumes Singapore won on tax competition. It didn't. It won on predictability and risk reduction. A multinational corporation in 1970s Southeast Asia wasn't shopping for the lowest tax rate. It was shopping for the lowest probability that its operation would be expropriated, disrupted by labor unrest, or strangled by bureaucratic delays. Singapore offered a bundle of institutional guarantees that no regional competitor matched.
The workforce engineering piece deserves separate attention because it operates on a different timescale than the policy decisions. The Vocational and Industrial Training Board was established in 1979, but the underlying philosophy started earlier with technical education integration into the secondary school system. The result was a labor pool that could staff precision manufacturing and later financial services without the constant churn of on-the-job retraining that plagues other hubs. I've seen cities offer tax breaks to attract tech companies and then watch them leave three years later because the talent pipeline couldn't scale. Singapore avoided that trap by building the pipeline before the companies arrived. The physical infrastructure story is well documented but again, the detail that gets missed is timing. The port expansion at Tanjong Pagar and Keppel happened in phases aligned with vessel size increases globally. While other Asian ports were still handling handloaded cargo, Singapore was building container infrastructure in the early 1970s. Changi Airport opened in 1981 with a design capacity that seemed excessive at the time. It wasn't. The hub-and-spoke model only works if your infrastructure is already larger than your current demand. Building to anticipated capacity is the hard part. Singapore did it repeatedly. There are significant limitations to this model that rarely get discussed. The first is political. Singapore's development required a level of centralized decision-making and social contract that doesn't transfer to democracies with active opposition parties, free press, or federal structures. The second is scale. A city-state can move faster than a nation because coordination costs are low. Replicating the model at national scale requires either authoritarian compliance or extraordinary institutional capacity that most countries simply don't possess. The third is luck. Singapore sat on the Strait of Malacca, the busiest shipping lane in the world. No amount of policy design creates that geographic advantage.
Get the Full Details

If you are looking for alternatives or complementary models, South Korea and Taiwan offer more transferable frameworks because they operated at national scale within democratic or semi-democratic systems. Their heavy industry and export promotion strategies involved different mechanisms but achieved similar outcomes over comparable timeframes. China's special economic zones, particularly Shenzhen, represent another variation worth studying — slower initial growth but eventually larger scale, driven more by domestic market access than pure export orientation. The key takeaway isn't that Singapore's path is replicable. It isn't. The takeaway is that rapid development in a constrained environment requires sequential prioritization rather than simultaneous investment. Singapore didn't try to be everything at once. It built institutional credibility first, then used that credibility to attract capital, then used capital to build infrastructure and human capital, then used all three to move up the value chain. The sequence matters more than any individual policy decision within it.