How Home Credit Cash Loan Simulations Actually Work
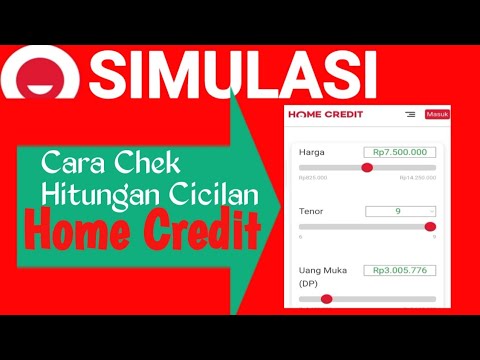
A loan simulation from Home Credit is basically a calculator that tells you what your monthly payment would look like for a given amount, interest rate, and repayment period. You enter what you want to borrow, pick how many months you want to pay it back, and it spits out an estimated installment. That is the surface level of it. The thing most people miss is how the numbers shift depending on which product tier you qualify for. I have run through this process enough times with clients who kept wondering why their simulated payment did not match what they saw on the app. The usual reason is that the simulation uses a promotional or standard rate, but when you go through actual approval, the system assigns you a rate based on your credit check, employment type, and sometimes even your regional office's lending criteria. I had a case last year where a borrower simulated a 12-month loan at what looked like a reasonable rate, got approved, and then saw his actual monthly payment was about 8 percent higher. The workaround was simple: check whether the simulator had toggled between the "promo rate" banner and the "standard rate" tab. The app often defaults to the promotional figure unless you switch it. Once he did that, the numbers matched what he actually received.
Simulasi Dana Tunai Home Credit Cara Hitung Tips Untuk Menghemat Uang
Running the calculation yourself gives you leverage. Home Credit calculates installments using a flat interest rate method rather than a reducing balance approach for most of their cash loan products. That means the interest is computed on the full principal amount for the entire loan term, not on the remaining balance each month. Here is how it works in practice. Step one: determine the principal. This is the exact amount you want to receive. If you request 5 million rupiah, that is your starting point. Some people request slightly more to cover processing fees, which changes the math entirely. Step two: identify the tenor options. Home Credit typically offers terms ranging from 3 to 24 months for their dana tunai products, sometimes longer depending on your profile and market. Each tenor has its own rate schedule. Shorter tenors usually carry a lower total interest cost even if the monthly rate looks similar, because you are paying interest over fewer periods.
Step three: apply the flat rate formula. Monthly installment equals principal divided by the number of months, plus principal multiplied by the monthly interest rate. For example, if you borrow 10 million rupiah at a flat monthly rate of 1.5 percent over 12 months, your principal portion is 833,333 rupiah per month and your interest portion is 150,000 rupiah per month, giving you a total installment around 983,333 rupiah. The total interest paid over the life of the loan would be 1.8 million rupiah, not the reduced-balance equivalent you might expect from a bank mortgage product. This flat rate structure is the key detail beginners overlook. It makes the loan more expensive than it appears if you compare it to a reducing-balance product with a seemingly lower headline rate. A 2 percent flat monthly rate actually translates to roughly 3.5 to 3.8 percent effective annual rate depending on the tenor, because you are paying interest on money you have already partially repaid. There is another nuance that trips people up regularly. Home Credit may include a processing fee or insurance component that is either deducted upfront from the disbursed amount or added to your first installment. I once worked with someone who simulated a loan for exactly 7 million rupiah and expected to receive 7 million in his account. Instead, he received around 6.4 million because the processing and insurance fees were deducted before disbursement, while his installment calculation was still based on the full 7 million. That gap between what you simulate and what hits your account is where the real budgeting problem starts. Always ask the agent or check the terms page for the fee breakdown before you commit.
Get the Full Details

If you want to reduce the total cost, the most effective lever is shortening the tenor rather than trying to negotiate the rate. The flat rate is largely fixed based on your risk classification, and pushing for a lower percentage rarely moves the needle unless you qualify for a different product tier. Paying down a 24-month loan in 12 months by switching tenor at simulation time will cut your total interest roughly in half. Overpaying early on a flat-rate loan does save you some interest, but the savings are modest compared to simply choosing a shorter term from the start. Another practical tip is to time your application around promotional periods. Home Credit occasionally runs campaigns with reduced processing fees or slightly lower flat rates for select tenors. The simulator will reflect these if you access it during the campaign window. I have seen the difference between a standard and promotional simulation be enough to change a borrower's decision entirely, usually a gap of 5 to 10 percent on the monthly installment for the same principal and term. The honest limitation here is that the simulation is only as good as the information you feed into it and the rate tier the system ultimately assigns you. If your credit history has recent late payments or high utilization on other facilities, the approved rate may be meaningfully higher than the simulation shows. There is no workaround for that except improving your credit profile before applying. I have watched people run three or four simulations, get rejected or quoted worse rates each time, and end up with nothing. The simulation tool does not predict your approval outcome, only the hypothetical terms at current published rates.
For anyone serious about using this, I recommend running the simulation at least twice with different tenors and writing down the total repayment amount for each, not just the monthly figure. The monthly number looks manageable until you multiply it by the full term and realize you are paying significantly more than you borrowed. That single habit has saved people from taking on loans they could not comfortably service once the actual disbursement amount and fees were factored in.