Understanding Simples Nacional
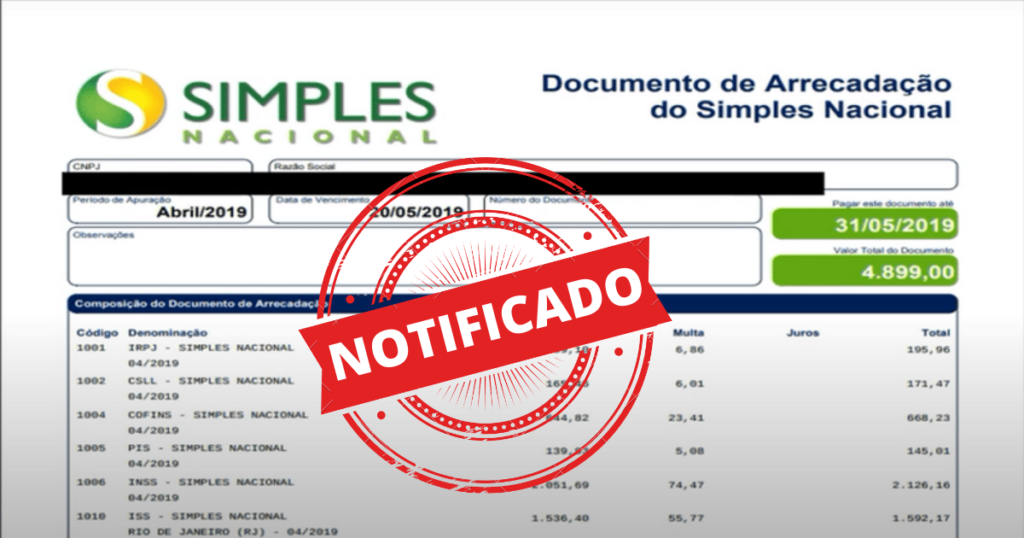
Simples Nacional is Brazil's simplified tax regime for micro and small businesses. It replaced eight different federal taxes with a single monthly payment calculated using a percentage of your gross revenue. The rates start around 6% for very small businesses and can climb to 33% depending on your activity sector and revenue bracket. State and municipal taxes get folded into that one payment instead of being filed separately. The Receita Federal handles the administration of this system, and filing is done through the DAS (Documento de Arrecadação do Simples Nacional) slip. You log into the federal system, enter your revenue for the month, and it generates the payment slip with all applicable taxes broken down. The whole process takes about five minutes if your accounting software is set up correctly. I remember the first time I accidentally triggered an Annex III rate instead of Annex V for a consulting client who also sold physical products. They had under R$180,000 in annual revenue, so they qualified for the simplest bracket, but the wrong annex calculation inflated their tax bill by about four percentage points for that quarter. The fix was straightforward once I realized the issue: you need to classify your revenue by activity code correctly when setting up the empresa no sistema. Receita Federal allows you to correct past declarations through the adjustment window, but you have to act within the same fiscal year or you lose the chance. That mistake cost them roughly R$2,400 extra in that quarter alone. Not catastrophic, but entirely preventable.
Who Qualifies
Your company needs to meet several conditions simultaneously. Gross revenue cannot exceed R$4.8 million per year. You cannot have shareholders or partners who are legal entities themselves unless they qualify as individuals under the rules. The company must not participate in special tax arrangements or benefit from development incentives that conflict with the Simples framework. Most service companies, retailers, and light manufacturers fit this profile without issue. What people commonly miss is the revenue calculation includes not just sales but also interest income, dividends in certain cases, and intercompany transactions. If you have a holding structure or significant non-operational income, your effective revenue for Simples Nacional purposes might push you over the limit even when your operating revenue looks fine. I had a client who was making R$4.2 million in actual sales but had R$700,000 in investment returns that got aggregated into the calculation. They exceeded the ceiling and were forced out of the regime mid-year, which triggered a messy reclassification period with the standard tax obligations catching up retroactively. The workaround was restructuring their investment holdings into a separate legal entity before the fiscal year ended.
How the Calculation Works
The system uses six different annexes based on your primary economic activity. Annex I covers retailers. Annex II covers constructors. Annex III covers industrial manufacturers. Annex IV covers transport services. Annex V covers service providers. Annex VI applies to some specific professional activities. Each annex has its own progressive rate table with five tiers based on revenue bands. The computation follows a cumulative method. You calculate the effective rate for the current month based on year-to-date revenue, then apply that rate only to the current month's revenue, subtracting any tax already paid in previous months. This means your effective rate can actually decrease as the year progresses if you stay within a bracket, which is counter to how most people expect progressive taxation to work. The Receita Federal system handles this automatically when you file the DAS each month. Here is a practical example. A software consultancy in Annex V with R$240,000 in January revenue and R$280,000 in February revenue would calculate February's tax differently than January's because the cumulative revenue changed the applicable bracket. January falls in the first tier. February pushes the cumulative total past a threshold, and the system recalculates using the higher bracket rate but only on the marginal amount. The actual payment for February accounts for this adjustment. Without the system doing the math, manual calculation gets complicated fast, especially when revenue fluctuates month to month.
Get the Full Details

The Download and Filing Process
You access the DAS generation tool through the Receita Federal website at simplesnacional.gov.br. After authenticating with your company's digital certificate or the gov.br credential system, you select the relevant month and the system pulls your revenue data. You can either input it manually or import it from accounting software that integrates with the platform. Several popular Brazilian accounting systems support direct API import, which eliminates most data entry errors. The generated DAS slip contains a barcode and a payment code. You pay through any bank or payment processor before the 20th of the following month. Late payment triggers a 1% fine plus monthly interest compounded at 1% per month. If you miss a payment entirely, the regime can expel you after repeated non-compliance, and reinstatement requires going through the full qualification review process again.
Known Limitations
Simples Nacional does not allow tax credits on inputs. If you purchase equipment or materials, you cannot reclaim the taxes paid on those purchases. For capital-intensive businesses, this significantly increases the effective cost of operations compared to the standard tax regime where credits are available. A manufacturing company buying R$500,000 in machinery annually might lose R$90,000 in potential input tax credits by staying in Simples Nacional. The decision to remain in the simplified regime versus switching to Lucro Presumido should weigh this factor heavily if your business involves significant equipment purchases or inventory. Another limitation is the prohibition on having employees outside Brazil. If you hire contractors or staff overseas, you are automatically ineligible regardless of your revenue level. This catches many tech companies off guard who assume remote work arrangements do not affect their tax classification.
When to Consider an Alternative
If your business routinely exceeds the R$4.8 million ceiling, operates in a sector with high input costs where tax credits matter, or has international operations, Simples Nacional may not be the optimal structure. Lucro Presumido offers a different rate structure with credit mechanisms and no strict revenue cap. The transition between regimes is possible but requires careful timing to avoid double taxation during the overlap period. Receita Federal publishes guidelines for regime transitions, but the accounting work involved means you should plan the switch during a low-revenue quarter and budget for at least two months of additional compliance overhead during the changeover.