The Actual Mechanics Behind Shop Financing Options
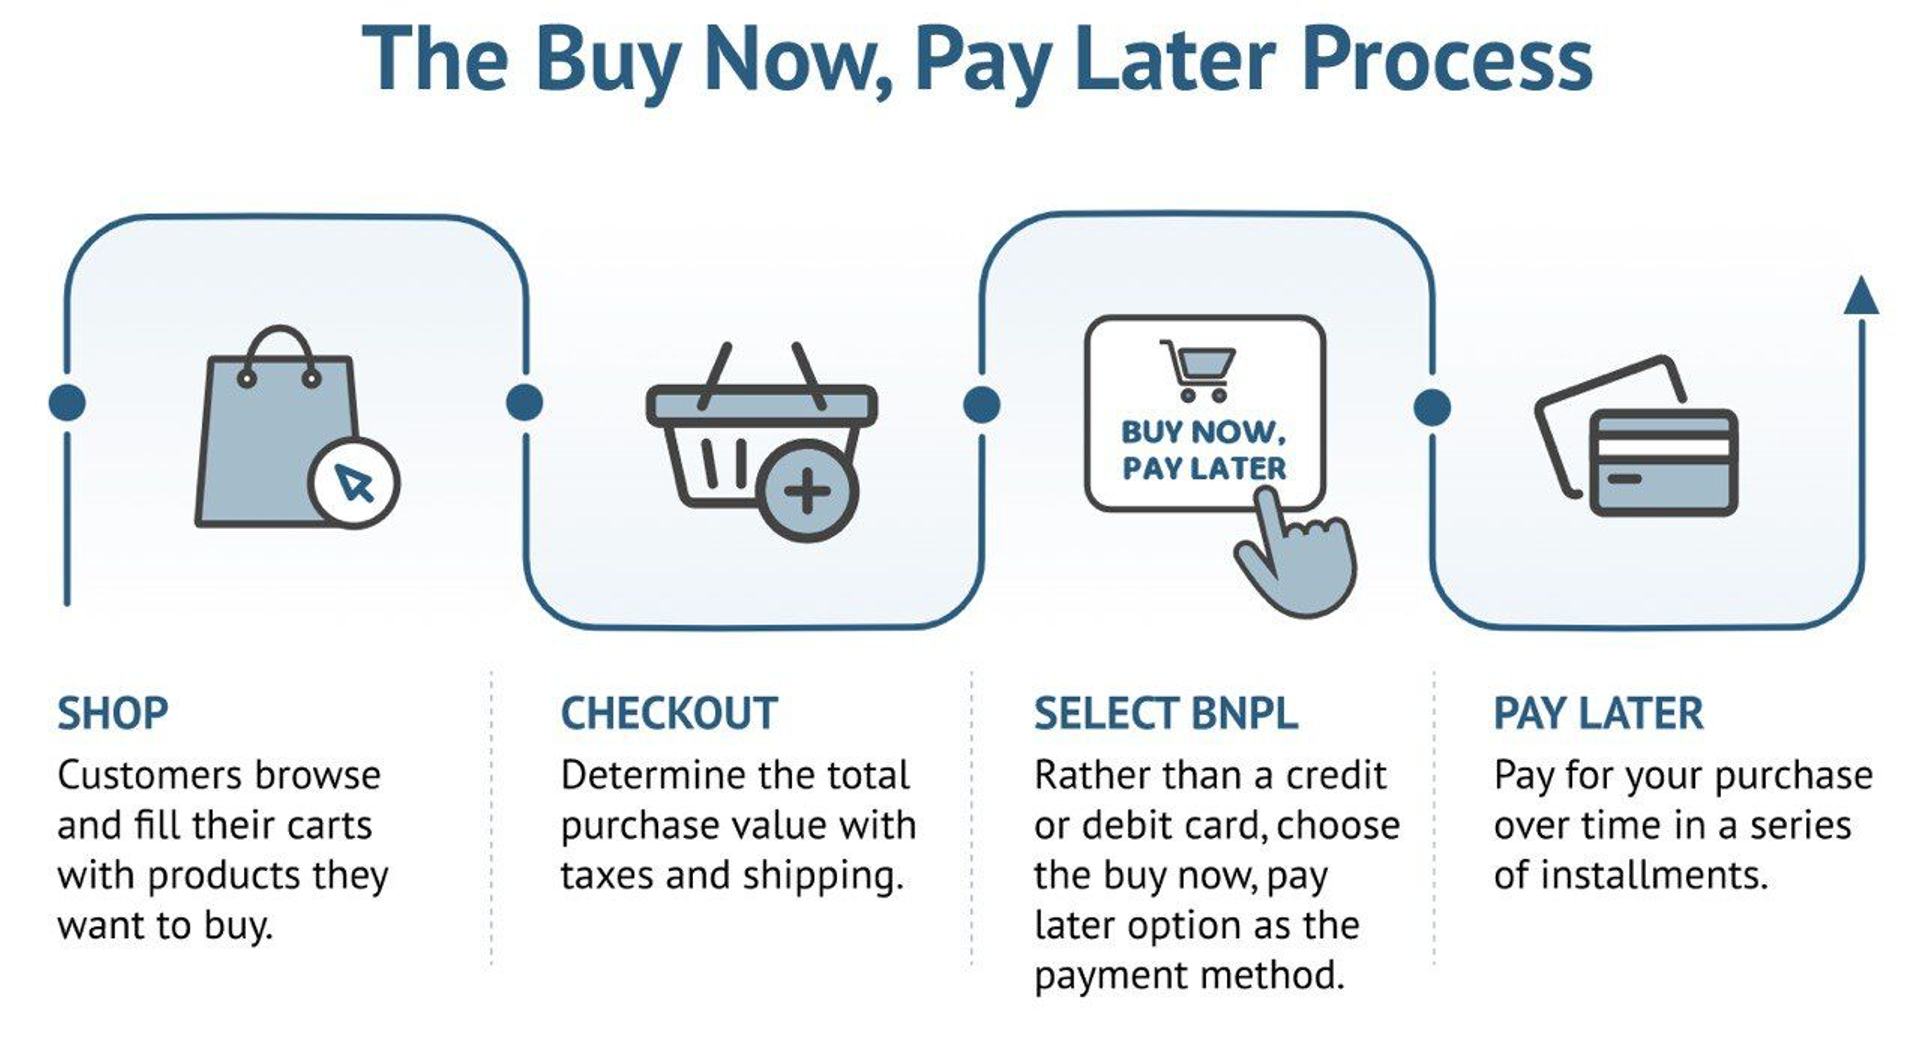
I've sat through enough merchant onboarding calls to know most people don't understand what they're actually signing up for when they offer a buy now pay later option. The sales pitch is always the same — your customers will spend more, you'll get more sales, nobody does any math. The reality is messier than that. When a shop integrates a payment plan provider, they're entering a three-party contract. The customer gets the goods immediately. The provider pays the shop in full upfront, usually within one to three business days. Then the customer pays the provider back in installments. That means the shop has already been paid but they're responsible for handling returns, disputes, and customer service questions about payment schedules. Most merchants forget that last part during the demo. The fee structure is where things get opaque. You'll see advertising for anywhere from four to fifteen percent per transaction, depending on the provider and your volume. A shop doing fifty thousand dollars a month in sales through a BNPL platform at a ten percent effective rate is paying five thousand dollars monthly. That eats into margins fast, especially if your net profit margin before financing costs is sitting around twelve percent.
Shops That Finance Your Guide To Buy Now Pay Later Save Money Pay Later Own It Faster
The marketing language around these programs usually centers on keywords like save money, pay later, own it faster, and buy now pay later. It's designed to sound like the customer is getting a deal. They're not. The interest is baked into the product price or the merchant fee. The customer who pays off a twelve-month plan with no advertised interest is still paying for that extension somehow. If you're a merchant considering this, the first thing to check is whether the provider treats returns correctly. I worked with a small furniture retailer who had a nightmare scenario in early 2024. A customer returned a sofa after their second payment on a four-month plan. The BNPL provider had already credited the merchant in full for the original sale, but the refund to the customer was being processed by the provider directly and took forty-five days. Meanwhile the merchant was getting pinged by the platform about an incomplete return loop because their internal system flagged it as unresolved. The workaround was straightforward once I figured it out: we set up a separate reconciliation spreadsheet that tracked every BNPL transaction alongside our POS records, and we flagged anything with a financing tag as requiring manual confirmation before closing the return in both systems. Took about ten minutes per transaction instead of the twenty-minute back-and-forth headaches we were having. Here's something most guides won't tell you clearly — credit soft versus hard inquiries matter more than merchants realize. Some BNPL providers do a soft pull only, which means no impact on the customer's credit score. Others run a hard inquiry that drops their score by a few points. If you're targeting a younger demographic that's building credit, a hard pull provider could be actively harming the customers you're trying to convert. Check before you sign.
Another detail people miss: the approval rates vary wildly by provider and by customer segment. One provider might approve sixty percent of applicants in the eighteen to thirty age bracket while another approves eighty-five percent. But those approval rates come with different risk profiles. The provider that approves more people is taking on more default risk, which eventually gets reflected in your fees or your payout terms. There's a tradeoff baked into every approval rate number. From a customer perspective, the math works in your favor only if you pay early or on time without fees. Most plans advertise zero interest but charge late fees between fifteen and twenty-five dollars per missed installment. Miss two payments on a six-hundred-dollar purchase and you've just added the equivalent of nine percent interest to that debt. Spread that across a year and you're looking at annual percentage rates that rival credit cards. Some BNPL providers also offer seasonal promotions where merchants absorb the fee for the first ninety days. I've seen small shops take advantage of those to move inventory during slow quarters, which is legitimate. But the trap is getting comfortable with the higher ongoing fee after the promotion ends. The merchant's pricing model was built around the subsidized period, so when the standard rate kicked in, their margins collapsed without anyone noticing until the quarterly reconciliation.
Get the Full Details

If you're a customer, the actual savings from using a payment plan are zero unless you were going to buy it anyway and the installment structure helps you manage cash flow better than a single lump sum. That's not a discount. That's budgeting flexibility with risk. If you use a credit card and pay it off every month, you're almost always better off. You get the reward points, the fraud protection, and the ability to dispute charges. With BNPL, your dispute process runs through the provider, not your bank, and resolution times average between two and six weeks. The one scenario where BNPL genuinely makes sense for a customer is when you need an item immediately and your credit card has a limit that's too low to cover it, and you can commit to the payment schedule without missing a single installment. In that case it's functionally equivalent to a zero-interest loan from your future self. For merchants, the decision comes down to whether the incremental sales from offering payment flexibility outweigh the effective cost of the service plus the operational overhead of managing returns and disputes across two systems. I've seen well-run shops pull maybe eight to twelve percent of their revenue through BNPL channels. That's significant but it's not transformative. The sales lift is real, but it's also concentrated among customers who were already likely buyers at full price, which means you're partly subsidizing purchases that would've happened anyway.
The alternative worth considering is a traditional store credit or loyalty financing program run in-house. Higher setup cost, more regulatory compliance, but you control the terms, you keep the data, and you avoid paying a middleman six to ten percent on every financed sale. For shops doing over two hundred thousand dollars annually, the math starts to tip in that direction within eighteen to twenty-four months. What you should actually look for before signing with any provider is clear language about who owns the debt during a return, how late fees are calculated, whether they report payment history to credit bureaus, and what happens if the provider changes their terms. I've watched contracts where the provider could adjust fees with thirty days notice and the merchant had no recourse beyond termination. That clause alone has caused problems for shops that switched too late. The industry standard now is Klarna, Afterpay, Affirm, and Sezzle in the US market, with some regional players like Quadpay folding into larger entities. Each has different onboarding requirements, payout speeds ranging from same-day to seven business days, and slightly different risk models. There's no single best provider. The right one depends on your average order value, your customer demographics, and how much operational bandwidth you have for handling the administrative complications.
Average order values under two hundred dollars tend to perform better on Afterpay and Klarna. Orders between three hundred and two thousand often align better with Affirm's longer-term installment structures. Anything above that range usually requires either a high-ticket BNPL provider or a traditional financing partner. Don't force a square peg into a round hole because the sales deck sounded convincing. Keep a spreadsheet. Track your BNPL revenue, your fees, your return rates specifically for financed transactions versus regular purchases, and your customer service ticket volume related to payment issues. Do that for six months and you'll know whether the program is actually helping you or just making your accounting department uncomfortable. Most merchants skip that step and judge success by total sales volume, which is the wrong metric.