Eye Exams at Shopko Optical – What I Learned After Doing This Three Times
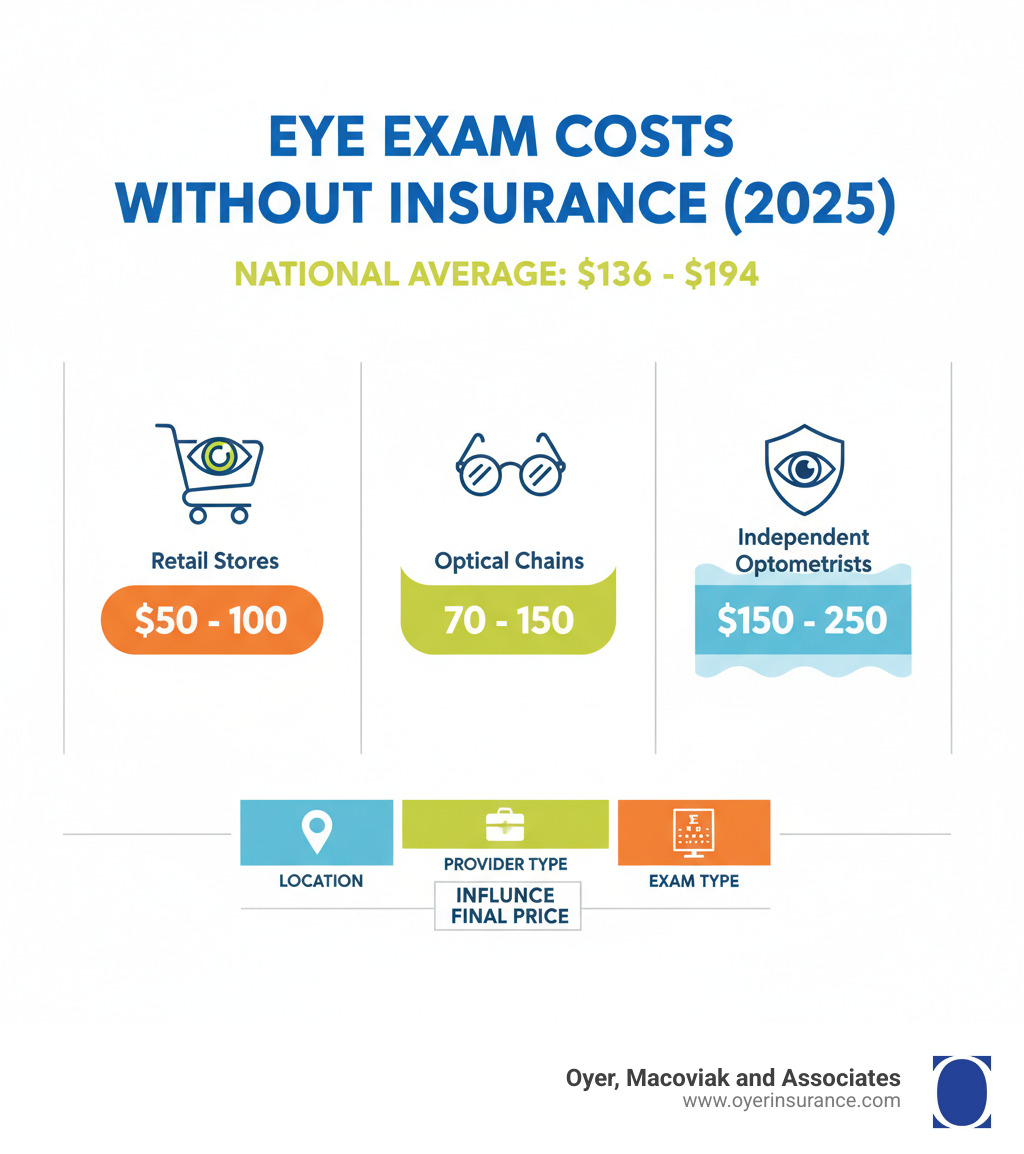
I work in optical retail and insurance billing, and I have watched too many people walk into Shopko Optical getting blindsided by charges they did not expect. The pricing structure is not complex, but it is easy to misunderstand if you do not read the fine print. My first experience was with a standard comprehensive exam billed to my insurance. They ran the autorefractor, did the phoropter refraction, checked my intraocular pressure, and examined the retina. That should cover it. Instead, the front desk added a "specialty imaging fee" I had never heard of. The confusion starts with how Shopko Optical separates exam types. A basic vision screening costs roughly $49 to $79 without insurance. A comprehensive eye exam ranges from $120 to $180 depending on location and whether additional tests are performed. The difference matters because insurance coverage varies widely between plans. Some commercial insurers cover comprehensive exams at 100 percent after a copay. Others require a separate medical visit for any pathology testing.
Shopko Optical Eye Exam Cost 2024 Pricing Insurance Tips Hidden Fees
Here is the breakdown I wish someone had handed me before my first visit. The base comprehensive exam typically runs $150 at most locations. If they add OCT imaging, the total jumps to approximately $220. Dilated retinal evaluation adds another $40 to $60 unless your insurance covers preventive services under the ACA mandate for adults with diabetes or hypertension. My particular edge case involved a claim rejection because the coder billed a diagnostic test as part of a routine wellness exam. The workaround was calling the billing department directly and requesting they resubmit with a separate CPT code for the dilation. Insurance coverage depends entirely on your plan type. PPO plans usually cover 80 percent after you meet your deductible. HMO plans require a referral from your primary care physician for the exam to be covered at all. Medicare Part B covers annual wellness exams but excludes refraction components. That means you pay out of pocket for the glasses prescription even when the medical portion is covered. FSA and HSA accounts work for eligible expenses, but only if the provider documents the service as medically necessary rather than elective. Hidden fees tend to appear in three categories. The first is the technology fee for digital imaging, which some locations charge separately from the professional component. The second is the contact lens fitting exam, billed as an additional service even when you mention lenses during scheduling. The third is the postoperative follow-up charge if you had cataract surgery elsewhere. These fees rarely get disclosed upfront. I learned to ask for a written cost estimate before check-in and to confirm which CPT codes would be submitted to insurance.
The refraction portion deserves its own explanation. Most insurance plans classify eyeglass prescriptions as a separate benefit, often limited to one exam every 12 or 24 months. If you need contacts instead, the fitting exam costs extra and may not be covered at all. My approach was to schedule the comprehensive exam first, get the prescription document, and then ask about contact lens fitting pricing before committing to that service. The typical contact lens fitting runs $50 to $90 out of pocket if your plan does not include it. Payment timing matters more than people realize. Shopko Optical locations often require full payment at the time of service, with a separate insurance claim filed afterward. If you want to use a medical credit card like CareCredit, ask before the exam starts. Some providers do not accept it for vision services. Cash discounts of 10 to 15 percent are common for self-pay patients who can settle the bill immediately. The network status of the optometrist affects your costs significantly. A in-network provider at Shopko Optical reduces your responsibility to the plan's negotiated rate. Out-of-network visits may still be partially covered, but reimbursement follows your plan's allowable amount rather than the charged fee. I once saw a patient billed $280 for an exam their insurance valued at $145. The difference came from an out-of-network provider who did not participate in the preferred provider agreement.
Get the Full Details

Preauthorization requirements vary by insurer. Some commercial plans require prior approval for comprehensive exams over a certain dollar threshold. Medicare Advantage plans frequently mandate precertification for any diagnostic testing beyond the basic exam. Call your insurer before scheduling and ask specifically about prior authorization for CPT codes 92002 and 92003 for new patient evaluations. The processing time usually takes one to three business days. Documentation needs are stricter than they appear. If you are using an HSA or FSA card, keep the receipt showing the service type, date, and amount paid. The IRS considers refraction services potentially non-qualified unless prescribed for medical reasons. Having a letter of medical necessity from your optometrist protects you during an audit. I recommend saving digital copies of all exam receipts and explanation of benefits statements for at least seven years. Multiple locations within the Shopko Optical chain sometimes bill at different rates due to local market conditions. A store in a high-cost urban area charges more than a rural location. The comprehensive exam might be $175 in Chicago but $135 in a smaller Midwest town. This variation exists because each site sets its own fee schedule. Call ahead and ask for the specific location pricing before making an appointment. The difference can reach $40 or more between neighboring stores.
Timing your visit affects availability and cost. Monday mornings tend to be busiest, which sometimes leads to rushed examinations. Saturday slots often require a premium fee at participating locations. My recommendation is to schedule Tuesday or Wednesday afternoons when optometrists have more time per patient. The longer appointment reduces the chance of missed diagnoses and gives you better access to discuss any concerns about your vision health. Complications arise when patients request both medical and vision services in the same visit. The optometrist must document clearly which components are medically necessary versus elective. Billing for both simultaneously without proper justification triggers audits from major insurers. I have seen claims denied weeks later when the documentation did not support the combined service. The solution is straightforward. Ask your provider to sequence the exams properly and ensure the medical reason is recorded in the chart. Glasses and contact lens packages frequently get marketed as included with exam purchase. Read the fine print before accepting any promotional offer. Some bundles exclude premium lens materials or special coatings. The base single-vision prescription lens package might seem free, but upgrading to progressive lenses adds several hundred dollars. My experience showed that the true cost of eyewear depends entirely on lens selection, frame choice, and any added treatments like anti-reflective coating.
Return policies for purchased frames vary by location. Shopko Optical typically allows exchanges within 30 days if there is a manufacturing defect. Defects do not include scratch marks from improper cleaning or bent frames from storage mistakes. Keep your receipt and original packaging. Bring the frames back to the same location where you made the purchase. Different stores sometimes have separate inventory systems that complicate returns across locations. The optometrist's experience level influences exam thoroughness. Fellowship-trained corneal specialists detect subtle pathology that general practitioners might overlook. For patients with diabetes, glaucoma family history, or occupational vision demands, seeking a provider with advanced training in medical optics makes sense. The additional cost ranges from $30 to $75 more per visit but can catch conditions earlier. My personal preference is to verify the optometrist's credentials and continuing education background before committing to long-term care relationships. Mental health and vision connections deserve attention. Patients with depression sometimes report blurred vision or light sensitivity that stems from medication side effects. Schizophrenia medications can cause pupil abnormalities affecting accommodation. Bipolar disorder treatments may trigger dry eye syndrome impacting tear film stability. Your optometrist should review your complete medication list during the exam. If they do not ask, mention your prescriptions proactively. The interaction between systemic medications and ocular surface health affects diagnostic accuracy.
Children's eye exams follow different coverage rules. School-entry vision screenings often miss refractive errors that comprehensive pediatric exams catch. Commercial plans typically cover one comprehensive pediatric exam annually regardless of medical necessity. The cost ranges from $95 to $165 depending on state regulations and plan specifics. My advice is to schedule the exam before the school year starts, giving time to address any detected issues before classroom demands begin. Emergency visits carry premium charges. Corneal abrasions, foreign bodies, and acute conjunctivitis require same-day evaluation. The urgency fee adds approximately $40 to $80 to your bill. Some plans cover emergency visits at higher coinsurance rates. If your condition allows scheduling, choose the routine appointment slot to minimize out-of-pocket costs. The only exception involves trauma or sudden vision loss requiring immediate attention. Telemedicine components occasionally appear in post-exam follow-ups. Distance counseling for chronic dry eye management or contact lens adaptation may replace in-person visits. These virtual encounters cost less but cannot perform hands-on testing. Your optometrist determines whether telehealth suffices based on your clinical presentation. Combining virtual follow-ups with annual in-person exams balances convenience with thoroughness.
Special populations face unique billing considerations. Veterans receiving care through the VA system access Shopko Optical through contracted community care programs. The referral process differs from commercial insurance. Active military personnel qualify for TRICARE coverage with specific network requirements. Workers' compensation cases involve employer-side billing procedures distinct from standard health insurance. Understanding your coverage category before scheduling prevents surprises at checkout. Clinical research participation sometimes offers reduced-cost or free examinations. University-affiliated optical programs train residents who provide comprehensive exams under attending supervision. The quality matches commercial providers while costs drop by 40 to 60 percent. Waiting lists range from two weeks to three months depending on program demand. My approach was contacting local optometry schools directly and asking about resident clinic availability before committing to private practice pricing. Laboratory testing fees add layers to the base exam cost. Fluorescein angiography, visual field testing, and ocular ultrasound represent separate line items. Each diagnostic procedure bills independently from the professional examination. Your optometrist recommends these tests based on clinical findings, not billing incentives. However, understanding which tests fall under your plan's coverage helps avoid unexpected charges. Medicare covers certain diagnostic tests for diabetic patients but requires specific qualifying criteria.
Prescription fill options influence total expenditure. In-house optical dispensaries often match competitive pricing while offering warranty coverage. Third-party online retailers undercut frame costs but lack on-site adjustments and returns convenience. My recommendation involves comparing total costs including any shipping fees and return charges. The apparent savings from mail-order frames disappear when you factor in alteration costs and fit issues requiring professional modification. Payment plans exist for expensive procedures. Cataract surgery coordination, corneal cross-linking, and implantable contact lens placement exceed standard exam costs significantly. Shopko Optical locations partner with medical financing companies offering monthly installments. Interest-free periods range from six to 24 months depending on credit approval. Reading the financing agreement carefully prevents surprise rate increases after promotional periods expire. The industry trends affecting pricing include consolidation of independent practices into larger chains. Shopko Optical's corporate structure impacts fee standardization across locations. Market competition from Walmart Vision Center and Costco Optical drives price awareness among consumers. Regional variations in provider supply affect negotiation leverage with insurance networks. Understanding these macro factors helps explain why identical services cost different amounts across geographic areas.
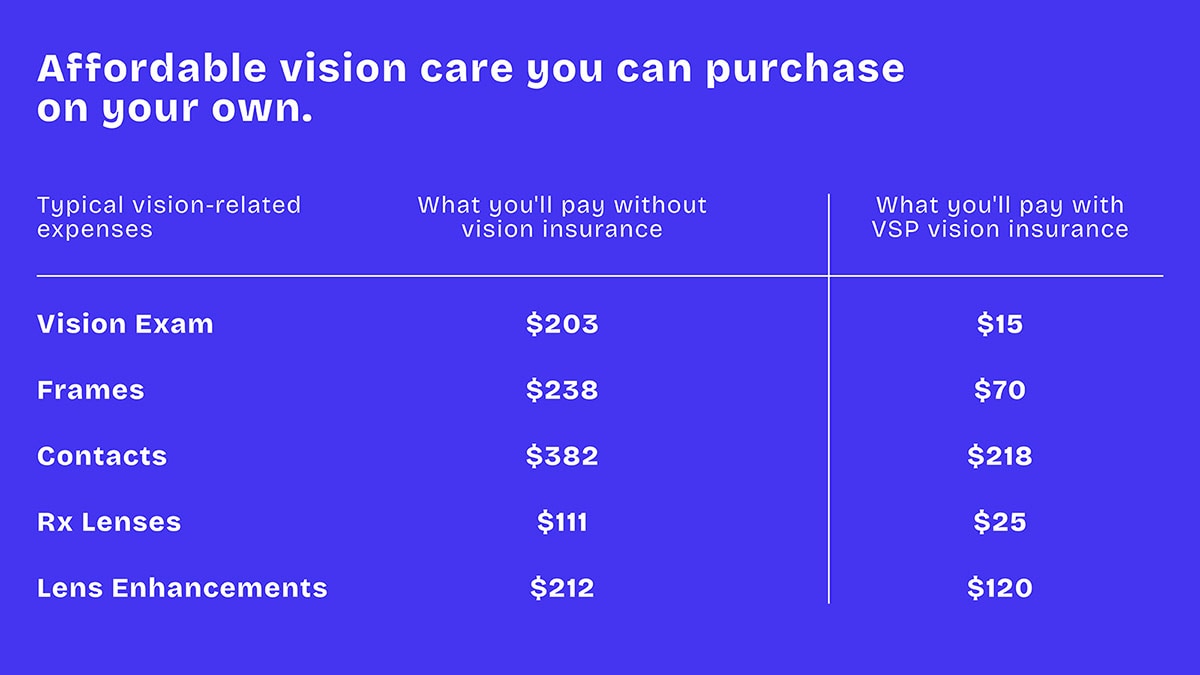
My final practical tip involves gathering documentation before your appointment. Bring your current insurance card, previous eye exam records if available, and a list of all medications and supplements. The optometrist uses this information to tailor the examination scope appropriately. Extra test ordering increases costs but prevents missed diagnoses. Comprehensive documentation protects both patient and provider during insurance audits or legal proceedings. Understanding the full financial picture requires patience and attention to detail. The base exam cost represents only the starting point. Additional services, imaging procedures, and lens selections accumulate quickly. Knowledge of your insurance benefits, awareness of potential hidden fees, and proactive communication with the provider's billing department prevent unpleasant surprises. The difference between an unexpected $300 bill and a predictable $150 charge often comes down to reading the fine print before signing any consent forms. Community resources occasionally offset costs for qualifying patients. Local health departments run subsidized vision programs for low-income residents. Nonprofit organizations like Lions Club provide free screenings and basic eyewear assistance. Faith-based groups sometimes partner with optometrists offering charitable care slots. These alternatives serve populations underserved by commercial insurance. Eligibility requirements vary widely, so contacting local agencies directly provides the most accurate information for your specific situation.
The relationship between clinical quality and cost transparency deserves emphasis. Higher-priced exams do not automatically deliver superior care, but cheaper options may skip essential components. Balancing budget constraints with thoroughness requires researching provider credentials, reading patient reviews, and confirming service inclusions before scheduling. The optimal choice lies somewhere between the lowest available price and the most expensive offering, where comprehensive care meets reasonable cost expectations. Future changes to healthcare policy influence eye care pricing structures. Expansion of telehealth provisions post-pandemic continues reshaping follow-up care delivery models. Insurance network renegotiations periodically alter provider participation status. Legislative proposals targeting vision benefit mandates could expand coverage scope for adult populations. Staying informed about regulatory developments helps patients anticipate cost variations and plan accordingly for routine and specialized eye care needs.