What Sephora Comenity Easy Pay Actually Is
Sephora partners with Comenity Bank to offer a store-branded credit card that includes a program called Easy Pay. It lets you split purchases into monthly installments instead of paying the full balance upfront. You apply through the Sephora app or at checkout, and if approved, you get a credit limit and a repayment schedule laid out on a monthly basis. It's not a loan from Sephora itself — it's a standard retail credit account backed by Comenity Bank, which is one of the bigger players in store card lending. I've used this for years because I buy makeup regularly, and sometimes I'd rather not drain my checking account in one hit. The main draw is straightforward: you can spread a big haul over several months. If you spend $300 during a holiday sale, you don't have to come up with $300 at once. You pay a portion each month alongside your regular statement. For someone who buys consistently at Sephora, that cash flow flexibility matters. The rewards structure is another piece. You earn Beauty Insider points on purchases, and Easy Pay doesn't disqualify you from earning them. That means you can still rack up points toward free products while paying over time. I've converted enough points this way to cover $40 to $60 in rewards per year, which offsets the program a bit.
But here's what people don't always catch: the interest rate. Comenity Bank's card carries an APR that's on the higher side compared to standard credit cards. I'm talking numbers in the 20-something to 30 percent range depending on your credit profile. If you carry a balance month to month, that interest compounds. A $500 purchase split into payments could end up costing you significantly more over time than if you just paid it off straight away. There's also the behavioral trap. When you have a credit line at Sephora, it's easy to justify bigger purchases than you originally planned. I definitely did this more than once. You see something you want, you think about the monthly payment, and suddenly you're spending $150 when you meant to spend $60. That gap between intended and actual spending is where people get tangled up. Another thing to consider is how this shows up on your credit report. Applying for the card triggers a hard inquiry, which can dip your score a few points. The account itself adds to your credit utilization ratio, and if you're maxing it out, that hurts your score more than you'd expect. Comenity doesn't report your payment history in the same way some larger issuers do, so timely payments don't always get the recognition they deserve across all three bureaus.
I ran into a specific issue once where I tried to use Easy Pay for a return. I'd bought a set of skincare products on installment, then returned half of them within the billing cycle. The return credit showed up on my statement, but the monthly payment amount didn't automatically recalculate to reflect the lower balance. I had to call Comenity's customer service, wait on hold for about twelve minutes, and explicitly request that my remaining payments be adjusted. They did it eventually, but it was a chore. The workaround is to always double-check your statement after any return and call if the payment schedule hasn't been updated within two billing cycles. There are scenarios where Easy Pay is genuinely useful. If you're planning a large purchase like a holiday gift haul and you know you'll have the funds to cover it within a few months, splitting it up can help you manage your budget without missing out on sales. The key is treating it like a short-term payment plan, not a long-term financing option. If you do decide to use it, here's what I'd suggest. Keep your balance below 30 percent of your credit limit to protect your credit score. Pay more than the minimum each month whenever possible. Set a reminder on your phone for payment dates so you don't miss one and get hit with a late fee. And track your total spending on the account, not just the monthly payment amount. It's easy to lose sight of the full picture when you're only focused on what comes due each month.
Get the Full Details
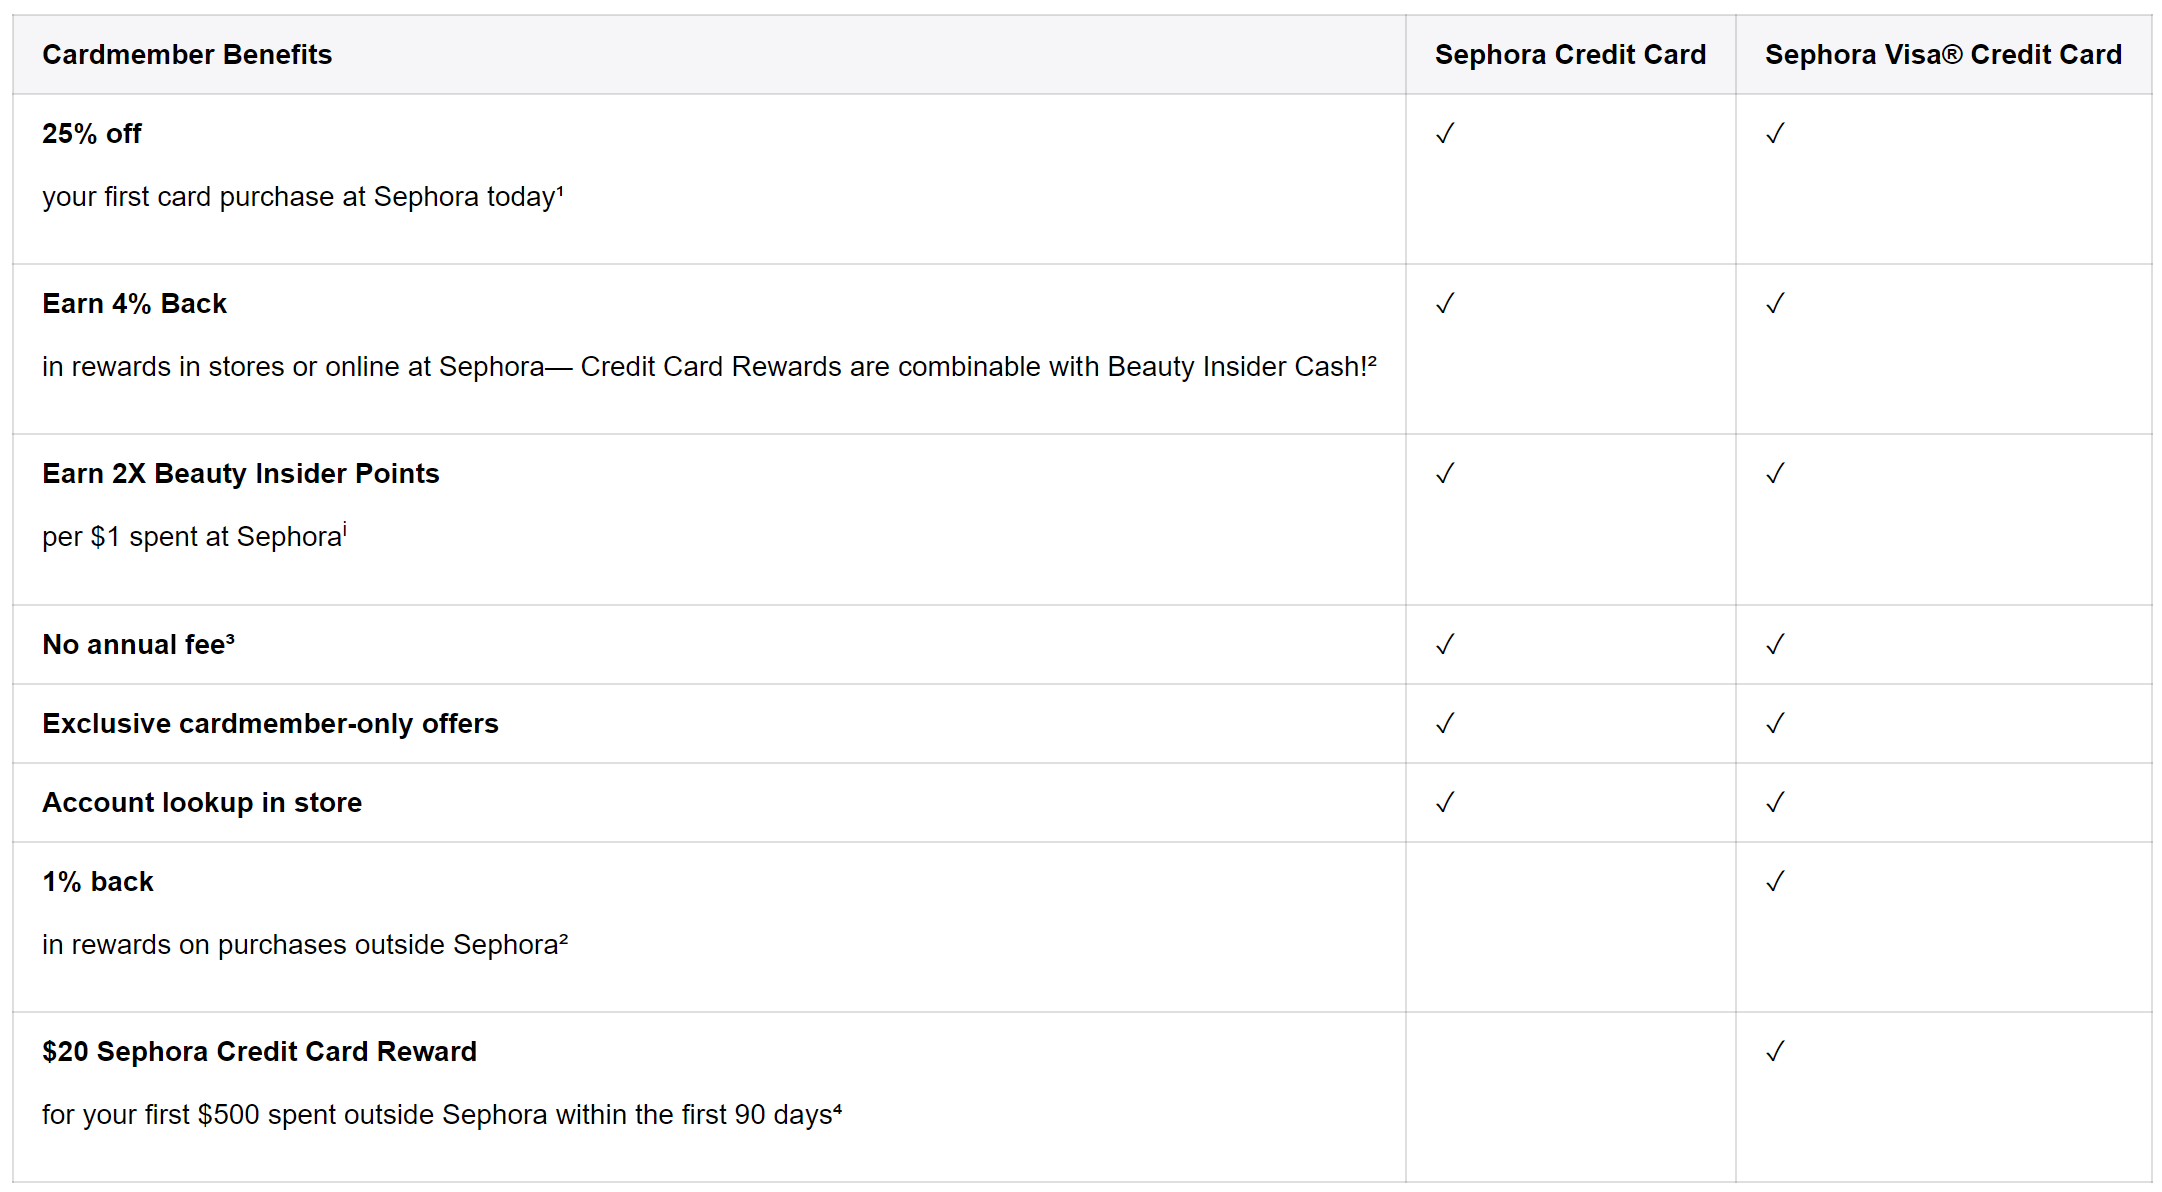
Comenity Bank does have a mobile app where you can view your balance, make payments, and check your payment schedule. It works fine, though the interface isn't the most polished. I'd recommend downloading it and getting familiar with it before you actually need to use it for anything urgent. I should mention that not everyone qualifies. Your credit score and history determine whether you get approved and what limit you receive. If you have thin credit or recent negative marks, you might get a low limit or be declined entirely. There's no way to know beforehand without applying, and every application counts as a hard pull on your credit report. The bottom line is that Sephora Comenity Easy Pay is a tool, not a solution. It works well for planned, short-term payment splitting. It falls apart when you start using it to finance purchases you can't actually afford. Knowing the difference is what separates people who benefit from it and people who end up owing more than they expected.