What Shipyard Layoffs Are Actually Looking Like Right Now
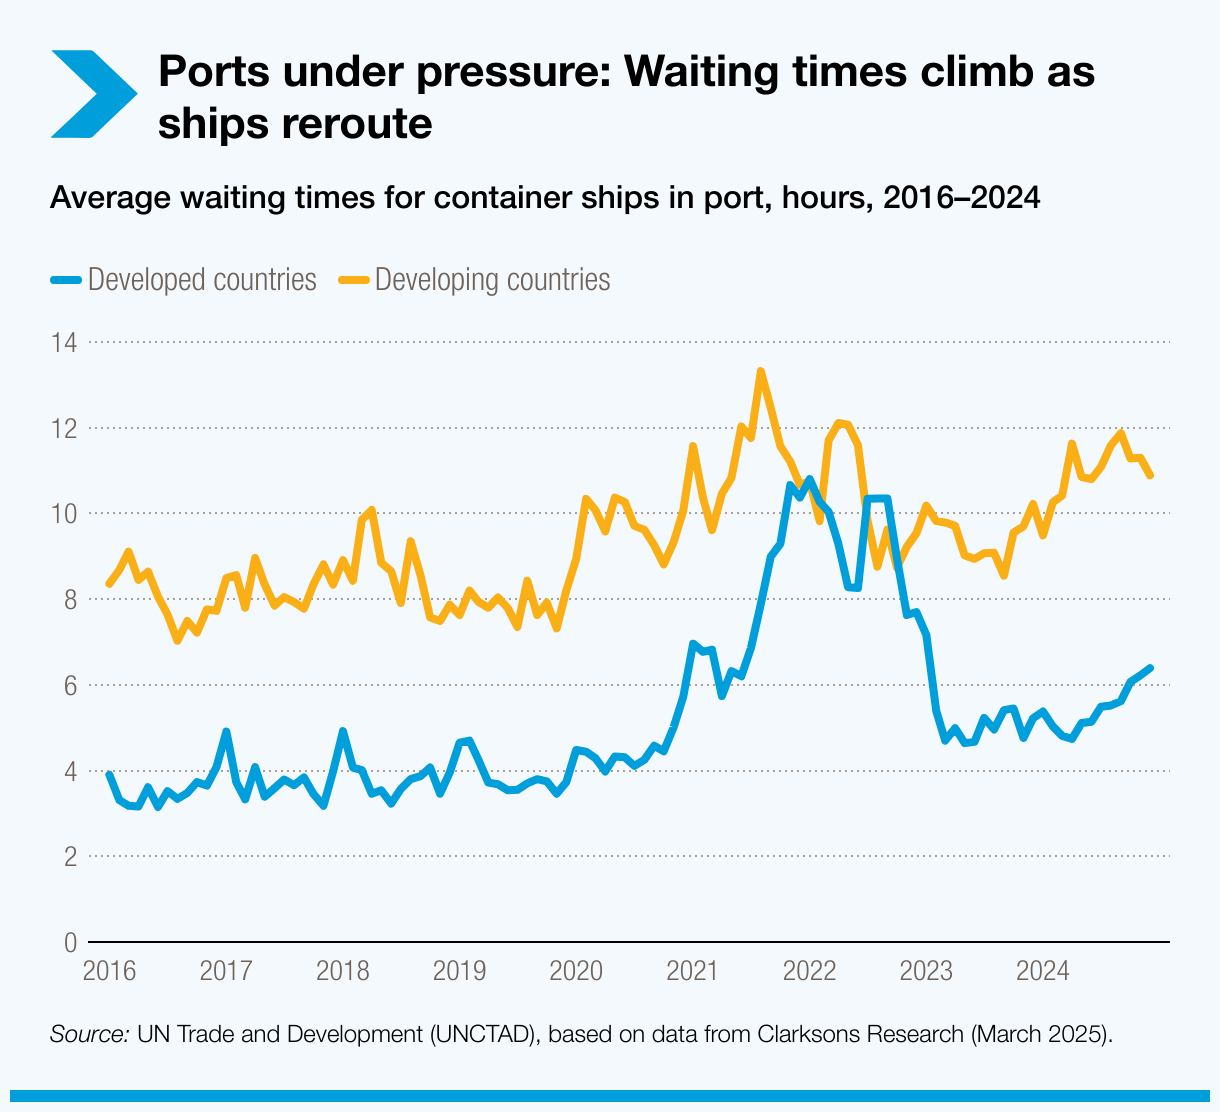
I spent the first week of January going through crew change manifests for a medium-sized vessel management company, and the pattern was already obvious to anyone who has watched these cycles. The numbers didn't lie. What the headlines are calling the Shipyard Layoffs 2025 Boombust Cycle Reshapes Maritime Industry Amid Global Uncertainty is really just a repeat of 2008-2010 and 2014-2016, but with a thinner safety margin this time because the companies that survived the last downturn are still carrying debt from the post-COVID boom years. The core mechanism is straightforward. Ship values dropped 30 to 45 percent across most sectors between late 2024 and early 2025. At the same time, newbuilding orders placed during the 2021-2023 peak are now coming due for delivery, and owners who committed capital at those prices are walking away from contracts or renegotiating terms hard. When vessels get pulled from orders or delayed at shipyards, the ripple effect hits the entire supply chain. But the layoffs happen in two distinct waves, and most people miss the difference between them.
Shipyard Layoffs 2025 Boombust Cycle Reshapes Maritime Industry Amid Global Uncertainty
The first wave hit the yards themselves. South Korean and Chinese yards cut between 12 and 18 percent of their workforce in Q4 2024 and Q1 2025. Not the offshore construction segments — those stayed busy because energy transition projects kept staffing levels intact. The ones that took the hit were commercial ship repair and conversion yards, plus the outfitting sections that handle interior fit-out work. That's where the subcontractor layer got squeezed hardest. I had a contact running a steel fabrication shop in Geoje who laid off forty-two people in three weeks because three major repair contracts got deferred simultaneously. The second wave is still happening and it's hitting the commercial side — flag state administrations, classification societies, crewing agencies, and the smaller ship management firms that don't have the balance sheet to ride out a twelve to eighteen month downturn. A mid-sized company in Greece that manages around sixty vessels cut roughly twenty-eight percent of its shore-based staff in February 2025. They didn't announce it as restructuring. They just stopped replacing people who left and sent a handful of senior managers packing with four weeks' notice. Here's the counter-intuitive part that most commentary misses. The layoffs in shipyards themselves are not the leading indicator of distress in the broader maritime sector. They're a lagging indicator. Yard workers get let go after the orderbook shrinks and after yards stop taking on new repair work, which happens after shipowners stop chartering vessels for layup and conversion. The real leading indicators are the cancellation rates on newbuilding contracts and the number of vessels being redirected from delivery to long-term layup. Those numbers started trending in the wrong direction in mid-2024. By the time the yard layoffs show up in quarterly reports, the financial damage to owners is already locked in.
Another thing people get wrong is assuming the layoffs are concentrated in a single region. They're not. What you're seeing is a geographic redistribution of work that's forcing redundancies everywhere at once. Indian and Turkish shipyards picked up some volume from the Korean yards, but not enough to offset the headcount reduction. Filipino crewing agencies saw a drop in placement volume because fewer vessels were actively trading when the Suez disruptions pushed shipping times up and fleet utilization down. Romanian ship repair yards lost contracts that used to go to Baltic yards because owners consolidated maintenance schedules to save cash. The layoffs spread across geographies because the distress is system-wide, not localized. I ran into a specific problem last spring that illustrates how messy the actual process is. A client asked me to assess the financial exposure from a batch of cancelled bulk carrier orders. The contracts were spread across three different yards in two countries, each with different penalty clauses and jurisdictional terms. The standard approach would be to calculate the cancellation fees, compare them to the original deposit payments, and net it out. That doesn't work here because several of the contracts had collateral letter-of-credit provisions that hadn't been drawn down yet, and the yards were refusing to release the LCs until the cancellation penalties were settled. So the theoretical loss on paper was different from the actual cash flow impact by nearly forty percent. The workaround was to pull the actual correspondence between the owners' legal teams and the yards, track the LC amendment requests, and model three scenarios instead of one: full penalty payment, negotiated settlement at sixty percent of the contractual amount, and contesting the penalties through arbitration with a projected timeline of fourteen to twenty months. The third scenario looked worst on paper but turned out to be the most realistic outcome for two of the three contracts. Arbitration clauses in these agreements are rarely straightforward. The yards know the owners need the capital released fast, so they stretch the process. That's not legal advice. That's just what happens when you're negotiating from a position of liquidity stress.
Get the Full Details
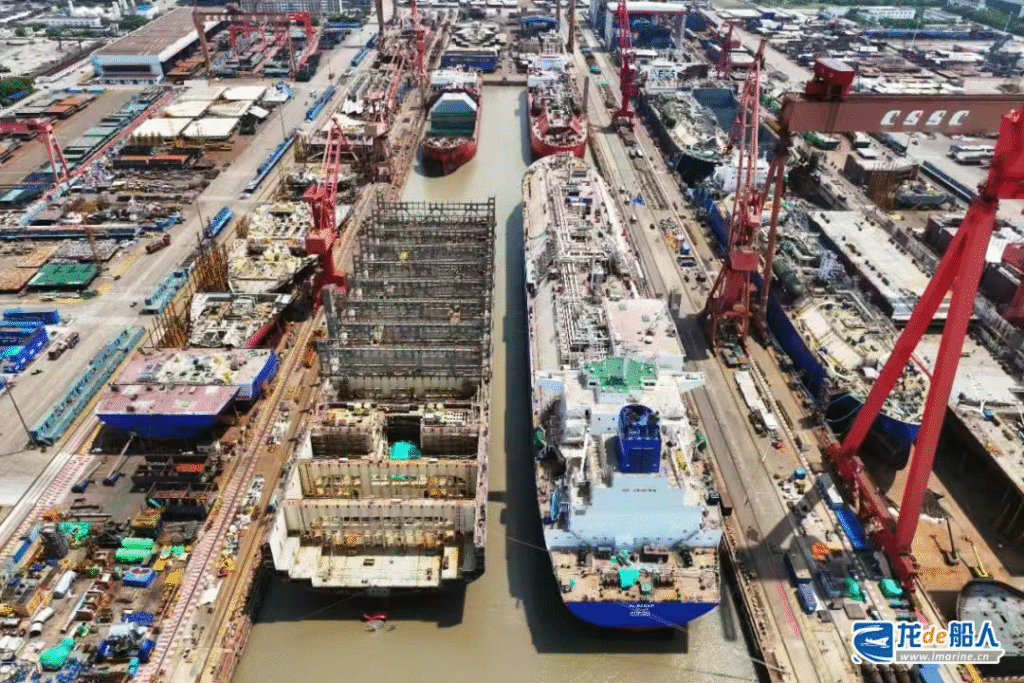
If you're trying to navigate this cycle as an owner or operator, the practical move isn't to wait for the layoffs to bottom out. It's to restructure your fleet deployment now while the yard capacity for repairs and conversions is still available at discounted rates. Yards that are understaffed still have their infrastructure. Dry docks are empty. The skilled welders and pipefitters are gone, but the overhead costs per berth have dropped significantly because the yards are desperate for any revenue. I've seen conversion timelines extend by six to eight weeks when you don't account for the relearning curve of a reduced workforce, but the cost savings on the conversion itself can be twenty-five to thirty percent lower than pre-2024 pricing. That math works if you have the patience. The biggest pitfall I see people fall into is assuming that laying off shore staff solves the cash flow problem. It usually doesn't. You cut the back-office functions that keep ISM and ISPS compliance in order, and then you spend more on external consultants to cover the gaps than you saved on salaries. A properly run ship management operation can trim fifteen to twenty percent off its cost base through attrition alone over a twelve-month period without touching the compliance team. Anything beyond that tends to create regulatory risk that costs more in the long run. Another nuance that isn't discussed enough: the pension and severance obligations from previous downturns are still on some companies' books. European and Japanese operators who took on additional pension liabilities during the 2021-2023 boom are now facing those payments while revenue is declining. This is one of those hidden cost drivers that shows up in annual reports as "other operating expenses" and nobody explains it. If you're doing due diligence on a distressed operator, pull the pension obligation line items and the severance accruals. They tell you more about sustainable solvency than the P&L does.
The maritime industry doesn't have a single boombust cycle. It has overlapping cycles at different stages depending on the vessel type and route. Tankers are in a different position than container ships, which are in a different position than dry bulk. LPG and LNG carriers are mostly insulated because of the energy transition investment pipeline. If you're making decisions based on aggregate industry data, you're probably making the wrong decisions. Break it down by segment. The layoffs in one segment don't predict the layoffs in another. They just look the same in a press release. What's left to say is basically this. The current cycle will normalize, but not the way the analysts on TV are saying. It won't be a quick bounce-back driven by renewed ordering. It'll be a slower contraction where the weaker operators get absorbed, the orderbooks stay lean for another couple of years, and the yards that survive do so by serving a smaller fleet more efficiently. The layoffs you're seeing now are just the visible portion of a much larger adjustment that's already underway. The people who understand that aren't the ones posting about it on social media. They're the ones quietly renegotiating contracts and conserving cash.