Getting Real Data From the Shanghai Stock Exchange
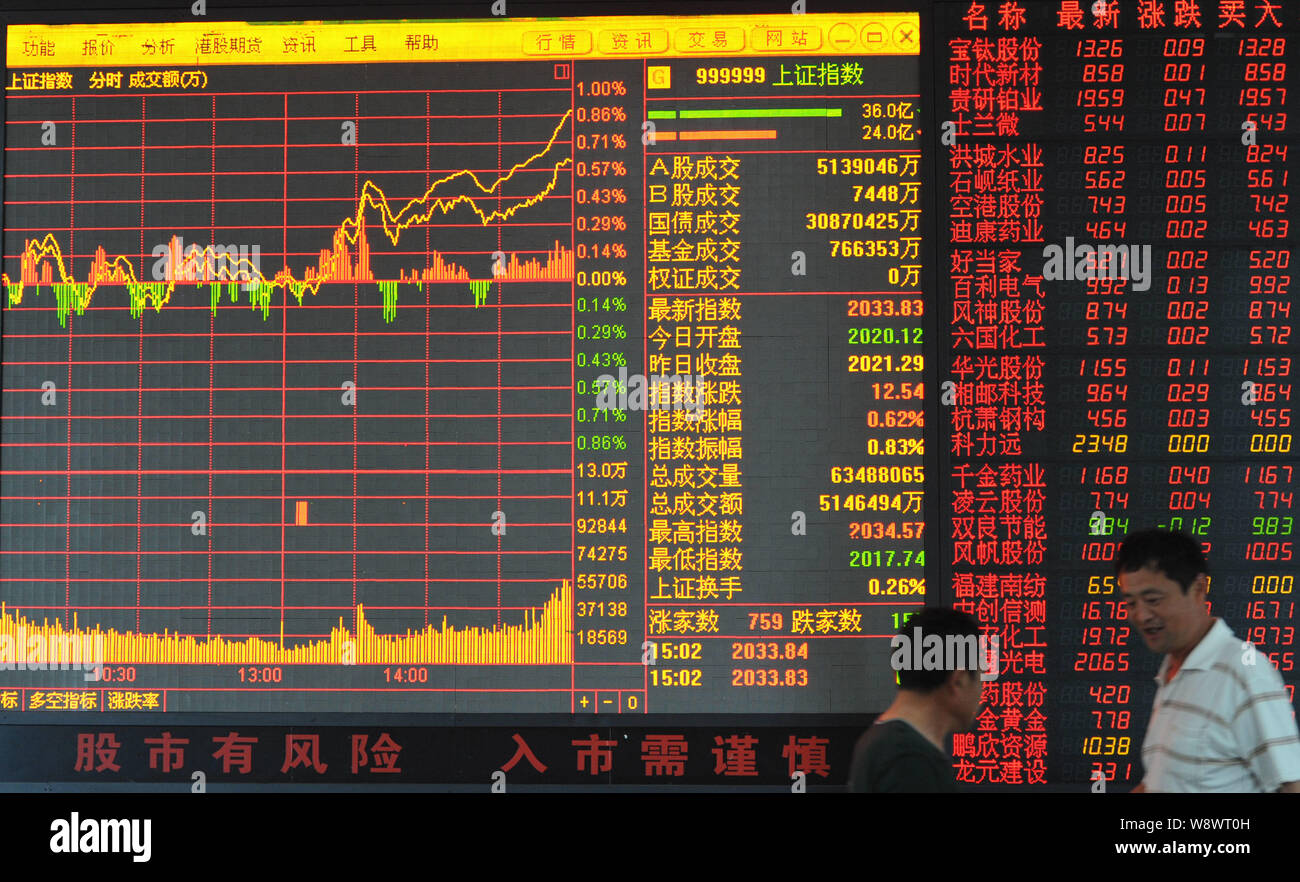
The Shanghai Stock Exchange data feeds aren't especially friendly to retail traders. The SSE offers a proper market data API called the Exchange Market Data Interface, but getting authenticated credentials requires going through a broker or financial institution with a formal agreement. Most people never make it that far because they get stuck on the licensing side. Instead, I ended up using third-party data aggregators that repackage SSE tick data with slightly different latency characteristics. For most traders looking at SSE Realtime Charts And Market Insights Power In Informing Trading Decisions, the practical path involves using platforms like Bloomberg, Wind, or even certain broker terminals that push SSE order book updates at sub-second intervals. The free tier options, like the SSE's own website data portal, give you delayed quotes—usually 15 minutes behind—unless you're paying for a professional feed. That gap matters more than you'd think when you're trying to catch intraday moves in illiquid A-share names.
How the Data Actually Arrives
SSE trades in two main sessions: 9:30 AM to 11:30 AM and 1:00 PM to 3:00 PM Shanghai time, with a call auction at 9:15 to 9:25 AM. The pre-market phase is where most price discovery happens for high-volatility names, and it's also where the order book gets most informative. If you're watching level two data, you're looking at ten price levels on both the bid and ask sides, updated every three seconds during continuous trading. During call auction, updates come at irregular intervals tied to order input. The symbols you'll see follow SSE conventions. Shanghai-listed A-shares use six-digit codes starting with 6. Bonds are 1, commodities are 2. ETFs and funds start with 5. Understanding this isn't just trivia—it's how you build screening logic without accidentally pulling liquidity from the wrong market segment.
Setting Up a Practical Monitoring Workflow
I built a basic monitoring system using Python with WebSocket connections to a data provider that supported SSE real-time feeds. The setup took roughly two weeks from start to functional alerting, depending on your familiarity with async programming and API authentication flows. Here's what actually worked. First, pick your data source. Wind Information is the dominant domestic Chinese financial data platform. It's expensive for individuals—easily several thousand dollars annually for proper market data access—but it covers SSE comprehensively with both level one and level two depth. For smaller operations, Tushare Pro offers a more accessible entry point with SSE tick-level historical data and reasonably current real-time quotes at a fraction of the cost. It has rate limits, though, so plan your polling strategy around those constraints rather than hammering the API. Second, structure your charting layer. I used mplfinance for candlestick rendering and plotly for interactive web-based dashboards. The key insight here is that mplfinance handles the SSE's specific candlestick semantics better than generic libraries—the 3% daily price limit on most A-shares means candles can look dramatically different from what US traders expect, and that compression of range needs to show up clearly in your visualization so you're not misreading volatility signals.
Get the Full Details

I learned this the hard way. In early 2023, I was watching a semiconductor A-share that had hit its daily limit-up for three consecutive sessions. My chart scale was auto-adjusting based on recent bars, which made the third limit-up day look like a minor 0.5% move compared to the previous session's full range. The stock wasn't consolidating—the entire visible price action was compressed against the upper band of the chart. I spent about twenty minutes manually adjusting the y-axis limits before realizing the issue was the scaling algorithm, not the data. Since then, I always set fixed axis ranges based on multi-day lookbacks rather than letting the library auto-fit.
What the Numbers Actually Tell You
Volume alone is almost meaningless without context on the SSE. Many A-shares trade heavily during the opening and closing call auctions, which inflates volume figures without reflecting genuine intraday participation. I started filtering out call auction volume separately and only analyzing continuous trading volume, which changed my read on half the stocks I was tracking. Names that looked actively traded were mostly seeing auction-driven volume spikes that meant nothing for momentum assessment. Turnover rate is the metric most traders in this space should be watching. A daily turnover above 5% on a large-cap Shanghai stock is unusual and worth investigating. Below 0.5% on mid-caps suggests genuine illiquidity that can make exit strategies a problem regardless of how good your entry timing is. The SSE publishes daily top turnover lists, but those rankings are often dominated by small speculative names that have no place in a serious portfolio. Price-to-book ratios on the SSE tell a different story than on other exchanges. State-owned enterprises in sectors like banking, telecommunications, and infrastructure frequently trade below book value for extended periods. This isn't necessarily a value signal—it can reflect structural issues with capital efficiency and governance—but it does mean traditional valuation screening needs adjustment when applied to Shanghai-listed stocks. A P/B of 0.8 on a Shanghai bank isn't the same situation as a P/B of 0.8 on a Nasdaq bank.
Common Pitfalls That Cost Me Money
The biggest mistake I made was assuming real-time means actionable in real-time. SSE data feeds from most commercial providers have latency between 200 milliseconds and 2 seconds depending on the path. By the time your chart updates, the opportunity you're looking at may already be priced in, especially on high-volume names. This doesn't mean real-time data is useless—it means you need to use it for monitoring and alerting rather than execution decisions on fast-moving stocks. Another issue is the treatment of halts. SSE suspends trading for companies with events—material announcements, restructuring news, regulatory investigations—without much advance warning. A stock can halt for hours or days, and when it resumes, the price gap can be substantial. My initial models didn't account for suspended instruments properly, which meant backtested performance figures included periods where the stock wasn't actually tradable. Once I added a suspension filter and excluded halt periods from position sizing calculations, the expected returns dropped noticeably on several strategies I'd been comfortable with. The T+1 settlement rule is another structural factor. You can buy shares during the day and sell them the next trading day, but you cannot sell shares you bought today. This matters for intraday strategies because it eliminates the ability to exit a losing position the same day after a bad entry. Stop-losses work differently when you're locked into a position until the next session opens. I had to redesign my risk management framework around this constraint, and it cut the number of viable intraday strategies down significantly.
What Works in Practice
The most reliable approach combines real-time charting with predefined alert thresholds rather than constant manual monitoring. Set alerts for volume spikes above two standard deviations of the recent average, for breakouts above or below key technical levels with confirmation from price action on the five-minute chart, and for unusual turning points in the order book imbalance ratio. This reduces screen time while keeping you informed of significant moves. For actual execution, use limit orders predominantly. Market orders on the SSE can slip considerably during volatile periods, especially on names with thinner order books. The spread between the best bid and best ask can widen unexpectedly when large orders hit the book, and slippage on a market order during those moments can eat into gains faster than you'd expect from the chart alone. Watch the northbound and southbound trading data if you're tracking cross-border flows. The Stock Connect program allows overseas investors to trade certain Shanghai-listed shares, and the daily net flow numbers published after market close provide information that sometimes precedes larger moves. This data isn't available in real time—it's published with a same-day delay—but it's one of the few structured signals that consistently correlates with subsequent price direction on liquid SSE names.
The platforms that handle this well tend to be institutional-grade systems, though several mid-tier options exist at lower price points. Professional terminals from providers like Refinitiv or local alternatives like East Money offer reasonable real-time charting capabilities at prices accessible to serious individual traders. Free browser-based tools work for casual monitoring but lack the depth and speed needed for active decision-making. Don't attempt to build a production system from scratch unless you have the engineering bandwidth and patience for the integration work involved. It usually takes most people two to four weeks to get something stable running, and maintenance is ongoing.
Shanghai Stock Exchange Realtime Charts And Market Insights Power Informed Trading Decisions
The core advantage of having real-time SSE data is the ability to react to market structure changes that standard delayed feeds miss. Order book imbalances, sudden volume surges, and limit-up or limit-down behaviors are the primary signals to watch. These events carry more information on the SSE than on many other exchanges because of the 3% daily price band and the predominance of retail participants, who tend to chase momentum more aggressively. Understanding that structural difference is what separates useful chart reading from decorative screen time. If you're serious about this, spend the first month just watching and recording what you see before committing any capital. Note the typical behavior of names you're interested in during different market conditions. Learn which stocks respect technical levels and which ones ignore them entirely. The exchange itself publishes daily summaries and statistics that are freely available and surprisingly useful for building context around the numbers you're seeing on your charts.