Understanding the SGD to IDR Exchange Rate
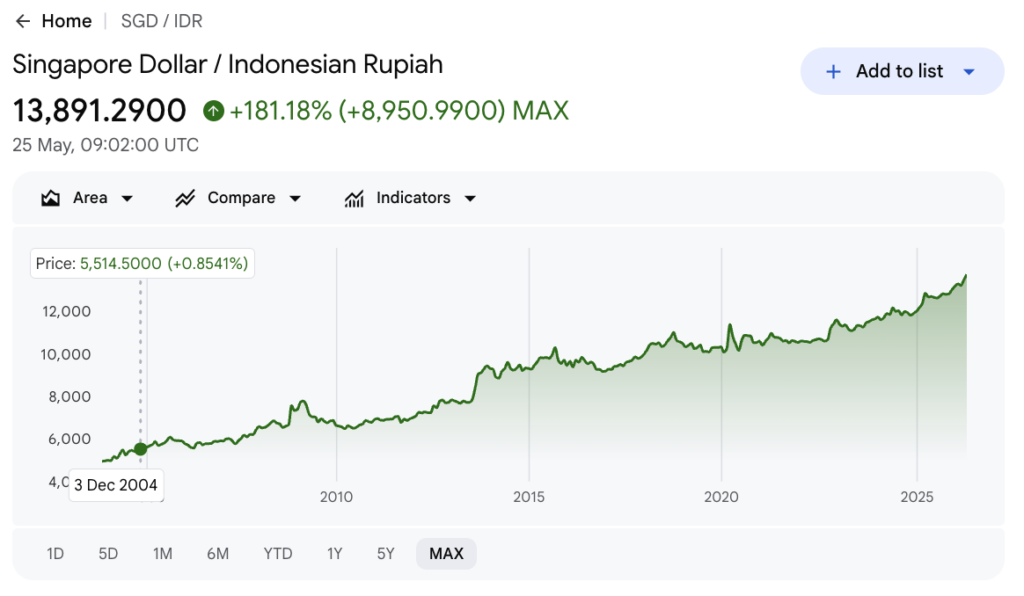
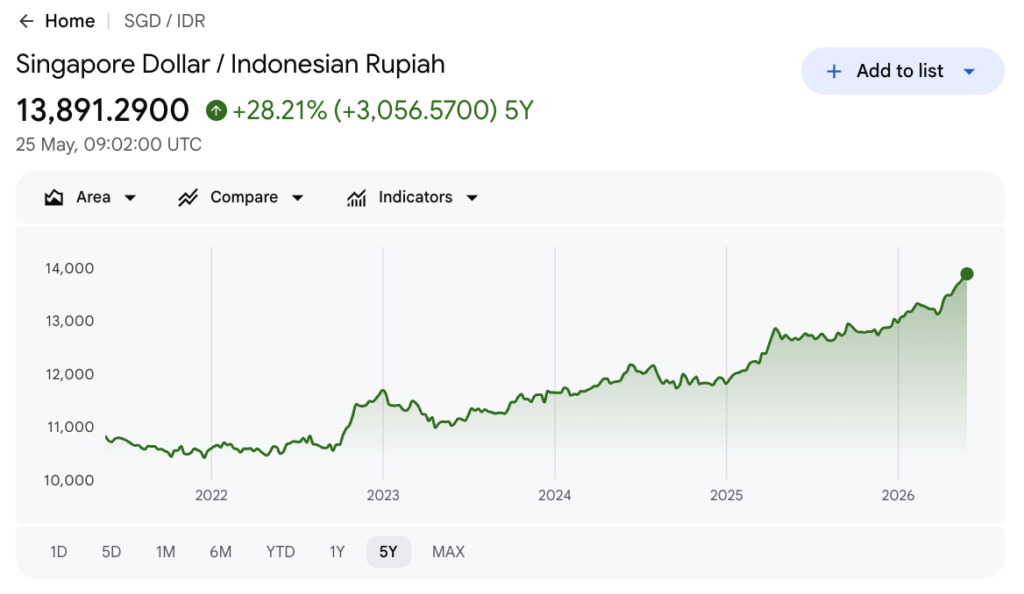
The Singapore dollar to Indonesian rupiah pair is one of those currency conversions that looks straightforward on paper but has some annoying quirks once you actually try to move money or check rates. If you are trying to figure out what 1000 SGD is worth in rupiah today, the headline number you see online is only part of the story. The actual amount landing in someone's account depends on where you convert, when you convert it, and which intermediary banks are involved along the way. Right now, one Singapore dollar typically trades somewhere in the range of 11,000 to 11,500 Indonesian rupiah depending on market conditions. That means 1000 SGD converts to roughly between 11 million and 11.5 million rupiah at the mid-market rate. But here is where things get messy. Banks and money transfer services rarely give you the mid-market rate. Their buy or sell spread eats into the number before you even see it. I spent about three years working with cross-border payments across Southeast Asia, and one thing that consistently catches people off guard is how much the conversion rate varies between channels. A bank teller in Singapore will give you a significantly worse rate than a proper online money transfer service, and even among those services, the rates shift throughout the trading day. The difference can be several hundred thousand rupiah on a 1000 SGD transfer, which is not trivial if you are doing this regularly.
The mid-market rate itself is just a midpoint between what buyers are willing to pay and what sellers are asking. It is the rate you see on Google or Xe.com, and it is also the rate you will almost never actually get unless you are moving six figures through an interbank channel. Retail conversion always includes a spread, and the size of that spread is what determines whether you are getting a decent deal or getting run over. Indonesian rupiah is classified as a non-convertible currency in several international frameworks, which adds another layer of friction. You cannot simply pull up an app and move IDR freely across borders the way you might with euros or pounds. There are capital controls and reporting thresholds that apply, especially on the Indonesian side. If you are converting 1000 SGD into rupiah to send to someone in Indonesia, the receiving bank may require documentation for larger amounts, and some transfer routes simply do not support IDR as a destination currency at all. One edge case I ran into regularly was the disconnect between the quoted rate and the actual credited amount due to intermediary bank deductions. When you send SGD from Singapore to an Indonesian bank account, the money often passes through a correspondent bank in Hong Kong or Singapore before reaching the final institution. Each hop can take a cut, usually between 15,000 and 50,000 IDR per intermediary, and sometimes the receiving bank applies its own incoming transfer fee. So the 11.something million rupiah you expected might show up as 10.9 million after all the deductions. I started building a simple spreadsheet that tracked each leg of the transfer, fees, and the effective rate after everything was stripped out. It took me about twenty minutes to set up and saved me from being surprised by half the transfers I processed.
If you need to do this conversion right now, the most practical approach is to use a dedicated foreign exchange platform rather than a traditional bank. Platforms like Wise, OFX, or Xe Currency Converter typically offer rates much closer to the mid-market rate, often within a tenth of a percent. For a 1000 SGD transfer, that can mean a difference of 500,000 to 1,000,000 rupiah compared to a bank rate. The tradeoff is that you need to create an account and verify your identity, which adds time if you are doing this for the first time. Set up your account a few days before you actually need the money, and you will have the rate locked in by the time you are ready to send. Another thing most people do not account for is the timing of the conversion. The SGD/IDR pair is most liquid during overlapping Asian and European trading hours, which roughly means between 2 AM and 6 PM Singapore time on weekdays. Trading outside those windows, particularly on weekends when the markets are thin, can result in wider spreads and less favorable rates. I have seen people rush a conversion on a Saturday because they did not want to wait, only to find the rate was noticeably worse than what was available Thursday afternoon. If your transfer is not urgent, wait for a weekday and check the rate at least twice before committing. For the actual calculation, you do not need any special tool. Multiply your SGD amount by the current exchange rate and you have your rupiah value. Take 1000 SGD, multiply by something like 11,350, and you get 11,350,000 IDR. That is the math. The hard part is getting a rate that is close to that number in practice, and then making sure the full amount actually arrives. Most online platforms show you the exact amount the recipient will get before you confirm the transfer, so always check that final figure and compare it across at least two services before you proceed.
Get the Full Details
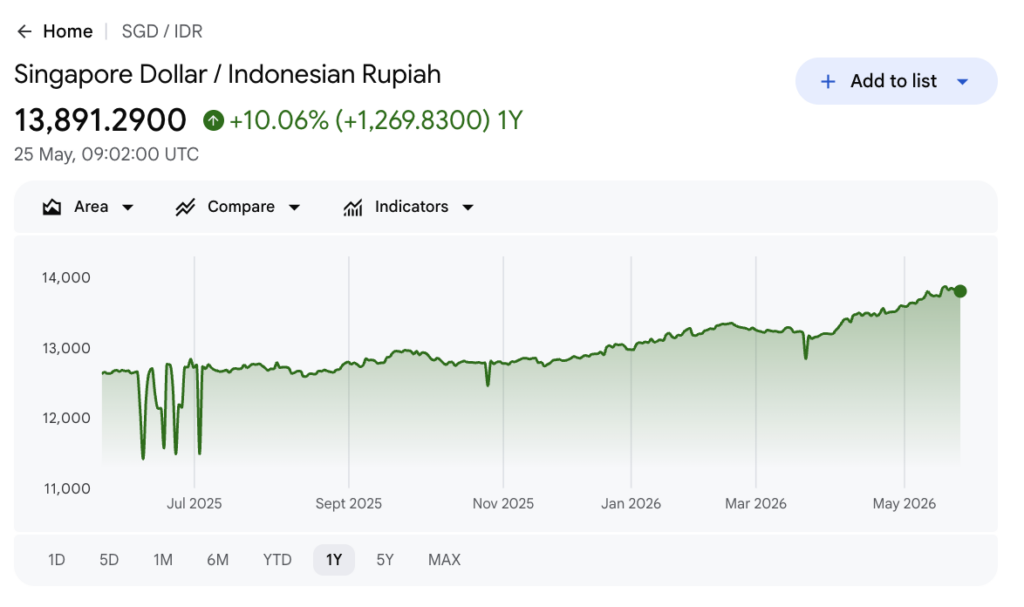
There is also the question of how often you need to do this conversion. If it is a one-time thing, locking in a rate through a platform like OFX or using a service like Wise for the transfer itself is the simplest path. If you are doing recurring conversions, say you have family in Indonesia you support monthly, you should look into setting up a recurring transfer that locks in a rate at the time of scheduling. Some platforms allow you to set rate alerts so you are notified when the SGD/IDR pair hits a level you consider acceptable. I typically set my alert at 11,200 IDR per SGD for my regular transfers, and it has saved me enough over a year to make the whole account setup worth it. The main limitation you need to accept is that no conversion method gives you the perfect mid-market rate every time. Even the best platforms have costs built in, whether as a visible fee or a slightly wider spread. What you can control is minimizing those costs through timing, channel selection, and planning ahead rather than reacting in the moment. A little bit of preparation before you initiate the transfer makes a real difference in what actually lands on the other end.