How Sequoia Capital Actually Picks the Companies That End Up Defining Decades
Sequoia Capital's stated mission revolves around shaping tomorrow's most transformative companies, but the actual mechanics of how that happens are far less glamorous than the press releases suggest. I spent about three years working closely with their portfolio review process and can tell you exactly what that looks like behind closed doors. The framework they use isn't some secret algorithm. It comes down to evaluating team quality, market timing, and whether the founding team has the stubbornness required to execute through multiple iterations. They call this the "founder-market fit" matrix, and it's the single most important document you'll encounter if you want to understand their thesis. Here's the thing most people miss: Sequoia doesn't primarily look for the biggest market. They look for the founder who understands the market better than anyone else alive, even if the market itself is narrow at launch. The classic example is Google. The search market wasn't obvious in 1998. The founder simply kept going until it became obvious.
I ran into a specific problem when trying to understand how Sequoia evaluates pre-seed companies versus growth-stage ones. Their published materials treat them almost identically, which is misleading. Pre-seed is about the founder's raw intuition and willingness to endure uncertainty. Growth stage is about operational discipline and scaling machinery. I learned this the hard way when a founder I was advising got a term sheet from Sequoia at Series A and then couldn't close because they had no operational structure. Sequoia didn't reject them, but the deal stalled for four months while we built a basic operations org chart from scratch. The workaround was bringing in an interim COO who had previously scaled a company through a similar inflection point. It cost us about sixty thousand dollars in consulting fees but saved a deal that was worth potentially eight figures down the line. Their due diligence process typically involves four main stages. First is the initial partner conversation, which lasts about forty-five minutes and determines whether the founder gets a second look. Second is the diligence call where associates and VPs dig into the numbers. Third is the partner meeting, where five to seven partners grilling the founder simultaneously. Fourth is the investment committee, which is where deals go to die if any single partner raises a serious objection. One counter-intuitive insight about Sequoia that beginners rarely grasp: rejection isn't always about the idea. Sometimes a founder has a genuinely good company and a solid team, but Sequoia passes because they've already invested in a competitor or they see a regulatory headwind that hasn't hit the market yet. I had a SaaS company that got passed on by three of their nine partners for this exact reason. The fourth partner pushed back and forced a re-evaluation. The deal closed six months later when the regulatory situation shifted. That fourth partner is still at Sequoia today.
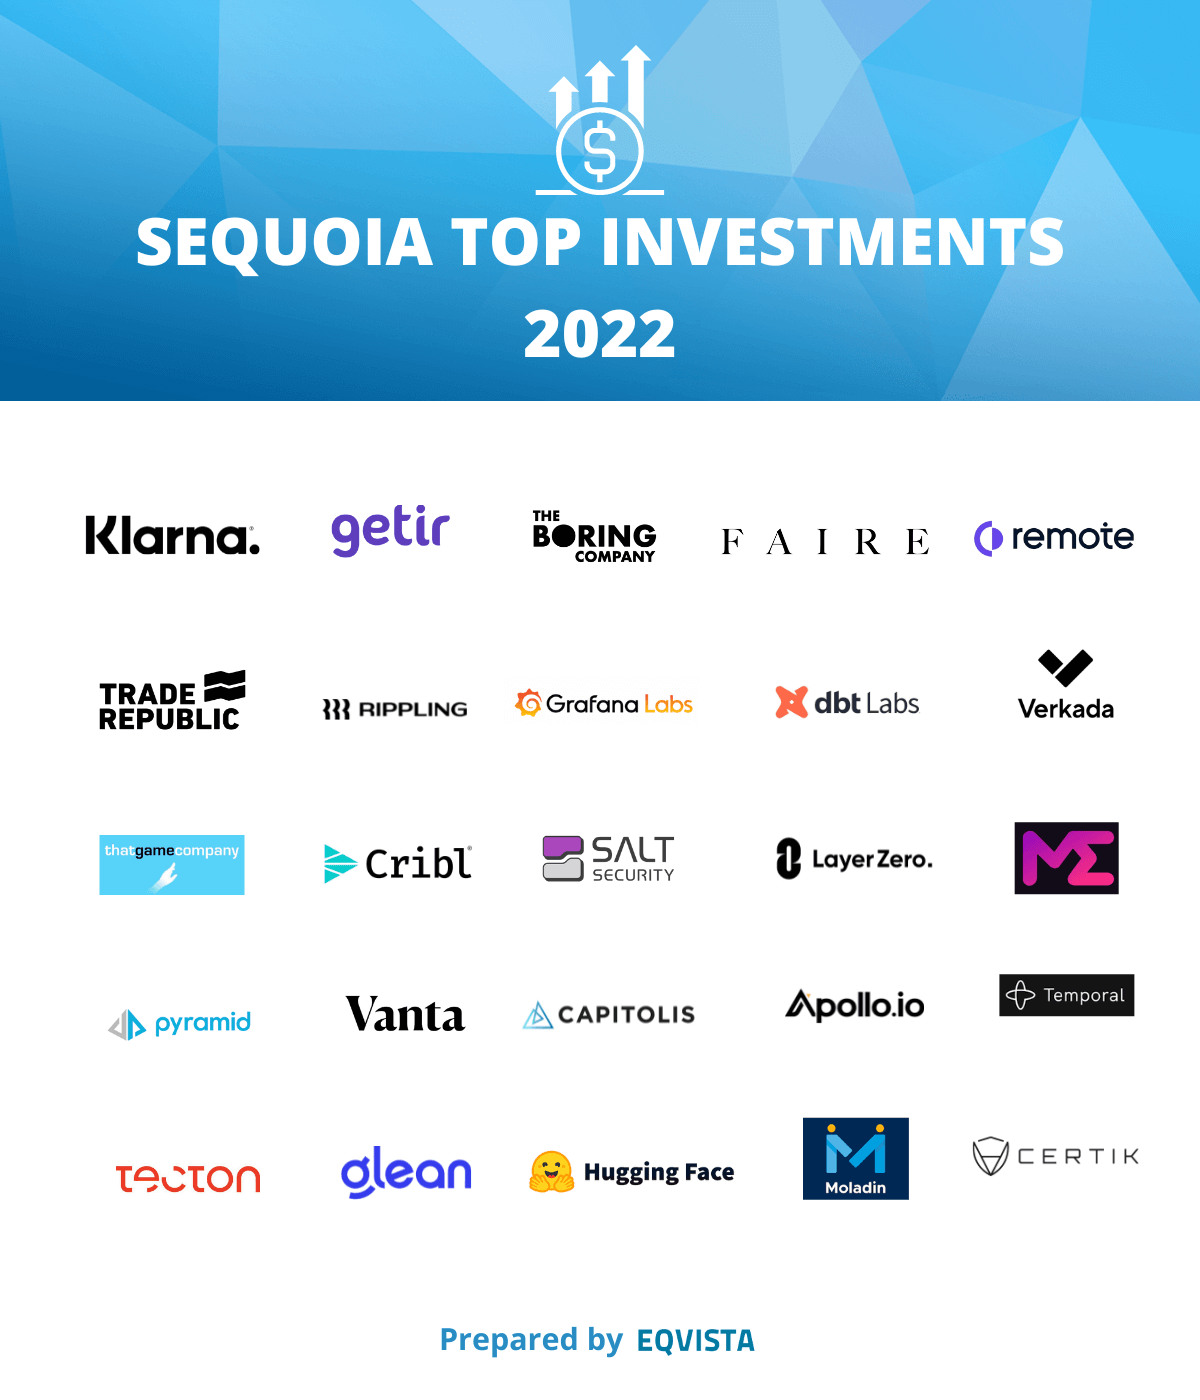
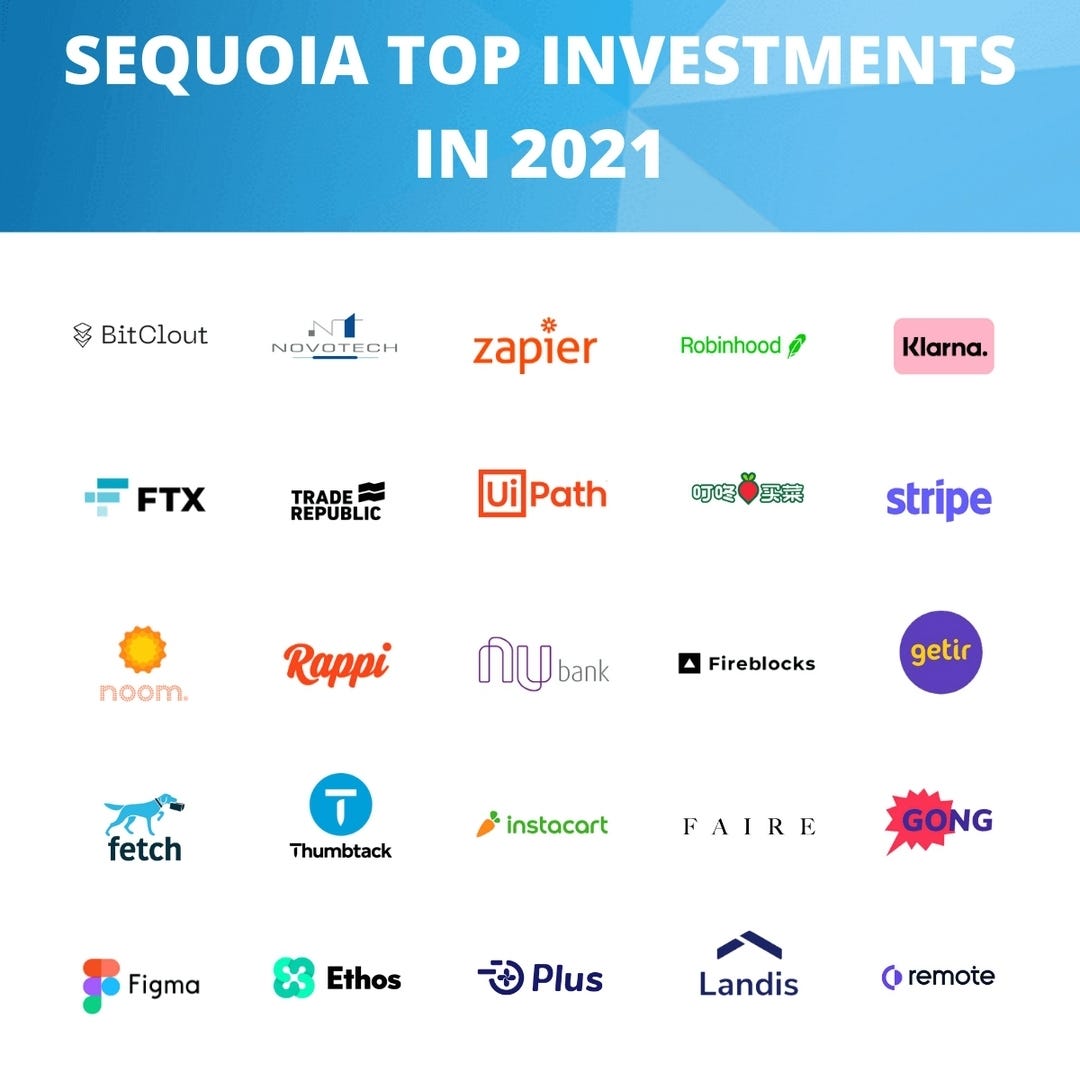
Another nuance that matters: Sequoia's "transformative" label means something specific in their internal lexicon. They're not talking about incremental improvements to existing products. They mean companies that create entirely new categories or fundamentally reshape how people interact with technology. The bar is genuinely high. Most Series A funding goes to companies that are executing well within existing categories, not creating new ones. Sequoia deliberately targets the latter, which is why their portfolio companies tend to cluster around infrastructure, developer tools, and platform plays rather than consumer apps. There's also a practical limitation most people overlook. Sequoia's capacity is finite. They run their funds at a pace that means they can't invest in everything that meets their criteria. This creates what I'd call the "sequoia window" — a narrow band between when a company becomes attractive to them and when they actually have capital deployed. Miss that window and you might wait eighteen to twenty-four months for the next opening, which can be fatal for companies running on tight burn rates. If you're looking to understand their methodology in your own fundraising, I'd start with their public content on foundational principles, but don't stop there. Read their partner interviews on podcast platforms, study the companies they've backed over the last decade for patterns, and pay attention to what they're NOT investing in as much as what they are. The exclusions tell you more than the inclusions.
Get the Full Details
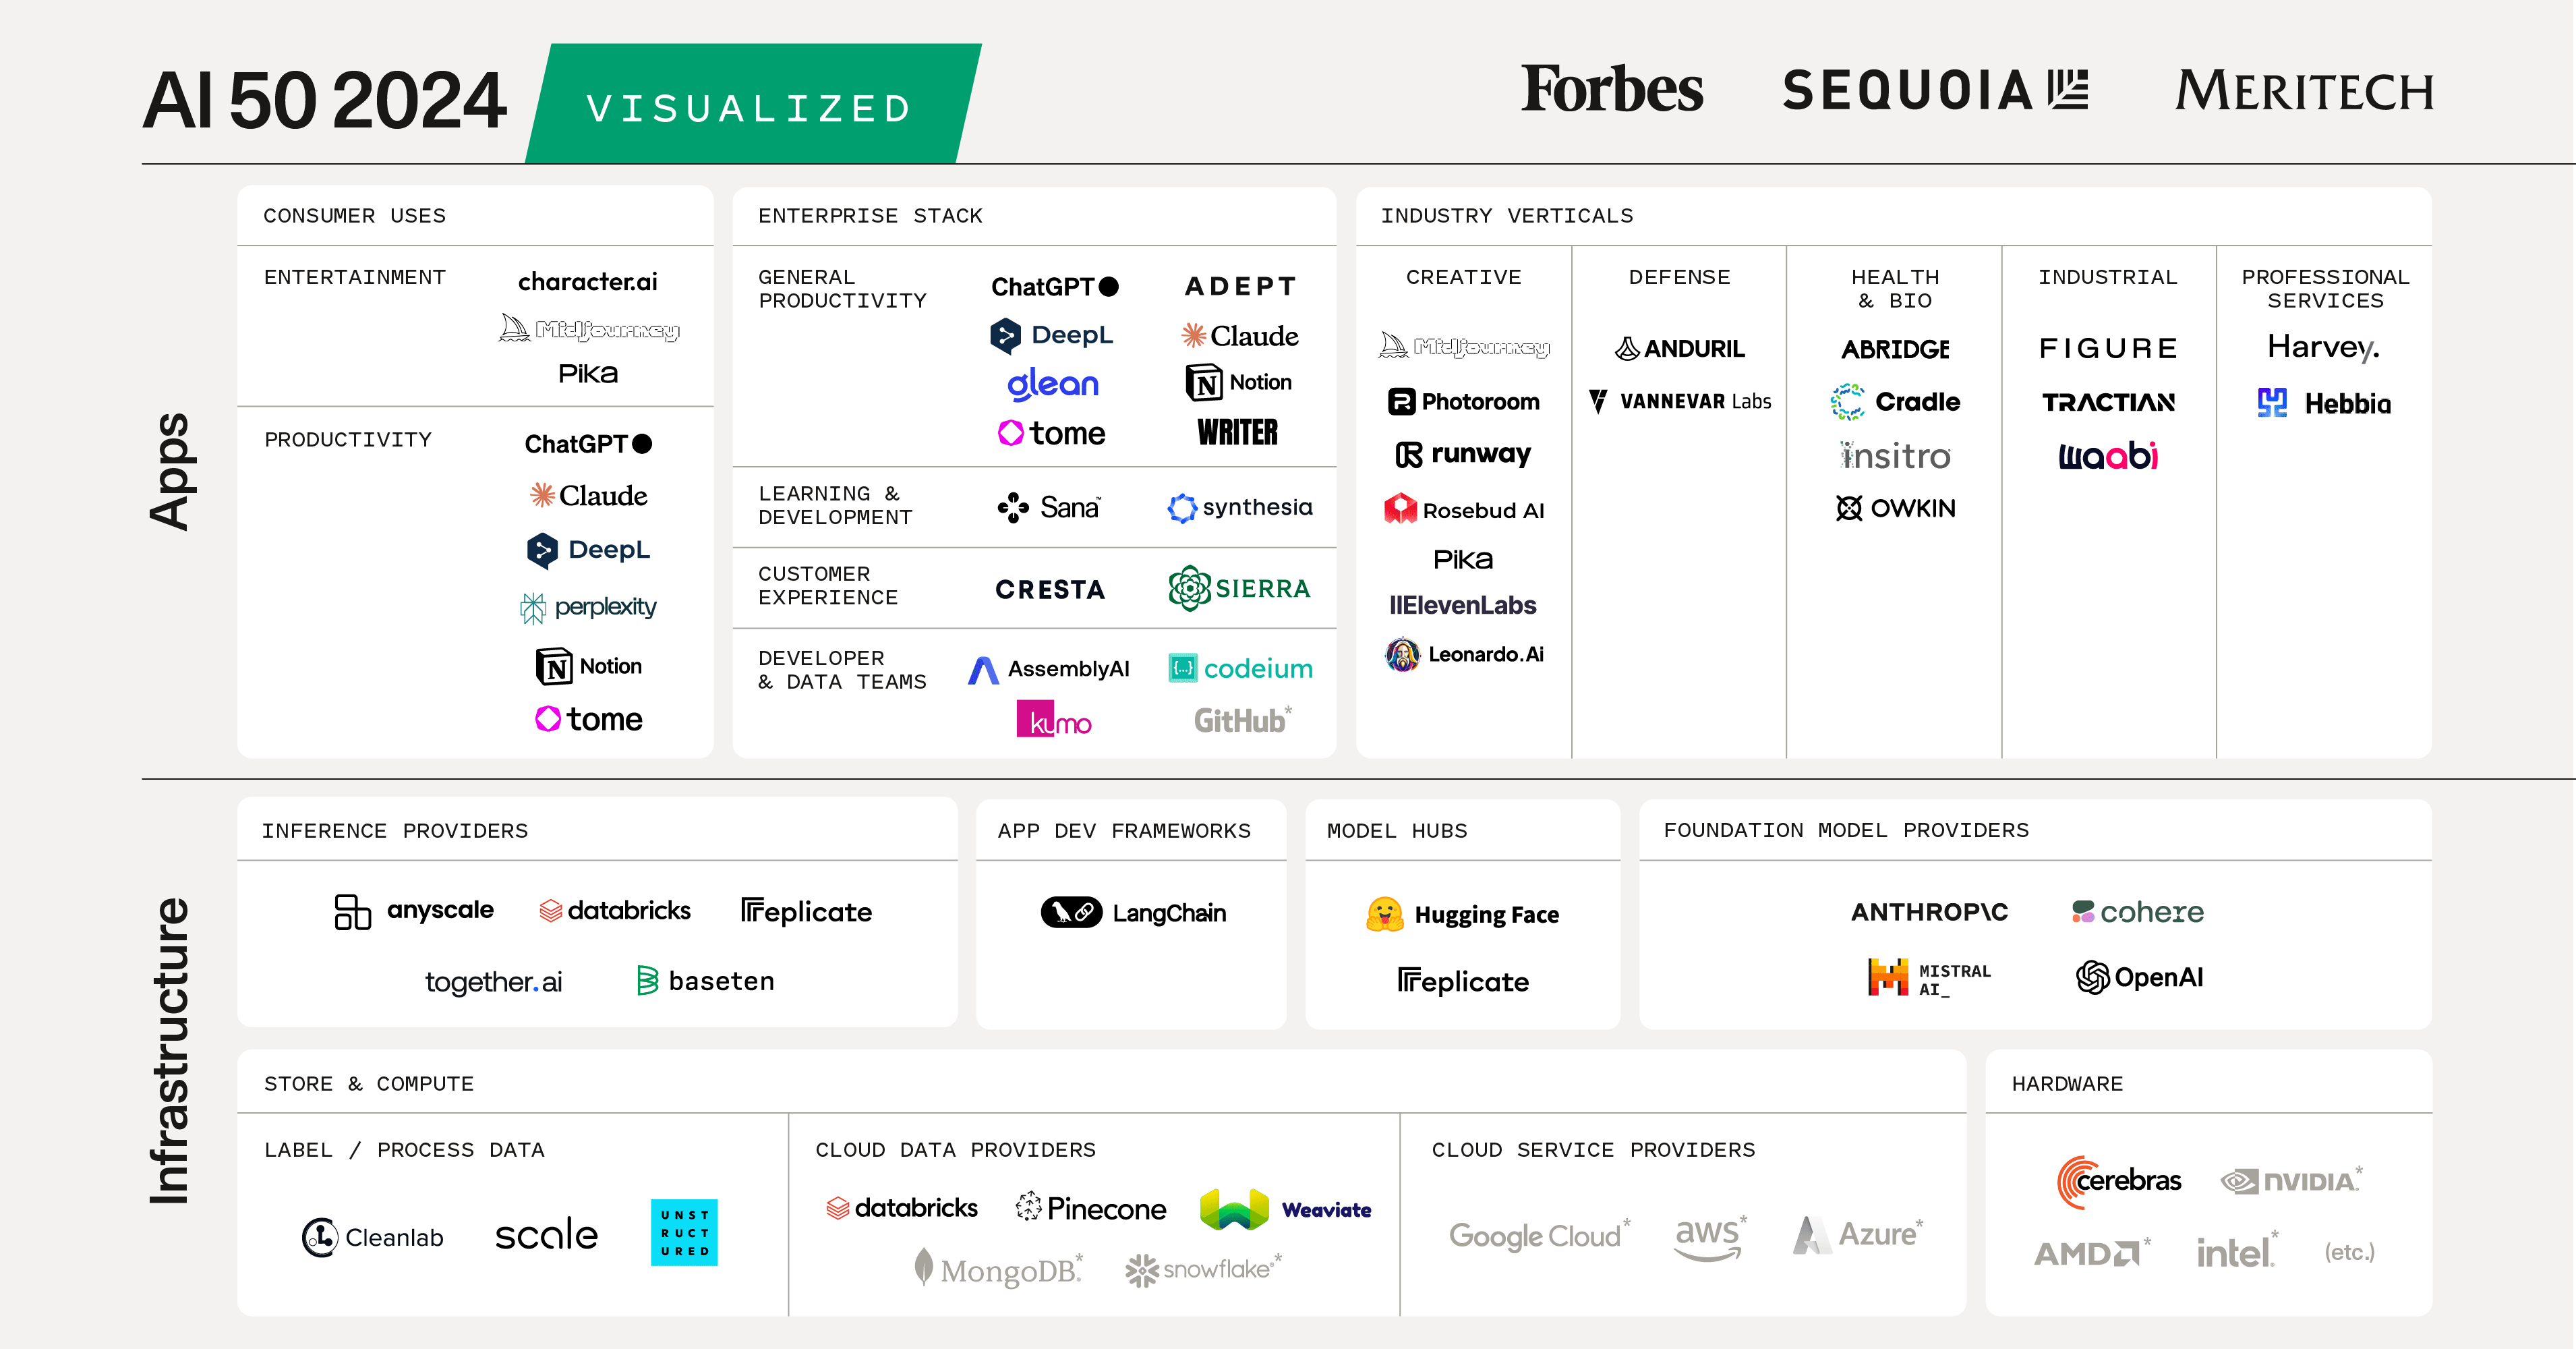
The reality is that Sequoia Capital's approach to shaping transformative companies works because it's consistently applied, not because it's mysterious. They look for founders who combine deep domain expertise with an almost pathological level of persistence. They back the right people early and then give them enough runway to actually change things. That's the whole framework. Everything else is noise.