Western Union doesn't make it easy to actually understand your options until you've gone through the motions a few times
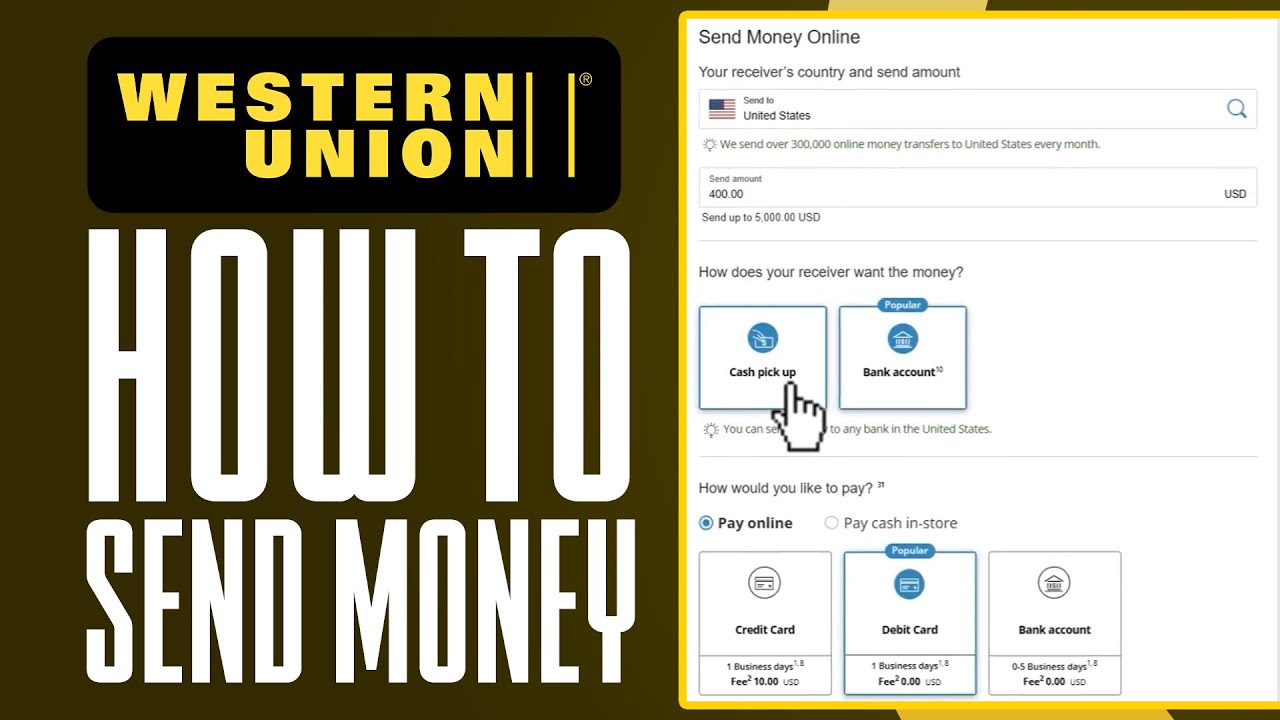
I've been moving money internationally for over a decade now. Western Union is one of the tools I reach for when the situation demands speed over cost. The website is cluttered. The app is better but still not intuitive. Here's what actually works. Western Union offers several ways to send and receive money, and mixing them up will waste your time. The main branches are bank deposit, cash pickup, mobile wallet, and card delivery. Each has different cut-off times, limits, and fees that aren't always visible until you're three steps into a transaction. When you go to westernunion.com, the homepage throws everything at you at once. Cash pickup is default. Bank deposit is hidden under "more options." Mobile wallets only appear if you're sending to a country where they're available. I learned this the hard way.
Bank Deposit puts money directly into the recipient's account. It's usually faster than cash pickup because there's no agent verification bottleneck. Fees are lower too, often around 5 to 10 percent less depending on the corridor. The catch: the recipient needs an active bank account at a participating institution, and not all banks in developing countries qualify. I sent money to a cousin in the Philippines who used a local cooperative bank. It went straight to his account in under 10 minutes. The same transfer to a different bank in Vietnam took 4 hours because that particular bank processes Western Union settlements in batches at 2 PM local time. Cash Pickup is the classic option. The recipient walks into any agent location with a reference number and ID. Good for people without bank accounts. Bad for everyone else because the fees are higher and the exchange rates are worse. A typical $500 transfer might cost you $25 at the counter versus $18 for bank deposit on the same route. The difference compounds quickly if you send regularly. Mobile Wallet covers products like M-Pesa in Kenya, GCash in the Philippines, and bKash in Bangladesh. This is honestly the best option if the recipient has one of these. Money lands in the app within minutes, fees drop by another few dollars, and the recipient can spend it immediately or withdraw at an agent. Availability is the real limiter though. It only works for specific countries and specific wallet providers. Pick the wrong one and the transaction will sit in limbo while you figure out why.
Card Delivery ships a prepaid debit card to the recipient's address. Useful when you need someone to have ongoing access to funds rather than a one-time pickup. Turns out this is rarely the right choice for what most people actually need. Setup takes 1 to 2 weeks. Annual fees apply. It's a niche product masquerading as a mainstream option.
Get the Full Details

The things nobody tells you upfront
Exchange rates at Western Union are not competitive. They build their margin into the rate they give you, not just the displayed fee. On a $1,000 transfer to Mexico, the fee might look like $15, but the exchange rate could be 3 to 4 cents worse than the mid-market rate. That's another $30 to $40 hidden in the conversion. If you're sending money for someone who needs it to live on, that matters. If you're reimbursing a business expense, it matters less. There's a workaround. Check the amount the recipient actually gets before you confirm. Western Union shows this on the review screen. Compare it to what you'd get from a service like Wise or Remitly on the same corridor. Sometimes the gap is small. Sometimes it's enormous. I stopped guessing and started doing the comparison every single time. Another thing: promo codes and first-time sender discounts are real but poorly advertised. Western Union occasionally runs campaigns that drop fees to near zero for new accounts. I found one last year that cut a standard transfer from $22 to $4. You have to create a new account to use it, which means verifying your identity again. I maintain a second account for exactly this reason. It's not elegant but it works.
The app has a feature called Scheduled Send that lets you lock in an exchange rate for up to 30 days. Useful if you know you'll need to send money on a specific date and the currency is volatile. I used this when sending funds to Pakistan during a period of sharp rupee fluctuation. Locked the rate on a Monday, sent it the following Friday, saved roughly 6 percent compared to sending without the lock. Not every corridor supports this. The app will tell you if it's available for your specific destination.
Edge cases and workarounds
I hit a wall once trying to send money to a recipient in rural Ethiopia. The app showed cash pickup was available, but when the recipient went to the agent location, they were told the specific office didn't have enough cash on hand for the amount I sent. The system showed available funds. The agent didn't. This happens more often than you'd think with smaller agent locations, especially in areas with high transaction volume. The fix was switching to mobile wallet delivery to a TeleBirr account, which was newly launching at the time. The money arrived instantly and the recipient could withdraw from any partner merchant. It took me three attempts and two phone calls to Western Union support before they'd even consider routing to a different delivery method. Support is better through the app chat than the phone line. Phone queues are long. Chat agents can see the same dashboard tools that a human would need to diagnose routing issues. Another problem: name mismatches. If the sender name on your ID doesn't exactly match the name on the account, the transfer gets flagged. I once spent 45 minutes on hold because my middle name appears on my passport but not on my driver's license, and the system required an exact match. The workaround was updating my profile with both IDs before initiating the transfer. Do this before you need it.

When Western Union is the wrong tool
Western Union excels at speed and physical agent access. It fails at cost efficiency and transparency. If you're sending more than $1,000 regularly, or if you're a business moving payroll or vendor payments, the cumulative fees and poor exchange rates will eat into your budget significantly. Services like Wise, Revolut, or even traditional bank wire transfers become cheaper at scale. If the recipient has a bank account in a well-connected country, Western Union is often the worst option financially. If the recipient is in a remote area with no banking infrastructure, it might be the only viable option. Know which situation you're in before you start the transaction. The mobile app is consistently better than the desktop site. Fewer pop-ups, clearer navigation, faster processing. Download it. Set up your account, verify your identity with both a government ID and a selfie verification, and keep it ready so you're not doing that mid-transaction when you need to send money urgently. Verification can take anywhere from 10 minutes to 3 business days depending on document clarity and current backlog.
Quick reference for common routes
Mexico to US: bank deposit is fastest and cheapest. Expect 15 minutes and fees around 2 to 3 percent. Philippines to US: mobile wallet to GCash or Maya is the best path. Under 10 minutes, fees around 2 percent. India to US: bank deposit works well for major cities. Tier 2 and tier 3 cities may have agent cash availability delays of several hours.
Africa to US: varies wildly by country. Mobile wallet where available. Cash pickup elsewhere, but verify agent capacity before sending large amounts. Latin America cash pickup: widely available but exchange rate markup is consistently higher than bank deposit. Budget an extra 1 to 2 percent for the convenience. There's no single right answer. The right choice depends on the corridor, the amount, the urgency, and the recipient's actual access to banking or mobile infrastructure. Western Union covers a lot of ground but does it unevenly. Knowing where it works and where it doesn't is the difference between a smooth transfer and a two-hour customer service call.