The Actual Process
You link your PayPal account to Xoom, add your bank details on the receiving end, and push the money through. That's the surface version. Here's what actually happens behind the scenes, and where people typically run into problems. The first step is making sure your PayPal account has a verified bank account or card attached to it. Xoom doesn't pull from your PayPal balance directly in all cases — it depends on which funding source you select during checkout. If you're sending to a bank account in the US, you can use PayPal as the funding source, and Xoom will move the funds from your PayPal balance or linked bank to the recipient's bank. International transfers work similarly but involve currency conversion and different routing. I've done this dozens of times across different countries. The interface makes it look simpler than it actually is. When I first tried sending to a bank in the Philippines, Xoom gave me two different exchange rates depending on whether I used my PayPal balance or a linked card. The PayPal balance rate was noticeably worse. That took me three attempts to figure out. Always compare the total amount the recipient will actually receive before confirming.
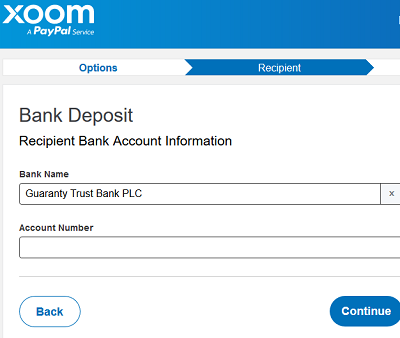
Here's the workflow that works: log into Xoom, select "Bank Account" as the delivery method, enter the recipient's full legal name exactly as it appears on their bank account, add the bank routing and account numbers, choose PayPal as your funding source, and review the exchange rate and fees before hitting send. The confirmation screen shows you the exact amount that will arrive and when. Standard bank transfers through Xoom typically arrive in 3 to 5 business days for domestic sends and 1 to 5 days internationally, depending on the destination country and the receiving bank's processing speed. One thing nobody tells you upfront: Xoom charges different fees based on your funding method and the destination country. Paying with a PayPal balance usually costs less than using a linked debit or credit card. Credit cards trigger cash advance fees from your card issuer in addition to Xoom's own fee, which is why experienced users avoid that route entirely. Also, some banks won't accept incoming transfers from digital remittance services like Xoom without additional verification. I learned this the hard way when a transfer to a credit union in Texas got held for three extra days because the receiving bank flagged it as an unfamiliar source. If you're moving large amounts regularly, consider whether Xoom is still the right tool. The per-transaction fees add up quickly compared to ACH transfers or wire methods. For amounts over a few hundred dollars sent frequently, a direct bank-to-bank approach through your own banking app usually comes out cheaper. Xoom is designed for convenience, not volume. That's a distinction worth keeping in mind before you commit.