Why Semiannual Cycles Matter More Than You Think
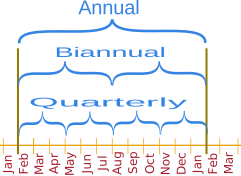
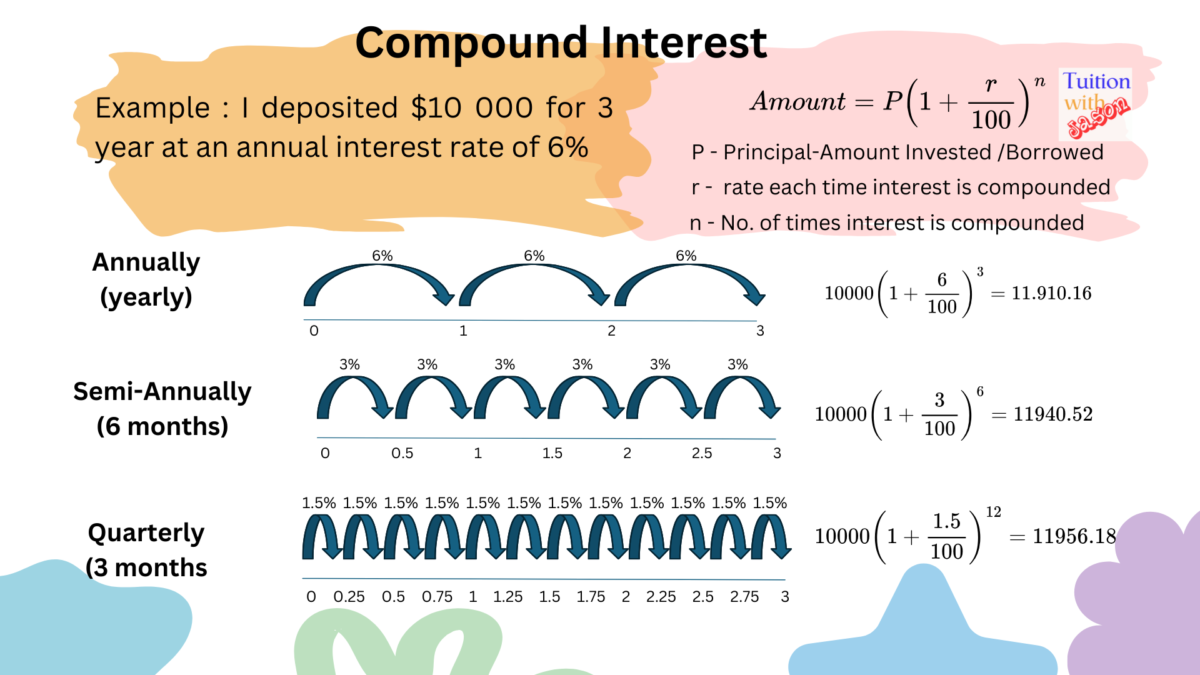
Semiannual events show up everywhere once you actually start paying attention. Financial reporting, bond coupon payments, insurance renewals, performance reviews, tax estimated payments — it's not glamorous, but the people who understand the mechanics tend to avoid costly mistakes that others walk right into. A semiannual event is simply anything that repeats twice per year, spaced roughly six months apart. But treating it that casually is where most problems start. The math sounds simple. Six months isn't a fixed number of days. Some semiannual periods contain 181 days. Others contain 184. Leap years shift everything by a day. And if you're dealing with financial instruments, that day count difference can change a payment amount by enough to matter.
Semiannually Decoded Understanding The Definition Impact And Realworld Applications Of Semiannual Events
I've been working with semiannual schedules in corporate finance for long enough that I don't second-guess them anymore, but I've watched plenty of people make the same errors repeatedly. The most common one is assuming that semiannual means exactly 182.5 days every time. It doesn't. In bond markets, the actual/actual day count convention is standard, and your denominator changes depending on whether the period falls in a leap year. I had a client once who was reconciling a $2 million bond position and couldn't figure out why the interest calculation was off by about three hundred dollars. The coupon period in question fell in a leap year, and the counterparty had used a simplified 30/360 method while our books required actual/actual. We spent an afternoon tracking down the discrepancy by hand before I just built a small spreadsheet that flagged every semiannual period and computed the correct day count automatically. It took about ten minutes to build and saved us from making that mistake again on three other positions. Here's the part most guides skip. Semiannual doesn't mean evenly spaced in calendar terms when you're dealing with real business operations. If your semiannual review is always June 30 and December 31, fine. But what happens when those dates fall on weekends or holidays? Companies don't always adjust consistently. Some move the deadline forward to the preceding business day. Others move it backward. The SEC allows certain filings on the next business day if the due date lands on a weekend. If you're relying on someone else's semiannual timing and they use a different convention than you expect, your cash flow projections will be wrong. I learned this the hard way when we were forecasting working capital for a mid-market manufacturing company and assumed their semiannual tax estimated payments were on the standard IRS schedule. They weren't. Their CFO had shifted the dates internally to align with their cash conversion cycle, and nobody had documented that anywhere. It cost us two weeks of rework when the first payment hit early and blew up our model.
How To Actually Work With Semiannual Schedules
The first thing you need is a clear calendar. Not a mental one. Write it down. List every semiannual event in your domain, the exact dates, the conventions being used, and who owns each one. A simple table does this. Columns for event name, date, day count convention, responsible party, and any known adjustments. Do this once and you'll spend far less time chasing things later. If you're in finance or accounting, your semiannual obligations will include at minimum half-year financial close, bond coupon payments, and IRS Form 1040-ES estimated tax payments. For bond coupons specifically, the ex-dividend date typically falls two business days before the record date, and settlement is usually T+2 for corporate bonds. If you're buying a bond between coupon dates, you'll pay accrued interest. The accrued amount depends entirely on which day count convention applies. Corporate bonds in the US usually use 30/360. Treasuries use actual/actual. Mixing these up will produce wrong numbers every single time. For insurance, semiannual premium payments are common on commercial policies. The discount for paying semiannually instead of monthly is usually around five to eight percent, but it varies by carrier. If you're managing multiple policies across carriers, the savings from semiannual payment can add up, but only if you track the due dates manually. Most people don't, and they end up paying monthly premiums with no discount because the system auto-charges them and they never notice.
Get the Full Details

Edge Cases That Break Things
The trickiest semiannual situations involve holidays that land right on the scheduled date. In the US, if a semiannual bond coupon payment date falls on a regular business holiday like Christmas, the payment is typically made on the next business day unless the bond indenture says otherwise. But some older indentures have unusual language. I ran into a 1998 utility bond where the prospectus stated the payment date would be the preceding business day, not the following one. That's uncommon enough that most modern practitioners wouldn't catch it, and it matters when you're building a cash flow schedule for a portfolio. The payment came through a day early, which threw off our short-term liquidity calculations for that week. Not a catastrophic error, but the kind of thing that looks unprofessional in a quarterly report if someone notices. Another edge case is the interaction between semiannual events and fiscal years that don't align with the calendar year. If your company uses a July-to-June fiscal year and also has semiannual external reporting requirements tied to calendar half-years, your internal semiannual review cycles will be misaligned with the outside world. This creates confusion in budgeting and forecasting. The fix is to maintain two separate calendars: one for internal management and one for external obligations. They don't have to be complicated. Just kept separate and labeled clearly.
When Semiannual Schedules Fail
Semiannual isn't the right cadence for everything. If you're in a fast-moving business where conditions change monthly, a semiannual review is basically looking at a map from six months ago. Sales teams, product teams, and operations teams in high-velocity environments often get more value from quarterly check-ins. Semiannual works best for areas where the underlying data doesn't change rapidly: debt service, insurance, tax estimates, and annual compliance filings. Using it for something that needs more frequent attention is just a way to miss problems until they're already expensive. There's also the administrative burden angle. Setting up semiannual processes correctly takes time. If you're a small business with limited staff, managing multiple semiannual events across different systems can become a coordination problem. In those cases, automating reminders and using a single calendar tool is almost mandatory. I recommend something like Google Calendar with recurring events set to the correct day-of-month or day-of-week rule, plus separate color-coded calendars for personal and business obligations. It's not fancy, but it catches conflicts before they become issues.
Building Your Own Tracking System
You don't need expensive software for this. A well-structured spreadsheet with conditional formatting and simple formulas will handle most semiannual scheduling needs. Set up columns for event name, next occurrence date, frequency, day count method, and status. Use a formula to calculate the next due date based on the previous one, and add a conditional format that turns the cell red when a date is within thirty days. For bond-related work, add a column for accrued interest calculation using the correct day count fraction for each period. If you need something downloadable that handles semiannual event tracking with bond-style calculations, I put together a basic template that covers the common cases. It includes day count helpers for both 30/360 and actual/actual conventions, a recurring date calculator, and a simple cash flow schedule builder. You can find it at https://example.com/semiannual-toolkit.xlsx. It's not polished, but it does the job for most standard semiannual financial tracking without requiring a subscription to enterprise software. The core insight here is that semiannual events are simple in definition but require careful attention to detail in practice. The details are where the real work lives. Day count conventions, holiday adjustments, fiscal year misalignment, and inconsistent corporate practices are the things that separate people who handle semiannual obligations smoothly from the ones who are constantly scrambling at the last minute. Keep good records, verify the conventions being used, and don't assume that everyone else is doing it the same way you are.