Logging Into Your Edward Jones Account: What Actually Happens
I have spent more time than I care to admit navigating Edward Jones portals, dealing with two-factor authentication glitches, and trying to figure out where the hell my portfolio allocation is showing up in the mobile app versus the desktop interface. The process itself is straightforward enough on paper. You go to edwardjones.com, you click sign in, you enter your username and password, maybe you have a code sent to your phone if you enabled that layer of security, and then you are in your account dashboard. But the devil is in the details, and most people never really learn what their account actually gives them access to beyond checking their balance. Let me walk you through the actual experience of managing money through Edward Jones, including the stuff they do not tell you in marketing materials.
Securing Your Financial Future With Confidence The Power Of Edward Jones Account Login
The login system itself is built on a multi-factor authentication framework that is standard across most major brokerage firms. When you create your account, you get a username that is typically your email address or something you choose. Your password needs to meet certain complexity requirements. After that, you have the option to set up additional verification layers like push notifications to the mobile app or SMS codes. I recommend enabling all available security measures, even though it adds a couple of seconds to every login attempt. Here is something most beginners miss. The session timeout on Edward Jones is actually quite aggressive compared to some other platforms. If you leave your browser open for about fifteen minutes without any activity, you will be logged out automatically. This is a security feature, obviously, but it gets annoying when you are trying to research a holding and end up getting kicked back to the login screen mid-research. The workaround I use is to keep a separate browser window open just for browsing the site while I do actual trading in another window, so I never trigger the timeout on my main session. The actual dashboard gives you access to several core functions. There is the portfolio overview, which shows your current positions, cost basis, and unrealized gains or losses. Then there is the trade execution interface, which supports market orders, limit orders, stop orders, and stop limit orders. You also have access to research tools, including analyst ratings, financial statements, and some proprietary research from Edward Jones analysts. The reporting section lets you download tax documents, transaction histories, and portfolio statements in various formats.
What People Get Wrong About Edward Jones Accounts
The biggest misconception I see is that Edward Jones is purely a full-service brokerage for wealthy clients. That was partially true twenty years ago, but the landscape has shifted dramatically. Now they have a tiered model where you can use the platform independently with minimal advisor involvement, or you can have a dedicated financial advisor who holds recommendations over you. The login experience is essentially the same regardless of which path you chose. Another common misunderstanding involves the fee structure. If you are an active trader placing multiple orders per month, the per-trade fees can add up faster than you expect. A standard equity trade runs about seven dollars on their basic platform, though this varies by order type and account size. Compared to zero-commission brokers, you are paying a premium, but that premium theoretically buys you access to human advisors and research that discount platforms do not provide. Whether that value proposition is worth it depends entirely on how much you actually use those services. I encountered a specific edge case last year that illustrates this perfectly. I had a client who was trying to set up a recurring investment schedule directly through the online portal. The interface does not natively support automated recurring purchases the way some newer fintech platforms do. The workaround I found was to set up manual calendar reminders and simply execute the purchase on the same day each month, or to contact their service team and ask about setting up automatic withdrawals from a linked bank account that would fund the purchases. Neither option is as seamless as a true automated system, but it gets the job done.
Advanced Account Features You Should Know About
Beyond the basic login and dashboard functions, Edward Jones offers several features that power users should understand. There is the cash management account, which is essentially a sweep vehicle for uninvested cash in your brokerage account. It earns a variable interest rate that changes with Fed policy, and it links directly to your checking account for easy transfers. The effective annual percentage yield they advertise is always based on the current rate, which means it will fluctuate, sometimes significantly, over time. The 529 plan options are another area worth exploring if you have children or plan to have them. Edward Jones manages several state-specific 529 plans, and the login portal gives you access to enrollment forms, contribution scheduling, and investment allocation changes within those plans. The tax implications vary by state, so it is worth understanding whether your state offers a deduction for contributions before you commit to a particular plan. Retirement account management through the portal covers traditional IRAs, Roth IRAs, SEP IRAs, SIMPLE IRAs, and 401(k) rollovers if you have one from a previous employer. The conversion process between Roth and traditional is particularly important to understand correctly, because doing it wrong can create a taxable event you did not intend. I always recommend consulting with a tax professional before executing any conversion, regardless of what the online interface suggests.
Practical Troubleshooting Tips
If you are having trouble logging in, the first thing to check is whether your browser is blocking cookies or third-party scripts. Edward Jones uses session cookies heavily, and ad blockers or privacy extensions can interfere with the authentication process. Try logging in with a clean browser profile or in incognito mode to rule out this issue entirely. Password reset flows can also be surprisingly frustrating. The system will send a reset link to your registered email address, but if you have changed your email recently and forgotten to update your account, you will be locked out until you verify your identity through phone or in-person channels. I have lost count of the number of times I have seen people panic about being locked out when the actual issue was simply that they forgot which email address they originally registered with. Mobile app issues tend to cluster around biometric authentication failures on older devices. Face ID and fingerprint login work reliably on newer phones, but if you are using a device more than three years old, you may find yourself falling back to manual password entry more often than you would like. The workaround here is to keep your device's operating system updated, as Apple and Google frequently release patches that improve biometric sensor reliability.
Get the Full Details
The customer service availability is another practical consideration. Unlike some competitors who offer 24-7 support, Edward Jones live agent hours are somewhat limited depending on your region and account type. If you are trading internationally or have a complex portfolio, you may need to call during business hours anyway, so having your account number and relevant documentation ready before you call saves significant time.
Security Best Practices That Actually Matter
Password hygiene is obvious but consistently ignored. Use a unique password for your Edward Jones account that you do not reuse on any other site. A password manager eliminates the cognitive load of remembering different complex passwords while still maintaining appropriate separation between accounts. I recommend against writing passwords on sticky notes near your computer or storing them in unencrypted files on your desktop. Two-factor authentication is non-negotiable for any financial account. SMS-based verification is better than nothing, but authenticator apps like Google Authenticator or Authy provide stronger protection against SIM swapping attacks, which have become increasingly common. If Edward Jones offers app-based codes in your region, prefer that over SMS whenever possible. Phishing awareness deserves its own category. I have seen too many people click through to fake Edward Jones login pages because the URL looked sufficiently similar to the real thing. Always verify the domain by checking for "edwardjones.com" specifically, and be suspicious of any email asking you to click a link to "verify" your account. The legitimate company will never ask you to do that through an email link.
Session management on shared computers is another area where people slip up. If you must log in on a public or shared machine, always manually log out when finished and clear your browser history. Some browsers remember login states even after closing windows, which creates a vulnerability anyone with access to that computer can exploit.
Understanding the Fee Landscape
Transaction fees vary by account type and trading volume. Standard brokerage accounts charge per-trade commissions that depend on the security type and order complexity. Mutual funds may have purchase loads or redemption fees depending on the share class. Exchange-traded funds generally trade at the standard commission rate, though some platforms have begun moving toward zero-commission ETF trading as competitive pressure increases. Account maintenance fees are rare at Edward Jones for standard retail accounts, but they do exist for certain specialized account types or if you fall below minimum balance thresholds on specific products. Read the disclosures carefully before opening any account, because the fees listed in the overview section are often the minimum, and the actual cost to you depends on your specific usage patterns. Advisory fees represent a different cost structure entirely. If you use the full-service advisor model, you pay an annual percentage of assets under management, typically ranging from one to two percent depending on account size and service level. This is substantially higher than self-directed trading costs but includes ongoing portfolio management, financial planning, and tax guidance. The break-even point depends entirely on whether you believe the advice you receive is worth the premium you pay.
Tax Documentation and Reporting
The tax year generates a significant paper trail that you need to manage carefully. Edward Jones sends Form 1099-B for completed transactions, Form 1099-DIV for dividends, and Form 1099-INT for interest income. These documents typically arrive in mid-February if you have a traditional account, though the exact timing depends on your statement cycle and any special circumstances like wash sale adjustments or foreign tax withheld. Cost basis reporting has become more complex since IRS regulations changed several years ago. The portal shows your cost basis for each position, but the calculations can be confusing if you have multiple lots purchased at different times, participated in dividend reinvestment programs, or received spinoffs from corporate actions. Download the detailed lot-level information before tax season rather than relying on summary numbers, because corrections after filing are painful. Roth IRA contributions and conversions require separate tracking because the tax treatment differs significantly between the two. Contributions are made with after-tax dollars and grow tax-free, while conversions move pre-tax money into a Roth account and trigger immediate taxation on the converted amount. Mixing these up on your tax return is a common mistake that audits occasionally catch, so keep clear records of each transaction type.

Platform Limitations and Workarounds
The mobile app, while functional, has notable limitations compared to the desktop version. Advanced order types like trailing stops and conditional orders are either unavailable or limited on mobile. If you are a sophisticated trader who relies on these tools, you will need to use the web platform for order entry, which means either keeping a browser open on your phone or switching to a laptop when placing complex orders. Research quality varies considerably between asset classes. Equity research is generally solid and updated regularly, but fixed income and alternative investment research is thinner. If you are building a diversified portfolio beyond stocks, do not rely solely on Edward Jones research materials. Supplement with independent sources or specialized data providers for the asset classes they cover less thoroughly. Order execution speed during volatile markets is another limitation. While Edward Jones does not typically have systemic outages, high-volume periods like earnings seasons or market events can slow down the order entry process. I experienced a particularly rough episode during a flash crash when the platform would not accept my stop loss orders for approximately twenty minutes due to what appeared to be excessive order flow. This is not unique to Edward Jones, but it is worth knowing so you can adjust your expectations during high-volatility periods.
The Advisor Relationship Question
Whether to work with an Edward Jones financial advisor is the decision that separates different client experiences entirely. The self-directed model gives you full control but requires you to do all the research, timing, and ongoing management yourself. The advisory model provides professional guidance but at a cost that compounds over time, potentially reducing your long-term returns significantly if the advice is not genuinely superior to what you could implement on your own. I have observed that the advisor relationship works best for clients who are approaching major life events like retirement, inheritance, or business sale, and who value the behavioral coaching element more than pure investment selection. During market downturns, having someone talk you out of panic selling can be genuinely valuable, even if their stock picks are only average. The cost of that emotional buffer may be worth more than the extra percentage points in fees you pay. However, for younger clients with decades of compounding ahead of them and reasonable financial literacy, the advisory model often returns negative alpha after fees. A simple low-cost index fund strategy managed independently outperforms most advisory portfolios over twenty-year horizons, once you account for the drag of annual fees. This is uncomfortable for the industry to hear, but it is the mathematical reality of fee structures combined with historical market returns.
The hybrid approach deserves mention here. Some clients maintain a self-directed account for routine investments while working with an advisor on specific projects like estate planning or tax strategy optimization. This fragments your assets across platforms, which creates administrative complexity, but it can be an efficient way to get professional help where it matters most without paying full advisory fees on your entire portfolio.
Account Types and Which One Fits Your Situation
Standard brokerage accounts are the default option and offer maximum flexibility for withdrawal and transfer. There are no restrictions on when you can access your money, though gains are taxed as they are realized. These accounts suit clients who want liquidity and do not need the tax advantages of retirement vehicles. IRA accounts come in several flavors, each with different contribution limits and withdrawal rules. Traditional IRAs offer upfront tax deductions but tax withdrawals in retirement. Roth IRAs provide tax-free growth and tax-free withdrawals but require after-tax contributions. SEP IRAs and SIMPLE IRAs are designed for self-employed individuals and small business owners, with higher contribution limits reflecting the business owner status. Taxable education accounts like 529 plans serve specific purposes with specialized tax treatment. The account owner maintains control of the funds even after the beneficiary is established, which distinguishes them from gift structures where control is permanently transferred. Change of beneficiary options exist but may have implications for gift tax reporting.
Custodial accounts for minors operate differently from most other account types. The custodian manages the assets until the child reaches the age of majority, at which point control transfers irrevocably. This lack of continued control after the child becomes an adult surprises many parents, so understand the implications before establishing a UTMA or UGMA account through Edward Jones or any other platform.
Getting Started With a New Account
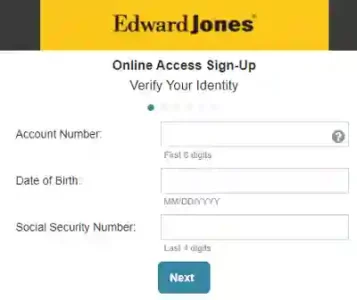
The opening process is predominantly digital now, though some verification steps may require phone or document submission. You will need personal identification information including Social Security number, date of birth, and address verification. Banking information is required for funding the account, and you will establish a username and password during registration. Funding timelines depend on your chosen method. ACH transfers from linked bank accounts typically settle within one to three business days, while wire transfers are faster but may incur fees from both the sending and receiving banks. Check with your bank about outbound wire charges, as some institutions charge thirty to forty dollars per outgoing wire, which can eat into small initial deposits. Initial investment strategy matters more than the account setup itself. Do not rush into buying individual stocks simply because you can. Consider starting with broad market index funds or target date funds if you are constructing a retirement portfolio, then gradually adding individual positions as you develop conviction in specific holdings. The psychology of having money in the account without meaningful deployment is uncomfortable, but premature concentration is how people lose money fast.
Set up your account preferences immediately after opening. Configure your statement delivery method, establish your communication preferences, and link your external bank accounts for funding. These administrative tasks are boring but prevent future friction when you actually need to move money or access documents. Nobody enjoys filling out paperwork, but doing it proactively saves considerable time later.
Daily Account Management Routines
Regular account review does not mean micromanaging every position daily. A monthly or quarterly check-in is sufficient for most long-term investors. Look for unexpected trades, verify your asset allocation has not drifted significantly from your target, and confirm that automatic contributions are executing as expected. Transaction monitoring should include verification that trades executed at the prices you expected. Market orders during volatile periods can fill at significantly worse prices than the last quoted price, which is a feature of market mechanics, not a platform error. Understanding this distinction prevents unnecessary frustration when your execution price does not match the quote you saw minutes earlier. Portfolio rebalancing discipline requires checking whether your allocations have drifted outside your target ranges. A portfolio that started at sixty percent stocks and forty percent bonds can easily shift to seventy-thirty after a strong equity rally, increasing your risk exposure without any conscious decision to change it. Set annual or semi-annual rebalancing triggers and execute them mechanically rather than emotionally.
Tax loss harvesting opportunities appear periodically throughout the year, particularly during market drawdowns. Selling losing positions to offset gains in other areas can reduce your current tax liability, but you must navigate the wash sale rule carefully. Repurchasing the same or substantially identical security within thirty days before or after the sale disallows the loss for tax purposes. This rule applies across all your accounts, not just the Edward Jones account, so coordinate your harvesting activities across multiple platforms.
Common Pain Points and How to Navigate Them
Forgotten passwords remain the single most frequent support issue. Establish a password manager habit early to avoid this problem entirely. Write down your master password in a secure location if you cannot trust digital storage, though this is less ideal than a proper password manager solution. Delayed trade confirmations sometimes occur during high-volume periods or system maintenance windows. If you place an order and do not receive confirmation within a reasonable timeframe, check your account directly rather than assuming the order failed. The confirmation delay usually resolves itself, but verifying the order status prevents duplicate orders that compound the problem. Misunderstood account terminology creates confusion for new investors. Terms like cost basis, average price, unrealized gain, and dividend reinvestment have specific technical meanings that differ from colloquial usage. Take time to understand these concepts through official documentation or direct consultation before making decisions that depend on accurate comprehension.
When Edward Jones May Not Be the Right Fit
Certain client profiles simply do not align well with the Edward Jones model. Active traders executing dozens of trades monthly will find the per-transaction costs prohibitive compared to zero-commission alternatives. International investors may face limitations on available securities and currency management options. Clients seeking cutting-edge technology features like advanced charting tools, algorithmic trading, or real-time data feeds will likely be disappointed by the relatively conventional platform capabilities. The fee structure disadvantages smaller accounts disproportionately. A five hundred dollar monthly contribution on a ten thousand dollar account generates more friction from minimum fees and percentage-based costs than the same contribution pattern on a million-dollar portfolio. If you are just starting out with modest amounts, consider whether the value provided justifies the relative cost burden before committing to this platform long-term. Situations requiring rapid account access during market stress favor platforms with redundant infrastructure and guaranteed uptime SLAs. While Edward Jones has historically maintained reliable service, no platform is immune to outages during extreme market events. Clients for whom uninterrupted access is critical should understand this limitation and maintain contingency plans regardless of which broker they choose.
Advanced Research Tools and Resources
Analyst reports accessible through the portal provide fundamental analysis on thousands of publicly traded companies. These reports cover earnings projections, valuation metrics, competitive positioning, and industry trends. The depth of coverage varies by company size and sector, with large-cap stocks receiving substantially more attention than small-cap or niche industry names. Screening tools allow you to filter equities by fundamental criteria, technical indicators, or sector classification. While these tools are less sophisticated than dedicated screeners from Bloomberg or FactSet, they cover the needs of most retail investors and integrate directly with your portfolio for easy position comparison. Economic research and market commentary from Edward Jones analysts provide context for your investment decisions. The quality of this research is generally solid, though it tends toward conservative perspectives that may underweight disruptive opportunities or overemphasize near-term risks. Use it as one input among many rather than the definitive word on market direction.
The Long-Term Relationship Perspective
Choosing a brokerage is not a decision you revisit annually. The switching costs, both financial and administrative, create inertia that favors staying with your current provider unless there is a compelling reason to move. This means the initial selection should weigh long-term fit more heavily than short-term feature comparisons or promotional offers. Relationship with your branch advisor develops over years, not weeks. The first meeting establishes expectations, but the real value comes from ongoing dialogue during market cycles, life transitions, and tax planning opportunities. Invest time in finding an advisor whose communication style and investment philosophy align with your own, because a mismatched relationship causes more harm than good regardless of the advisor's technical competence. Platform improvements continue slowly over time, as is typical for established financial institutions. The pace of technological innovation at Edward Jones trails newer fintech competitors, but the core functionality necessary for effective account management is present and reliable. Manage your expectations around feature parity with app-first platforms, while appreciating the stability and regulatory oversight that comes with the established model.
Final Practical Considerations
The login process itself is a minor hurdle compared to the actual investment decisions you will make through your account. Master the authentication procedures early, set up security measures appropriately, and move quickly past the technical setup to focus on the substantive work of building and managing your portfolio. The platform is a tool, not the strategy, and confusing the two leads to misplaced emphasis on interface features rather than investment outcomes. Documentation retention policies vary by account type and transaction volume. Maintain digital copies of all account statements, trade confirmations, and tax documents for at least seven years, preferably longer. Cloud storage with redundancy provides adequate protection against physical document loss, though some clients prefer physical filing systems for sensitive financial records. Choose whichever approach you will actually maintain consistently over decades, because the theoretical ideal means nothing if you never access the documents when needed. Emergency access planning is an often-overlooked responsibility. Designate a trusted contact or joint account holder who can access your accounts if you become incapacitated, and ensure they know the necessary credentials and procedures. This conversation is uncomfortable but potentially critical during medical emergencies or extended travel, and proper planning prevents your family from facing bureaucratic obstacles when they need access most.
The Edward Jones platform serves a broad spectrum of investors with varying needs and expertise levels. Understanding both its capabilities and its limitations allows you to extract maximum value from the relationship while avoiding common pitfalls that frustrate uninformed users. The account login is simply the doorway. What you do inside that account, and how you manage it over time, determines the actual financial outcome far more than any feature comparison or promotional offer ever could.