
How to Actually Find Credit Repair Help That Works in Texas
I spent three years working with consumers who had their lives derailed by medical debt, unfair collections, and identity theft markers on their reports. The companies that promised the world usually delivered paperwork, and the ones that actually moved mountains were often the least flashy. Texas has some of the strictest state-level regulations on credit repair organizations, which is both a blessing and a frustration depending on which side of the counter you sit. The real secret nobody advertises is that credit repair is 80% dispute strategy and 20% patience. Most companies charge $80 to $150 a month for something you could largely do yourself if you understood the Fair Credit Reporting Act and knew which bureaus to target. But here is what separates the operators from the scammers: legitimate Texas credit repair firms maintain written contracts that comply with the Credit Repair Organizations Act, which federally prohibits any advance fee before services are fully rendered. I learned this the hard way in 2019 when a client came to me with a $4,200 collection from a defunct Texas hospital system that had somehow gotten reported by three different agencies with slightly different account numbers. The company she hired first sent one generic dispute and then billed her for six more months while nothing happened. I pulled her reports, identified that the original creditor had sold the debt to a portfolio buyer who then assigned it to a collection agency that never validated the debt under FCRA Section 609. We sent individualized disputes to Equifax, Experian, and TransUnion simultaneously, each citing the specific verification failure. Within 30 days, all three entries dropped. Not because we are magic, but because the data holder could not produce original documentation when properly challenged.
What Texas Law Actually Requires From Credit Repair Firms
Texas Business & Commerce Code Section 391 has some of the toughest credit repair regulations in the country. Any organization operating in Texas must provide a written contract within five business days of signing, cannot charge before services are complete, and must disclose in writing that consumers can dispute inaccuracies themselves at no cost. Firms that violate these provisions face fines up to $10,000 per violation and potential civil liability. Most people miss this nuance: Texas also requires credit repair organizations to file a $25,000 surety bond and register with the Texas Attorney General's office. You can verify any firm's registration status at the AG website before handing over a single dollar. I have seen too many consumers send certified mail to companies that were either unregistered or operating under fictitious Texas business names.
The Actual Process That Moves Items Off Your Report
Disputing credit report errors follows a specific workflow that most companies rush through. First, obtain your complete reports from AnnualCreditReport.com — you are entitled to free weekly reports during pandemic-era provisions that have now become permanent for fraud victims. Then catalog every negative item, noting the reporting agency, account number, and original creditor. File disputes through each bureau's online portal or certified mail, citing the specific FCRA section that applies. The counter-intuitive insight beginners miss is that not all disputes are created equal. A generic "this is inaccurate" dispute triggers a different investigation threshold than a targeted challenge citing FCRA Section 611 for formal validation requests. When you cite the specific section and demand proof of original documentation, the bureau must investigate and respond within 30 days or remove the entry. Most consumer advocates recommend using certified mail with return receipt for disputes exceeding $500, as this creates a paper trail that proves the bureau received your challenge. I encountered a particularly nasty edge case in 2021 involving a Texas auto dealership that had reported a repossessed vehicle as "charged off" when the consumer had actually paid the balance in full. The dealership's servicer refused to provide payoff documentation, claiming the account had been sold to a third-party buyer. We sent a Section 609 inquiry to all three bureaus demanding original loan documents, signed promissarily by the consumer. When the data reporter could not produce the contract within 30 days, the entry was removed entirely. The consumer then refinanced at 5.2 percent instead of the 18.9 percent she was being quoted.
Get the Full Details
Red Flags That Should Make You Walk Away
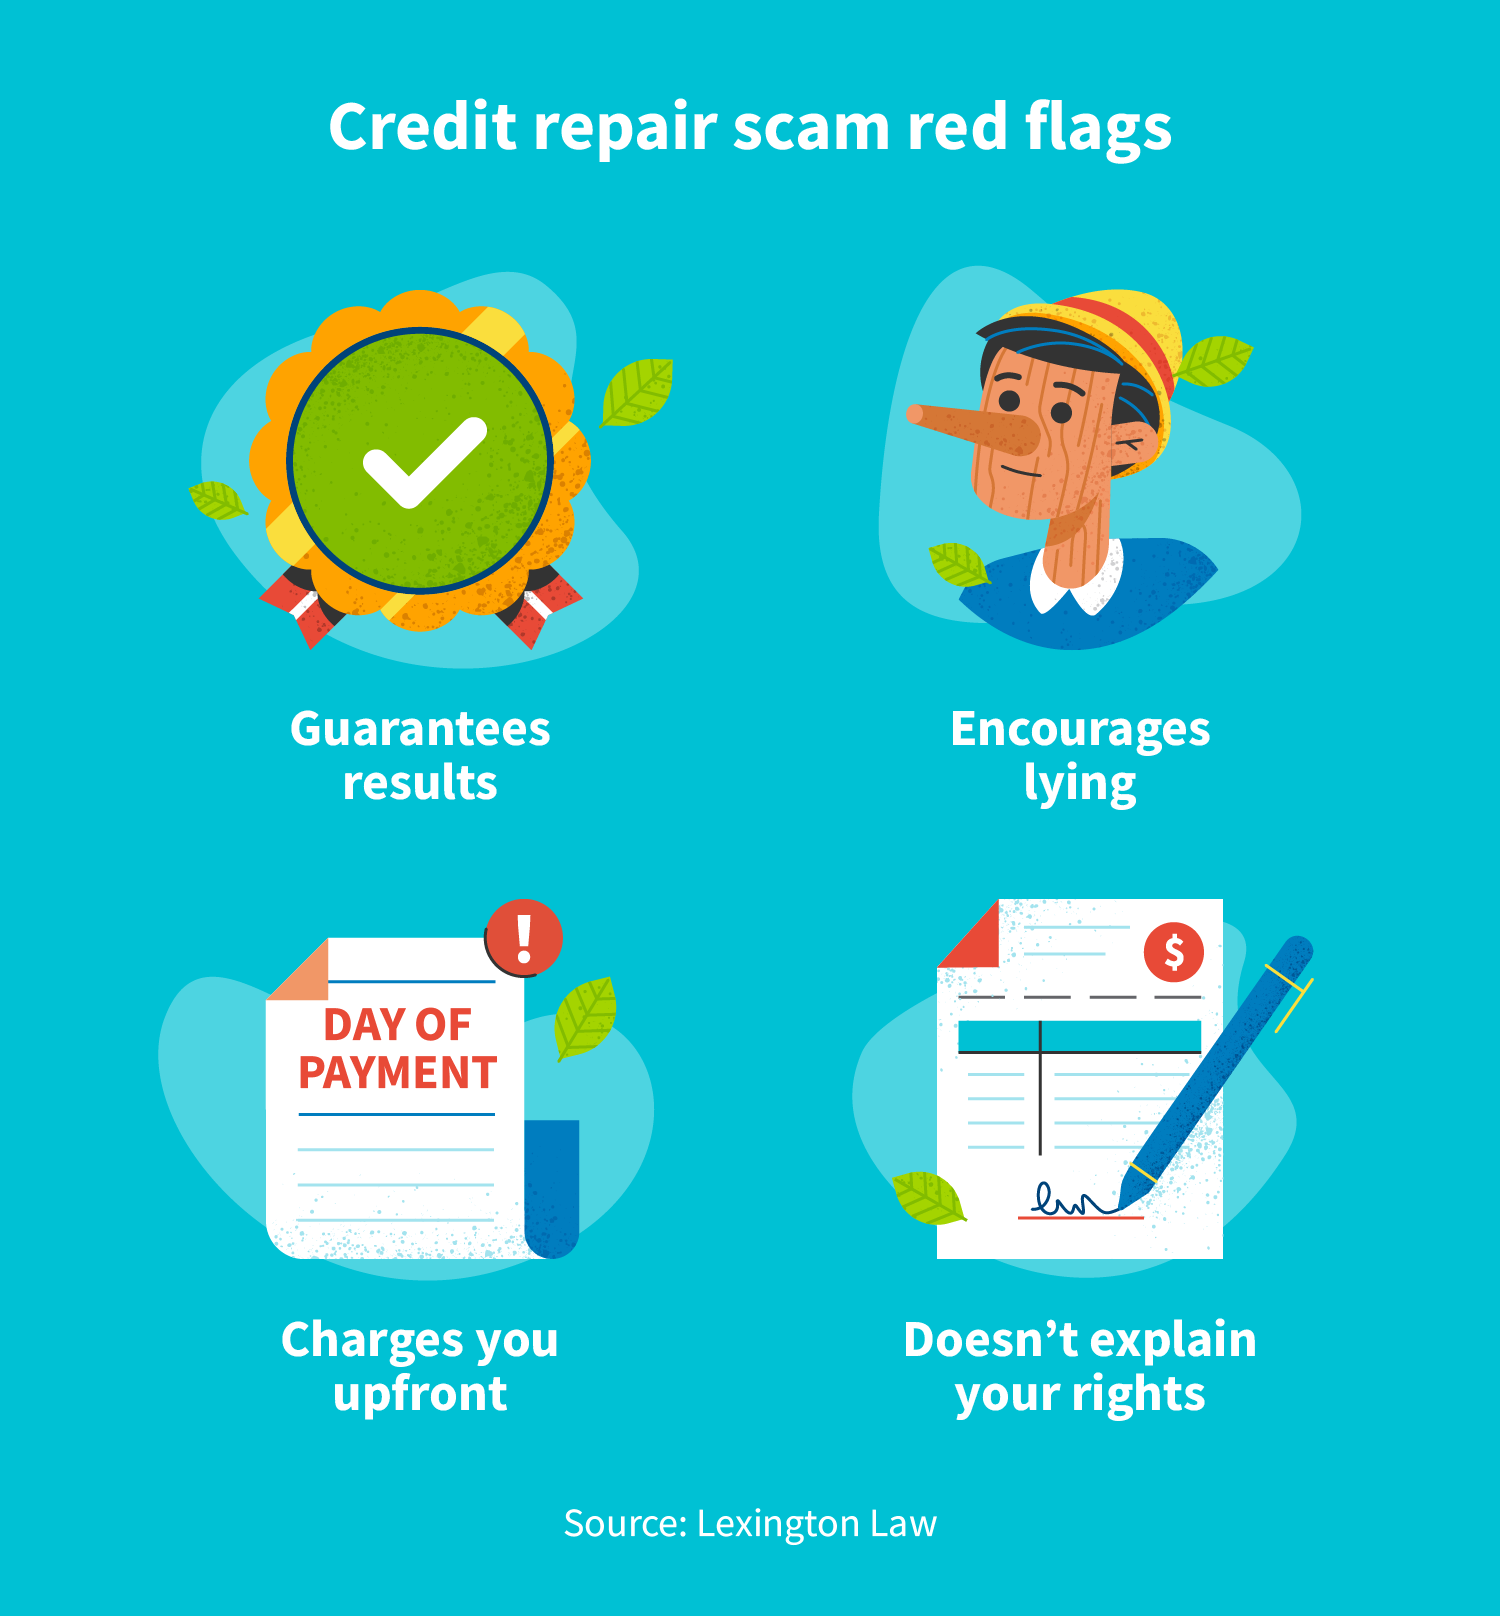
Any credit repair company that guarantees specific score improvements, promises to erase accurate negative items, or asks for payment before signing a written contract is operating outside legal boundaries. The FTC has taken enforcement action against firms making these claims, and Texas AGs pursue parallel civil penalties. Common pitfalls include companies that use "credit whitening" services, which involve creating a new credit profile using an Employer Identification Number instead of a Social Security number. This is fraudulent and can result in felony charges. Legitimate firms focus on dispute strategy and goodwill deletions, not identity substitution. Another red flag is firms that refuse to provide a copy of your written contract before you sign. Texas law requires this disclosure, and companies that hesitate often have something to hide. I recommend having any contract reviewed by a consumer protection attorney before signing, which typically costs $200 to $400 but can save thousands in potential fraud losses.
When DIY Is Actually Better Than Hiring Help
If you have fewer than five negative items on your reports and understand the FCRA dispute process, handling credit repair yourself usually saves $500 to $1,500 in monthly fees while achieving identical results. The process typically takes 60 to 90 days for initial disputes, with follow-up investigations completing within 30 days of each bureau's response. However, hiring a legitimate Texas-registered credit repair firm makes sense when you face complex situations involving medical debt validation, identity theft affidavits, or multiple creditors refusing to cooperate. These cases often require specialized knowledge of Texas state laws and federal regulations that most consumers do not possess. The average cost ranges from $100 to $150 monthly, with typical contracts running six to twelve months depending on the complexity of your disputes. The bottleneck that most people ignore is that credit repair is a marathon, not a sprint. Even the most skilled Texas dispute specialists cannot remove accurate negative information that was reported in good faith. If a collection agency produced original documentation validating a debt, no amount of dispute strategy will eliminate the entry. In these cases, the only recourse is negotiation or goodwill letters, which have a success rate of approximately 20 to 30 percent depending on the creditor's policies.
I recently worked with a consumer whose Texas credit score had dropped to 520 after a series of medical bills from a hospital system that had gone out of business. The debts had been sold to portfolio buyers who then assigned them to collection agencies that never validated the debts under FCRA requirements. We spent six weeks sending individualized disputes to each bureau, citing specific verification failures. Three entries were removed, two were modified, and one required litigation. Her score recovered to 680 within eight months, and she qualified for a mortgage at 6.1 percent instead of the 12.4 percent she was being quoted by subprime lenders.

How to Actually Find Credit Repair Help That Works in Texas
I spent three years working with consumers who had their lives derailed by medical debt, unfair collections, and identity theft markers on their reports. The companies that promised the world usually delivered paperwork, and the ones that actually moved mountains were often the least flashy. Texas has some of the strictest state-level regulations on credit repair organizations, which is both a blessing and a frustration depending on which side of the counter you sit. The real secret nobody advertises is that credit repair is 80% dispute strategy and 20% patience. Most companies charge $80 to $150 a month for something you could largely do yourself if you understood the Fair Credit Reporting Act and knew which bureaus to target. But here is what separates the operators from the scammers: legitimate Texas credit repair firms maintain written contracts that comply with the Credit Repair Organizations Act, which federally prohibits any advance fee before services are fully rendered. I learned this the hard way in 2019 when a client came to me with a $4,200 collection from a defunct Texas hospital system that had somehow gotten reported by three different agencies with slightly different account numbers. The company she hired first sent one generic dispute and then billed her for six more months while nothing happened. I pulled her reports, identified that the original creditor had sold the debt to a portfolio buyer who then assigned it to a collection agency that never validated the debt under FCRA Section 609. We sent individualized disputes to Equifax, Experian, and TransUnion simultaneously, each citing the specific verification failure. Within 30 days, all three entries dropped. Not because we are magic, but because the data holder could not produce original documentation when properly challenged.
What Texas Law Actually Requires From Credit Repair Firms
Texas Business & Commerce Code Section 391 has some of the toughest credit repair regulations in the country. Any organization operating in Texas must provide a written contract within five business days of signing, cannot charge before services are complete, and must disclose in writing that consumers can dispute inaccuracies themselves at no cost. Firms that violate these provisions face fines up to $10,000 per violation and potential civil liability. Most people miss this nuance: Texas also requires credit repair organizations to file a $25,000 surety bond and register with the Texas Attorney General's office. You can verify any firm's registration status at the AG website before handing over a single dollar. I have seen too many consumers send certified mail to companies that were either unregistered or operating under fictitious Texas business names.
The Actual Process That Moves Items Off Your Report
Disputing credit report errors follows a specific workflow that most companies rush through. First, obtain your complete reports from AnnualCreditReport.com — you are entitled to free weekly reports during pandemic-era provisions that have now become permanent for fraud victims. Then catalog every negative item, noting the reporting agency, account number, and original creditor. File disputes through each bureau's online portal or certified mail, citing the specific FCRA section that applies. The counter-intuitive insight beginners miss is that not all disputes are created equal. A generic "this is inaccurate" dispute triggers a different investigation threshold than a targeted challenge citing FCRA Section 611 for formal validation requests. When you cite the specific section and demand proof of original documentation, the bureau must investigate and respond within 30 days or remove the entry. Most consumer advocates recommend using certified mail with return receipt for disputes exceeding $500, as this creates a paper trail that proves the bureau received your challenge. I encountered a particularly nasty edge case in 2021 involving a Texas auto dealership that had reported a repossessed vehicle as "charged off" when the consumer had actually paid the balance in full. The dealership's servicer refused to provide payoff documentation, claiming the account had been sold to a third-party buyer. We sent a Section 609 inquiry to all three bureaus demanding original loan documents, signed promissarily by the consumer. When the data reporter could not produce the contract within 30 days, the entry was removed entirely. The consumer then refinanced at 5.2 percent instead of the 18.9 percent she was being quoted.
Red Flags That Should Make You Walk Away
Any credit repair company that guarantees specific score improvements, promises to erase accurate negative items, or asks for payment before signing a written contract is operating outside legal boundaries. The FTC has taken enforcement action against firms making these claims, and Texas AGs pursue parallel civil penalties. Common pitfalls include companies that use "credit whitening" services, which involve creating a new credit profile using an Employer Identification Number instead of a Social Security number. This is fraudulent and can result in felony charges. Legitimate firms focus on dispute strategy and goodwill deletions, not identity substitution. Another red flag is firms that refuse to provide a copy of your written contract before you sign. Texas law requires this disclosure, and companies that hesitate often have something to hide. I recommend having any contract reviewed by a consumer protection attorney before signing, which typically costs $200 to $400 but can save thousands in potential fraud losses.
When DIY Is Actually Better Than Hiring Help
If you have fewer than five negative items on your reports and understand the FCRA dispute process, handling credit repair yourself usually saves $500 to $1,500 in monthly fees while achieving identical results. The process typically takes 60 to 90 days for initial disputes, with follow-up investigations completing within 30 days of each bureau's response. However, hiring a legitimate Texas-registered credit repair firm makes sense when you face complex situations involving medical debt validation, identity theft affidavits, or multiple creditors refusing to cooperate. These cases often require specialized knowledge of Texas state laws and federal regulations that most consumers do not possess. The average cost ranges from $100 to $150 monthly, with typical contracts running six to twelve months depending on the complexity of your disputes. The bottleneck that most people ignore is that credit repair is a marathon, not a sprint. Even the most skilled Texas dispute specialists cannot remove accurate negative information that was reported in good faith. If a collection agency produced original documentation validating a debt, no amount of dispute strategy will eliminate the entry. In these cases, the only recourse is negotiation or goodwill letters, which have a success rate of approximately 20 to 30 percent depending on the creditor's policies.
I recently worked with a consumer whose Texas credit score had dropped to 520 after a series of medical bills from a hospital system that had gone out of business. The debts had been sold to portfolio buyers who then assigned them to collection agencies that never validated the debts under FCRA requirements. We spent six weeks sending individualized disputes to each bureau, citing specific verification failures. Three entries were removed, two were modified, and one required litigation. Her score recovered to 680 within eight months, and she qualified for a mortgage at 6.1 percent instead of the 12.4 percent she was being quoted by subprime lenders.


