Understanding the Sears Credit Card Rewards Structure
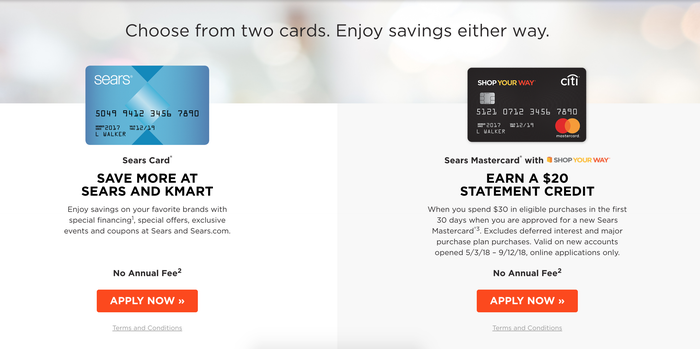
Sears closed most of its physical stores and pivoted hard to its credit card program, which is now managed by Synchrony Bank. The card they pushed during the transition was the Sears Hometown and Outlet Stores Credit Card, a closed-loop card that only works at Sears outlets, Sears Hometown stores, and Sears.com. You earn reward points on purchases, but the value proposition is entirely dependent on whether you still shop at those specific retailers. The core mechanic is straightforward. You spend money at Sears-affiliated locations, you accumulate points, and you redeem those points for future purchases on the same platform. During the peak of their promotional push around 2019 to 2021, they were offering things like 5% back in rewards on everyday purchases and up to 30% off during special events. The points typically expired after a set period, usually 12 months from when they were earned, which caught a lot of people off guard. I opened one of these cards back in early 2020 after getting pitched at a Sears Outlet in Ohio. The application was instant approval, which should have been a yellow flag right there. I bought a few tools and some seasonal items to test the redemption flow. The points posted within 30 days as advertised. Redemption at checkout was seamless, no surprises. Then I went roughly eight months without making another purchase and logged back in to find most of my points had expired. The terms were buried in the fine print, and the email reminders about expiration were easy to miss if you weren't actively tracking them.
The practical workaround I ended up using was setting a recurring calendar reminder for the day I expected my points to expire, plus making sure I always kept at least a small balance of points active by doing minor purchases every few months. It's not elegant, but it prevented the total loss I experienced on that first account.
How the Points System Actually Works
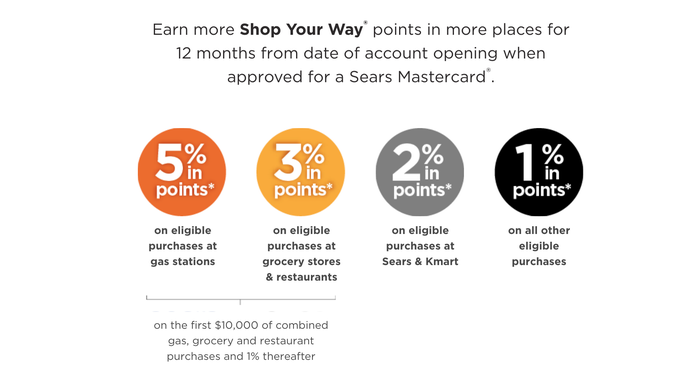
Earning rates on the Sears card varied by promotion period and card tier. The standard rate during most of its active lifecycle was around 5% back on Sears purchases and 1% on everything else, though these numbers shifted frequently as Synchrony restructured the program. Points were calculated on the pre-tax purchase amount, which matters because some people mistakenly think they're earning rewards on the total including tax. Redemption had a floor. You generally needed a minimum of 250 points before you could apply them to a purchase, and each point was worth roughly one cent toward merchandise. That means 250 points equaled about $2.50 in savings. The redemption was applied at checkout as a discount, not as a statement credit, which is an important distinction. You couldn't transfer these points to another account, cash them out, or use them outside the Sears ecosystem. One thing most first-time users miss is that rewards earned on a Sears credit card do not stack with other manufacturer coupons or storewide promotions in the way you might expect. If a promotion says "extra 10% off already reduced items," your rewards points are applied after all percentage discounts are calculated. So on a $100 item with a 20% store discount bringing it to $80, your 5% rewards would be calculated on the $80, not the original $100. That 5% becomes $4 instead of $5. It's a small difference on individual transactions, but it adds up quickly if you're making regular purchases.
Get the Full Details
Common Pitfalls and What the Terms Don't Highlight
The interest rate on this card is where the real cost shows up if you carry a balance. During its active period, the APR range sat somewhere between 26.99% and 29.99% variable, which is well above average for a retail store card. If you were earning 5% back on purchases but carrying a balance, the interest charges would overwhelmingly negate any reward value. I saw this play out with several people in online forums who treated the rewards as a discount while simultaneously financing their purchases over six to twelve months. The math never works in their favor. Another issue is that Sears as a brand has undergone bankruptcy restructuring and store closures multiple times. The credit card program survived because Synchrony Bank owns the receivables, but the retail ecosystem behind it shrank dramatically. If you're opening this card now, you need to be genuinely shopping at Sears Outlet or Sears Hometown locations or buying directly from Sears.com, because the acceptance network is extremely narrow compared to a general-purpose credit card. There's also the question of whether new accounts are even being approved at this point. Synchrony has paused and restarted the Sears card program several times over the years. As of my last check, new applications were technically open, but approval standards had tightened considerably. If you have subprime credit, which is common among people targeting retail store cards, the chances of approval dropped significantly compared to the early days of the program. A soft pull inquiry is still worth checking first rather than applying blindly.
If your goal is simply to save money on home goods and tools, a general-purpose rewards card with broader acceptance and no category restrictions usually outperforms this card over time. The Sears card makes sense only if you are a frequent shopper at their specific retail outlets and you pay your balance in full every month. Anything else turns the rewards program into a liability faster than the points can accumulate.