Managing Your Sears Account Online Without Losing Your Mind
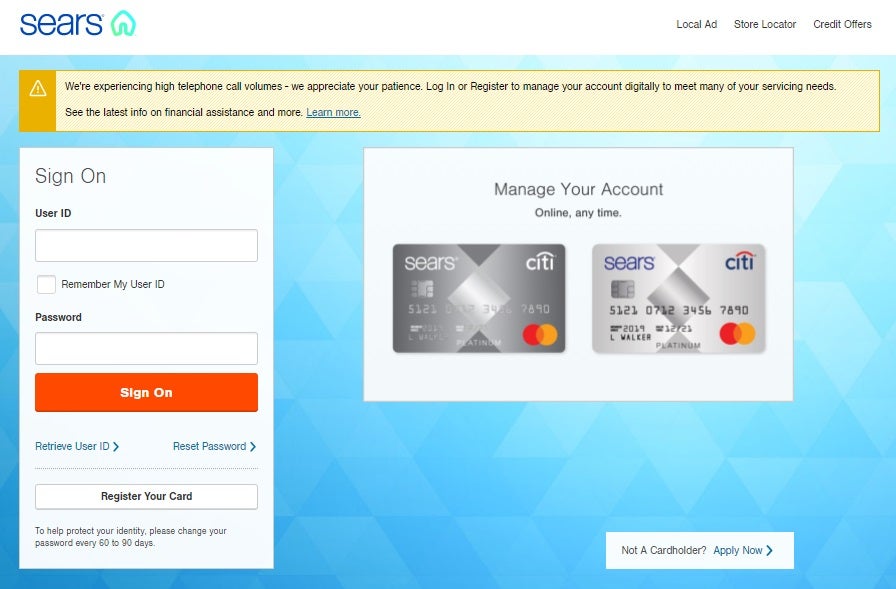
Sears accounts used to be straightforward. You got a card, you paid the bill, you shopped at the store. That changed around 2019 when Synchrony Bank took over the credit portfolio and then again when the retail side collapsed. If you're trying to deal with a Sears bill right now, the landscape is messy and not very well documented anywhere. This guide covers what actually works. Start at mysearsaccount.com. That's still the portal, even though it looks like it hasn't been touched since 2017. The login page still functions. Enter your account number — it's on your monthly statement, twelve digits starting with a 4 or a 5 — and your username. If you set one up, you're good. If you never created a username, click "Register" and use your account number plus your SSN or date of birth. That takes about ninety seconds. Once you're in, the payment section is buried under "Services" then "Make a Payment." The interface is clunky. It doesn't auto-fill anything. You enter the dollar amount, select your bank, and confirm. Payments processed before 5 PM Eastern on a business day usually post the same day. After that, it's next business day. Late fees are assessed if you miss the due date, and they're not cheap — typically fifteen dollars or twenty percent of the minimum, whichever is greater.
Here's the thing nobody puts in the FAQ: the portal sometimes shows a pending balance instead of the actual posted balance for up to two business days after a payment goes through. I learned this the hard way in March 2023 when I paid my bill and immediately tried to close out the account. The system kept rejecting the request because it thought I still owed money that had already been deducted from my bank. I waited four days, refreshed, and it went through. If you're in a similar situation, don't spam the payment button. Just wait. The Sears mobile app is another story. The original Sears app was discontinued and replaced by what they called the "Sears+ App" in 2021, but it's basically a shopping app now. It doesn't handle bill payments. If someone sent you a link to download the Sears app for bill pay, that's outdated information. Stick to the website. Auto-pay is available but finicky. You set it up in the same payment section, and it pulls from a checking or savings account on your due date. The problem is that auto-pay doesn't account for purchases you make after the billing cycle closes but before the statement generates. If you put a big purchase on your card three days before the statement date, your auto-pay amount won't include it. You'll get a shortfall notice and a late fee anyway. The workaround is turning off auto-pay and setting a manual calendar reminder for five days before the due date instead. That gives you time to see your statement and adjust.
There's also a phone option. The number is 1-800-853-8326, which is the Synchrony credit services line. The automated system can process a one-time payment if you have your account number and routing information. Going through a representative adds about eight minutes but helps if you're dealing with a billing dispute. I called once when a $34 charge from a defunct Sears store in Ohio showed up on my statement six months after that location closed. The rep pulled up the transaction, flagged it as potentially fraudulent, and escalated it. It disappeared from my next statement. The chat feature on the website doesn't connect you to a real person — it routes to a bot that gives you scripted responses. Skip it. Statement delivery defaults to paper unless you opt for electronic. The e-statement option is worth switching to because it posts to your account faster and you get email notifications when a new one is ready. You change this under "Profile" then "Statement Preferences." Takes thirty seconds. Now for the things that go wrong and what to do about them. First: if your account is in collections, the online portal won't help you. You need to contact the collection agency directly. Second: if you lost your statement and can't find your account number, call the number above. They'll verify your identity and read it to you over the phone. Third: if you're trying to pay off a balance in full and the system is showing a payoff amount that seems too high, that's probably because interest accrues daily. The amount you see online is a snapshot. For a true payoff quote, you need to call and ask for a "payoff statement" which will be valid for a specific ten-day window.
Get the Full Details

One counter-intuitive detail: making a payment larger than your statement balance doesn't immediately give you a refund. It creates a credit balance on the account. To get money back, you have to call and request a refund check, which takes ten to fourteen business days to arrive. I had a $200 credit sit there for six months because I didn't know this and just assumed it would bounce back automatically. The Sears credit card also has a rewards program, but it's largely irrelevant now. Points are worth about half a cent each, and redemption options are limited to catalog items or statement credits. There's no transfer partner for travel. If you're earning rewards, fine. Don't hold your breath. Bottom line: the system works if you understand its quirks. Log in, pay on time, call instead of using chat, and don't rely on auto-pay without checking your statement first. Everything else is noise.