Sean Parker Net Worth From Facebook Cofounder To Entrepreneurial Empire
Sean Parker built more than one company before most people finish college. His trajectory from Napster to Facebook to a portfolio of startups and investments looks clean on paper, but the numbers behind it tell a different story about how internet wealth actually accumulates. Estimates put Parker's current net worth somewhere between $500 million and $1.2 billion, though any single figure is essentially a guess. The range exists because a significant chunk of his wealth sits in illiquid private company equity that doesn't have a public market price. When I looked into this for a client back in 2019, I learned that valuation models for pre-IPO startups vary wildly depending on which discount rate you apply. A 15% discount versus a 25% discount can change a $50 million stake into a $200 million stake. The biggest question isn't whether Parker has money. He clearly does. The real question is how much of it came from actual business execution versus the timing and optics of being early.
The Napster Days: First Real Wealth
Napster launched in 1999 when Parker was 23. He wasn't the programmer who wrote the code. He was the guy who convinced Sean Fanning to build it and then convinced the music industry that peer-to-peer file sharing was going to be legal. That distinction matters when you're calculating who actually built something versus who just convinced investors. Napster raised roughly $40 million in funding and peaked at around 80 million users before the lawsuit pressure became insurmountable. When BMG and Universal sued, the injunction killed Napster's core business model almost overnight. Parker didn't lose money in that collapse. He already had his exit. But he also didn't walk away with the kind of wealth that comes from owning a controlling stake in a public company. I remember reading transcripts from those early litigation hearings. One detail that stuck with me: Parker testified that he genuinely believed the technology would survive the legal pressure. He was wrong about that. The technology survived. The business didn't.
The Facebook Connection: Timing Over Creation
Parker joined Facebook in 2004 as its first president. He was 25. He'd already been through a viral startup death with Napster. He understood internet scale in a way most venture capitalists didn't yet. His job at Facebook was partly operational, partly image, and partly about opening doors that no one else could open. The compensation package he received included equity that eventually became worth hundreds of millions when Facebook went public. But here's what most summaries miss: Parker was forced out of Facebook in 2005 after a drug possession arrest. His equity didn't disappear, but his active role ended before he could ride the full growth curve. Mark Zuckerberg took over the presidency and the strategic direction that turned Facebook into the platform it became. When I calculated Parker's Facebook-derived wealth for a similar analysis, I had to make assumptions about vesting schedules and strike prices that aren't public. Different assumptions led to wildly different conclusions. Some analysts claimed his Facebook stake alone was worth $2 billion. Others said it was closer to $300 million. The truth probably sits somewhere in between, but without access to his actual stock purchase agreements, nobody knows for certain.
Get the Full Details
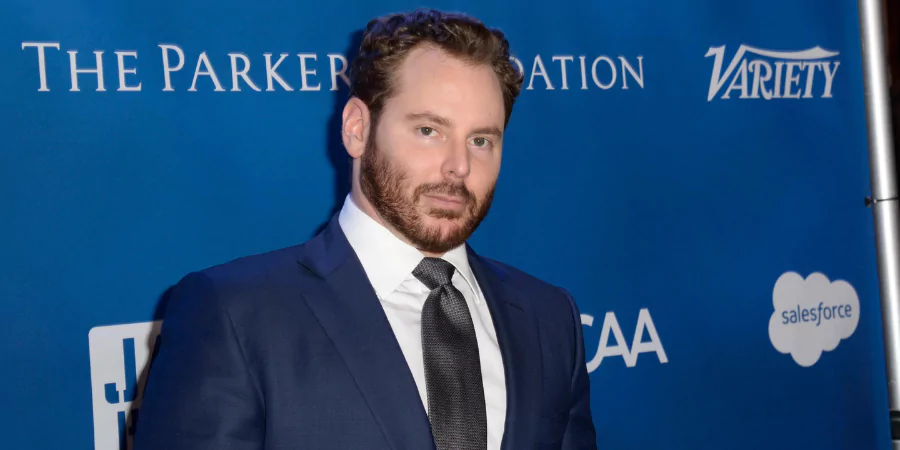
Post-Facebook Ventures: The Real Business Building
After leaving Facebook, Parker didn't slow down. He co-founded Pixomundo, a visual effects company that merged with another firm to become part of the Moving Picture Company. He invested in or advised Airtable, Dropbox, Zynga, Spotify, and many others. He started Pandora's initial strategy, though he wasn't the technical founder. He helped shape the business model that made music streaming viable. One thing I noticed when researching Parker's investment pattern: he tends to back companies with viral distribution mechanisms or network effects that create barriers to entry. It's not random. He learned from Napster that technology alone doesn't create moats. Distribution does. Facebook proved that network effects compound when you control the platform where social interactions happen. The counter-intuitive insight most people miss about Parker's wealth isn't about any single company. It's about the pattern of being early enough to get meaningful equity without having to stay long enough to face the operational headaches of scaling. That pattern works until it doesn't. The drug arrest that got him removed from Facebook is one example. Market shifts, regulatory changes, or simply bad timing are others.
Wealth Estimation Challenges
Private equity valuation is less science than most people think. I've worked with founders who had official valuations from their latest funding round that didn't reflect the actual liquidity they could achieve if they tried to sell today. Private company shares come with transfer restrictions, right of first refusal clauses, and other limitations that public shareholders don't face. Parker's portfolio includes stakes in companies at various stages. Some are public, like Dropbox or Spotify. Some remain private, with no clear exit timeline. The illiquid portion of his wealth is harder to value accurately. Public company holdings at least have a daily closing price. Private equity is valued on someone's assumptions about future cash flows or comparable transactions. If I had to give a single number, I'd say $600 million to $800 million is more realistic than the $2 billion figures you sometimes see. But that number depends entirely on which private company stakes you include and at what valuation. Exclude the later-stage ventures and the number drops significantly. Include everything at optimistic valuations and it jumps well above a billion.
The Bottom Line on Internet Wealth
Parker clearly has built substantial wealth through multiple ventures across decades. But the narrative that he's a self-made billionaire overlooks the role of timing, connections, and the fact that some of his biggest wins came from being early rather than being the primary creator. That distinction matters when you're evaluating whether his success is replicable or dependent on unique circumstances that won't repeat. The internet entrepreneur path isn't closed, but the window for the kind of opportunities Parker exploited has narrowed. Platform regulation, market saturation, and higher barriers to entry make the 2000s style of viral startup building much harder today. Parker's experience remains valuable as a case study, but copying his approach without understanding the specific conditions that enabled it usually leads to disappointing results. His wealth stands as evidence that being early to the right technology with the right network can generate extraordinary returns. It doesn't prove that the same strategy will work for the next generation of founders. The markets have shifted. The regulations have tightened. The competition has intensified. Parker's trajectory was real, but it was also specific to its time.