Local Banking in Columbia, SC: What You Actually Need to Know
State Credit Union has been operating in South Carolina for decades, and if you live around Columbia, it's one of the more common options people consider. I've dealt with enough credit unions across the state to know what works and what doesn't. Let me walk you through the practical side of things. First, let's get the basics straight. State Credit Union (often abbreviated as SCU) is a member-owned financial cooperative, not a bank in the traditional sense. That ownership structure is why rates tend to be better on savings and loans compared to big commercial banks. You're not dealing with shareholders demanding returns. You're dealing with members who set rates among themselves. The membership requirement is the first thing that trips people up. You don't just walk in and open an account because you live in Columbia. Credit unions operate under a field of membership, which for SCU generally includes people who work in certain counties, attend specific schools, or live in defined areas. Richland County is covered, so if you're here, you likely qualify. But the best move is to check their official membership eligibility page before wasting time applying.
I ran into this exact issue a few years back. My partner at the time lived in Lexington County, and we weren't sure if that fell within their membership boundaries. The website wasn't clear about it. We ended up calling the Columbia branch directly, got put through to a membership services rep, and within ten minutes had a definitive answer. Save yourself the confusion. Call before you apply online.
Accounts and Products That Actually Matter
The checking account options are pretty standard. They have a regular share draft account and a premieryouthing account with fewer fees if you meet certain direct deposit or balance requirements. The premieryouthing version usually requires a minimum balance of around $1,500 or a direct deposit of $500 or more per month. If you don't hit either threshold, you'll get hit with a monthly fee that eats into whatever rate advantage the credit union offers. The savings accounts are where credit unions typically beat banks. The regular share account pays somewhere in the 0.10 to 0.50 percent range depending on the current rate environment. Their high-yield savings option can be significantly better, sometimes four to five times the standard rate. This matters more than people realize. On a ten thousand dollar balance, that difference could be forty dollars a year. Not life-changing, but it's free money you'd leave on the table otherwise. Loans are where SCU really differentiates itself. Auto loans, personal loans, and home equity lines tend to come in under comparable bank products by roughly half a percent to a full percentage point on the rate. That might sound small until you run it over a seven-year auto loan or a fifteen-year home equity line. The savings compound in a way that actually shows up in your bank statement.
Get the Full Details
The Digital Experience
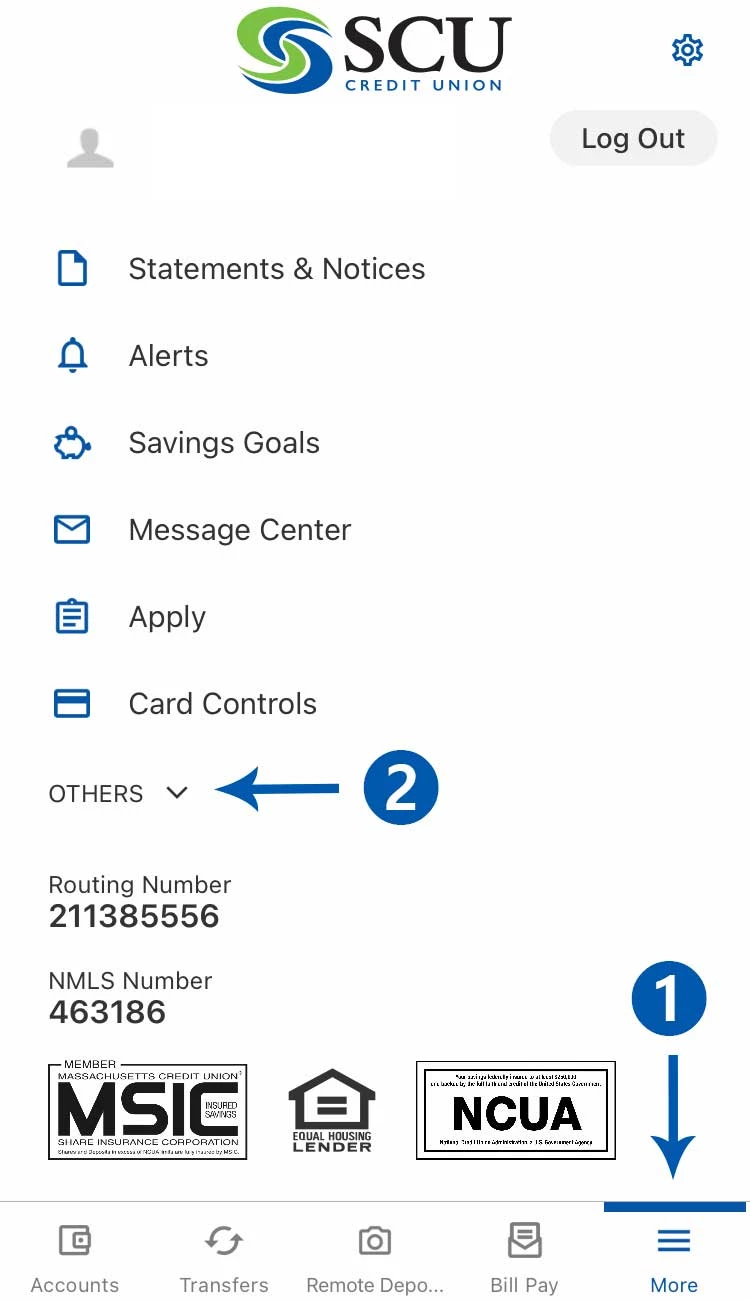
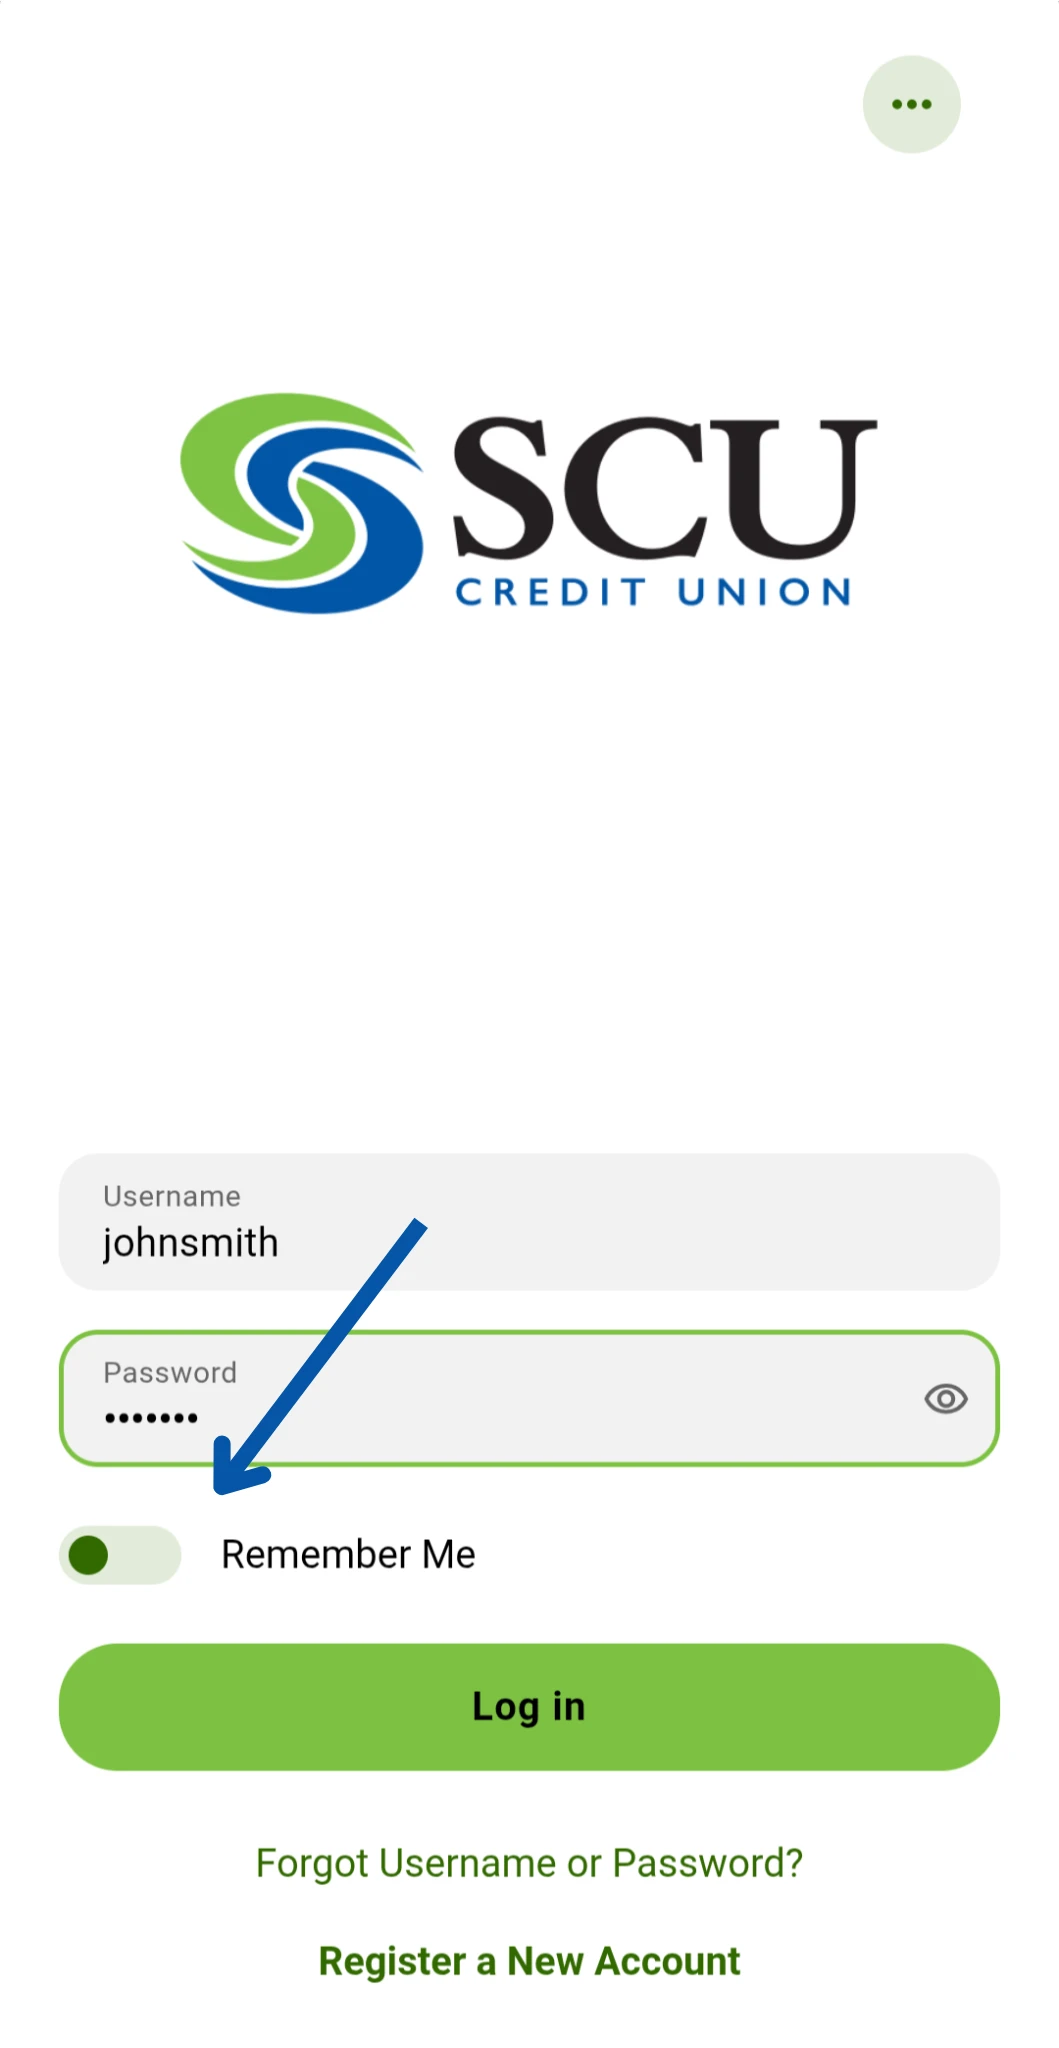
Their mobile app is functional. It's not going to win any design awards, and I've had moments where bill pay took an extra day to process compared to what I'd expect from larger institutions. The core features work though. You can deposit checks, transfer between accounts, pay bills, and set up alerts. The mobile check deposit limit is reasonably generous, but there is a daily and monthly cap. If you're handling something like a property sale or a large settlement, you'll want to know those numbers before you try to deposit everything at once. Online banking login issues come up occasionally. I had a situation where my two-factor authentication kept failing after a password reset, and the automated system was looping me through the same broken path. The workaround was straightforward but not obvious. I called the help desk number printed on the back of my debit card instead of using the in-app support button, and a live person resolved it in about eight minutes. The in-app chat routing seems to default to a bot-heavy system that doesn't handle edge cases well.
Common Mistakes People Make
The biggest one I see is people treating credit unions like banks and expecting the same branch hours. Many SCU branches in the Columbia area close at five on weekdays, and some close early on Fridays. If you work standard business hours and need to make a deposit or get help in person, you're looking at lunch breaks or after-work visits. This is normal for credit unions. It's just something you need to plan around. Another pitfall is the joint account structure. When you open a joint account with someone else, both parties typically have equal access and equal liability. I learned this the hard way when a former business partner had a judgment placed against their share of a joint account, and SCU froze our entire account until the matter was resolved. It took about three weeks to sort out. Joint accounts with non-members of your household are a real legal exposure. Keep those separate. The certificate of deposit ladder strategy works well here, but most people don't use it correctly. They throw money into the longest CD term they can find, chasing the highest rate. What actually works better is staggering your CDs across six-month intervals. That way you have liquidity every half year, and you're not locked into a single rate for three years if rates shift dramatically. This is basic portfolio management, but it surprises me how often I see people ignore it.
When SCU Makes Sense and When It Doesn't
If you're a local resident who values lower loan rates and a community-focused institution, State Credit Union is solid. The staff at the Columbia branches generally knows their stuff, and the customer service response time is reasonable for a mid-sized credit union. You won't get the sprawling ATM network of a national bank, but that's a trade-off you accept. Where it falls short is for people who travel frequently or do business across multiple states. The ATM fee reimbursement policy covers some outsourced network fees, but it has limits. If you're constantly pulling cash from different state's ATMs, those fees add up faster than you'd expect. Similarly, if you need same-day wire transfers or complex international banking features, you'll hit walls. Credit unions simply don't have the infrastructure for that level of financial sophistication. For most people in Columbia, though, SCU does the job well. It's not flashy. The technology lag behind big banks is real, but the rate advantages and the lack of hidden fee structures more than compensate. Just do the membership check first, call before you apply, and set up those alert notifications so you catch any weird activity before it becomes a problem.