So Brexit Happened and Scotland Didn't Like It
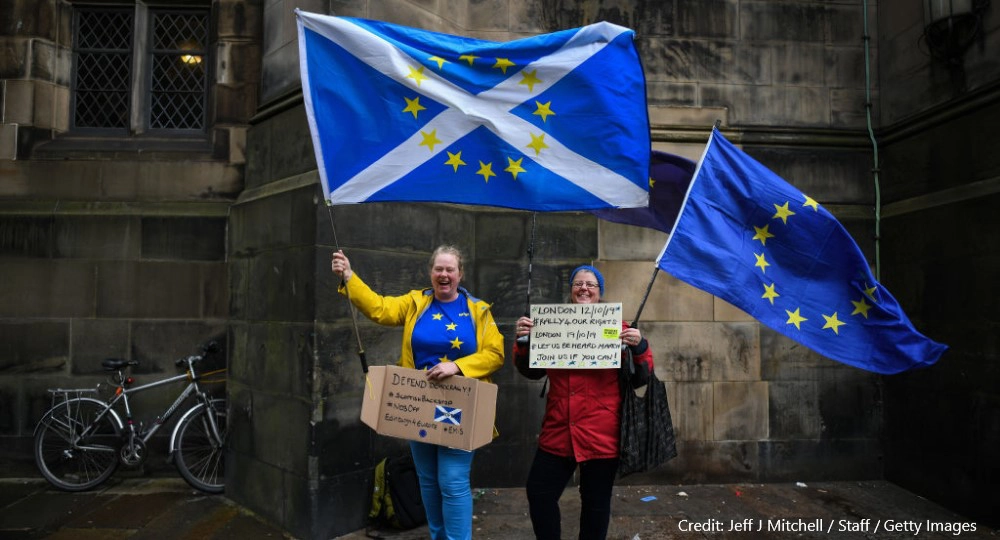
Scotland voted 62% against leaving the European Union in 2016. The UK as a whole voted 51.9% to leave. That gap matters because it became the central tension in Scottish politics for the next half-decade and counting. The independence question didn't go away after the 2014 referendum, which had produced a 55% "No" vote. It just got buried under the sheer mess of what followed. I've been tracking this from the Inside side, not the abstract political-science side. I helped coordinate a small cross-border research project between Edinburgh and Dundee on trade displacement patterns after Brexit. It wasn't glamorous. The data was a nightmare. But it made the abstract argument about Scotland's EU relationship concrete in a way that polling alone never does.
Scottish Independence The Unfinished Business Of Brexit
The core mechanism is straightforward, even if the politics aren't. Scotland, like the whole of the UK, was an automatic member of the EU by virtue of being part of the United Kingdom. When the UK left, Scotland left too — against its democratic will, by its own measure. The Scottish Government's position, since at least 2020, has been that a second independence referendum is justified on those grounds. The UK Government's position, confirmed multiple times including by the Supreme Court in 2022, is that Westminster controls the legal mechanism for such a referendum. Section 30 orders under the Scotland Act 1998 are the actual legal tool here. They temporarily transfer legislative competence over a specific matter — in this case, holding a referendum — to the Scottish Parliament. Without one, the Holyrood government could pass a referendum bill, but UK courts would almost certainly strike it down for exceeding devolved powers. That's what happened in 2022 when Holyrood tried to pass the National Membership of Europe (Scotland) Bill. The Advocate General for Scotland referred it, and the Supreme Court ruled it unlawful in November of that year. The practical reality is that a Section 30 order requires agreement from both governments. The UK Government has refused on multiple occasions. The most recent major attempt was in late 2023, when the Scottish Government proposed a referendum date for autumn 2024. Boris Johnson's successor Liz Truss rejected it within days. By that point, the political landscape had shifted again because the UK had already agreed to the Windsor Framework dealing with Northern Ireland, and the focus had moved toward the 2024 general election. That election produced a Labour government under Keir Starmer, who has consistently said he will not negotiate a Section 30 order while he is chancellor or prime minister.
Here's something most summaries miss. The legal barrier is real but not the primary obstacle. The real question is whether the Scottish Government can maintain a coherence of message and strategy across multiple electoral cycles while the UK Government treats the issue as permanently closed. Labour's position has hardened since 2014. In 2014, many Labour MPs in Scotland supported the union. By 2024, the party had replaced nearly its entire Scottish parliamentary caucus with pro-union candidates and had effectively removed devolution expansion from its agenda. The political cost of even entertaining independence talks within Labour is now extremely high. I ran into a specific operational problem during my research project that illustrates why the "unfinished business" framing, while politically useful, glosses over some messy realities. We were trying to model the trade impact on Scottish food and drink exporters if Scotland re-entered the EU as an independent member state. The EU's own trade database, TradeCOM, doesn't have granular regional data for UK sub-national exports. You get UK-wide figures. So we had to impute Scottish shares based on production data from the Scottish Government's own statistics, adjusted for port and airport export routing patterns. It worked adequately for bulk commodities. For specialty products like single malt whisky, the margins of error got wide fast because a lot of Scottish production ships through English ports and gets recorded as English exports in EU customs data. The workaround was to cross-reference the Scottish Government's annual outward investment survey with HMRC's detailed trade statistics, which do break out Scotland at the product level but only to the 8-digit CN code. It took about three weeks of manual work to reconcile the two datasets, and even then we had to make assumptions about transshipment volumes through Felixstowe and Southampton. This is the kind of detail-level friction that never appears in political rhetoric but determines whether policy proposals hold up under scrutiny.
Get the Full Details

The demographic argument is another area where surface-level reading is misleading. Yes, Scotland's population is aging. Yes, younger voters skew more pro-independence. But the age split isn't as clean as polling suggests. In the 2023 ScotCen survey, respondents aged 18 to 24 supported independence at roughly 58%. Those aged 65 and over were at about 31%. The critical group is 40 to 64, where support drops into the low 40s and varies significantly by region. Highland and island communities, which voted heavily against Brexit, show different patterns than Glasgow or Dundee, where economic anxiety overrides some of the pro-independence lean. A model that treats "young people" as a monolith will overestimate the independence vote in any realistic scenario. The economic dimension has a structural weakness that independence campaigners tend to address with optimism about North Sea revenues and financial services relocation. The counterpoint is equally structural. Scotland runs a fiscal deficit — roughly 8% of GDP according to the Office for Budget Responsibility's 2024 estimates — meaning it receives more from the UK Treasury than it pays in taxes. An independent Scotland would inherit a proportional share of UK debt, estimated by the independent fiscal council Scotland's Economy to be around £17,000 per capita, or roughly £8.5 billion total. That figure changes depending on whether you use a per-capita split, a GDP-based split, or a revenue-based split. The debate over methodology isn't academic. It shifts the starting position by billions and therefore determines whether the remaining fiscal gap looks manageable or severe. Currency choice is another area where the easy answers don't hold. The Scottish Government's 2014 white paper explored three options: retaining the pound sterling without a formal monetary union (the "dollarisation" model), creating a new Scottish currency, or applying to join the euro. None of these are straightforward. The dollarisation model was rejected internally because it means giving up monetary policy control with no seat at the table. A new currency introduces exchange rate volatility during the transition period, which matters enormously for a small open economy. Euro membership is theoretically possible but requires meeting the convergence criteria, and there's no guarantee the EU would accelerate Scotland's accession — other countries have waited years.
The EU membership question itself contains an internal tension. Article 49 of the Treaty on European Union states that any European state may apply to join. Scotland's case would be that it is a European state, that it has a functioning democracy, and that it meets the Copenhagen political and economic criteria. The counter-argument, pushed by Spain and others with separatist movements, is that Scotland isn't a "state" in the relevant sense because it was previously part of another member state and is seeking to separate rather than emerge from colonial rule or foreign occupation. This isn't a fringe position. Spain has explicitly stated it would veto any UK application that involved Scottish independence, and Spain's veto power means unanimous council approval would be impossible. That doesn't mean EU membership is off the table, but it does mean the timeline and conditions are uncertain. The standard accession process takes roughly two years from application to completion under normal circumstances, but political blockage can extend that indefinitely. Croatia took eight years. Turkey has been negotiating for over fifteen. Scotland's case would likely fall somewhere between those extremes, with the Spanish veto as the main variable. On the administrative side, there's a detail most people overlook. If Scotland became independent, it wouldn't just need to establish new institutions. It would need to resolve the status of UK-wide public services that operate across the border. The NHS isn't one system — Scotland's is separate from England's already, which helps. But pensions, the BBC, the Royal Mail delivery network, and the UK's debt obligations all require negotiation. The UK Pensions Service alone holds records for approximately 12 million Scottish contributors to the State Pension and private occupational schemes. Dividing those liability records accurately is an enormous logistical task that has no precedent in modern European history.
I learned this the hard way when a colleague asked me to estimate the administrative timeline for a hypothetical independence scenario. I gave a quick back-of-the-envelope calculation based on the Brexit transition period, which ran for about 11 months from January to December 2021. That was wrong. The Brexit transition dealt with trade and travel. It didn't require splitting pension systems, customs databases, or defense commitments. A realistic estimate for the core institutional setup would be 18 to 24 months of intensive negotiation, followed by another 12 to 18 months of operational adjustment. Anything less and you're gambling with service disruption. The polling has shifted since 2014 but not in a linear way. In the 2014 referendum, independence lost 44.7% to 55.3%. Since then, the gap has narrowed. Late 2023 and early 2024 polling consistently showed independence support in the high 40s, sometimes touching 50%. But polling has a well-documented tendency to overstate support for constitutional change when it's driven by protest sentiment rather than a detailed understanding of the consequences. The 2016 Brexit referendum showed this pattern clearly — early polling had Remain leading by double digits, and the final result was a narrow Leave victory. Scotland-specific polling carries the same uncertainty. The turnout factor is also critical. In 2014, turnout was 84.6%. A subsequent referendum would almost certainly see lower turnout, possibly in the 65 to 70% range, based on the 2021 Scottish Parliament election (46.2%) and the 2023 local elections (39.2%). Lower turnout favors the status quo because disengaged voters tend to default to the existing arrangement. That's a structural disadvantage for the independence campaign that gets underplayed in political analysis.
The broader Brexit context continues to shape this issue in ways that go beyond the simple "Scotland voted to stay" narrative. The post-Brexit trade arrangements with Northern Ireland, the retention of UK-wide regulations in devolved areas, and the UK Internal Market Act all constrain Holyrood's policy space in ways that some independence advocates argue prove their case — that Scotland is better off outside the UK framework entirely. Others counter that the constraints are reversible through devolution expansion, not independence. Both positions have evidence behind them. Neither is resolved. The practical takeaway is that the question of Scottish Independence The Unfinished Business Of Brexit remains unresolved because there is no legal pathway that both sides accept and no political moment that both sides see as favorable. The mechanism exists — a Section 30 order — but the agreement required to trigger it hasn't materialized. The public opinion exists in a narrow and volatile band. The institutional and economic complexities are real and understated in public debate. The EU membership question is theoretically answerable but politically contingent in ways that make timing unpredictable. None of this means independence is impossible. It means the path is narrower and more conditional than the political rhetoric often suggests. The next general election in the UK, scheduled for 2029 at the latest, will be the next major inflection point. How Labour performs in Scotland, whether the SNP maintains its parliamentary presence, and what the EU's posture is toward a potentially smaller, poorer applicant state will all determine whether the question moves from stalled to active.