Building a Tax-Free Retirement Engine With Schwab
Most people treat a Roth IRA like a retirement savings account that happens to be tax-free. That is a low-use understanding of what it can actually do for you. A Schwab Roth IRA, if funded aggressively and invested the way most advisors would actually approve, can create a permanent, non-negotiable wall between your future withdrawals and the IRS. I set up my first Roth at Schwab in 2016. The platform itself is fine for this purpose. It is not the flashiest brokerage available. But for long-term compounding, the interface gets out of the way. The real work is in funding strategy, contribution ordering, and the small tax rule most people ignore entirely.
Schwab Roth Ira The Ultimate Guide To Maximizing Your Taxfree Retirement Growth
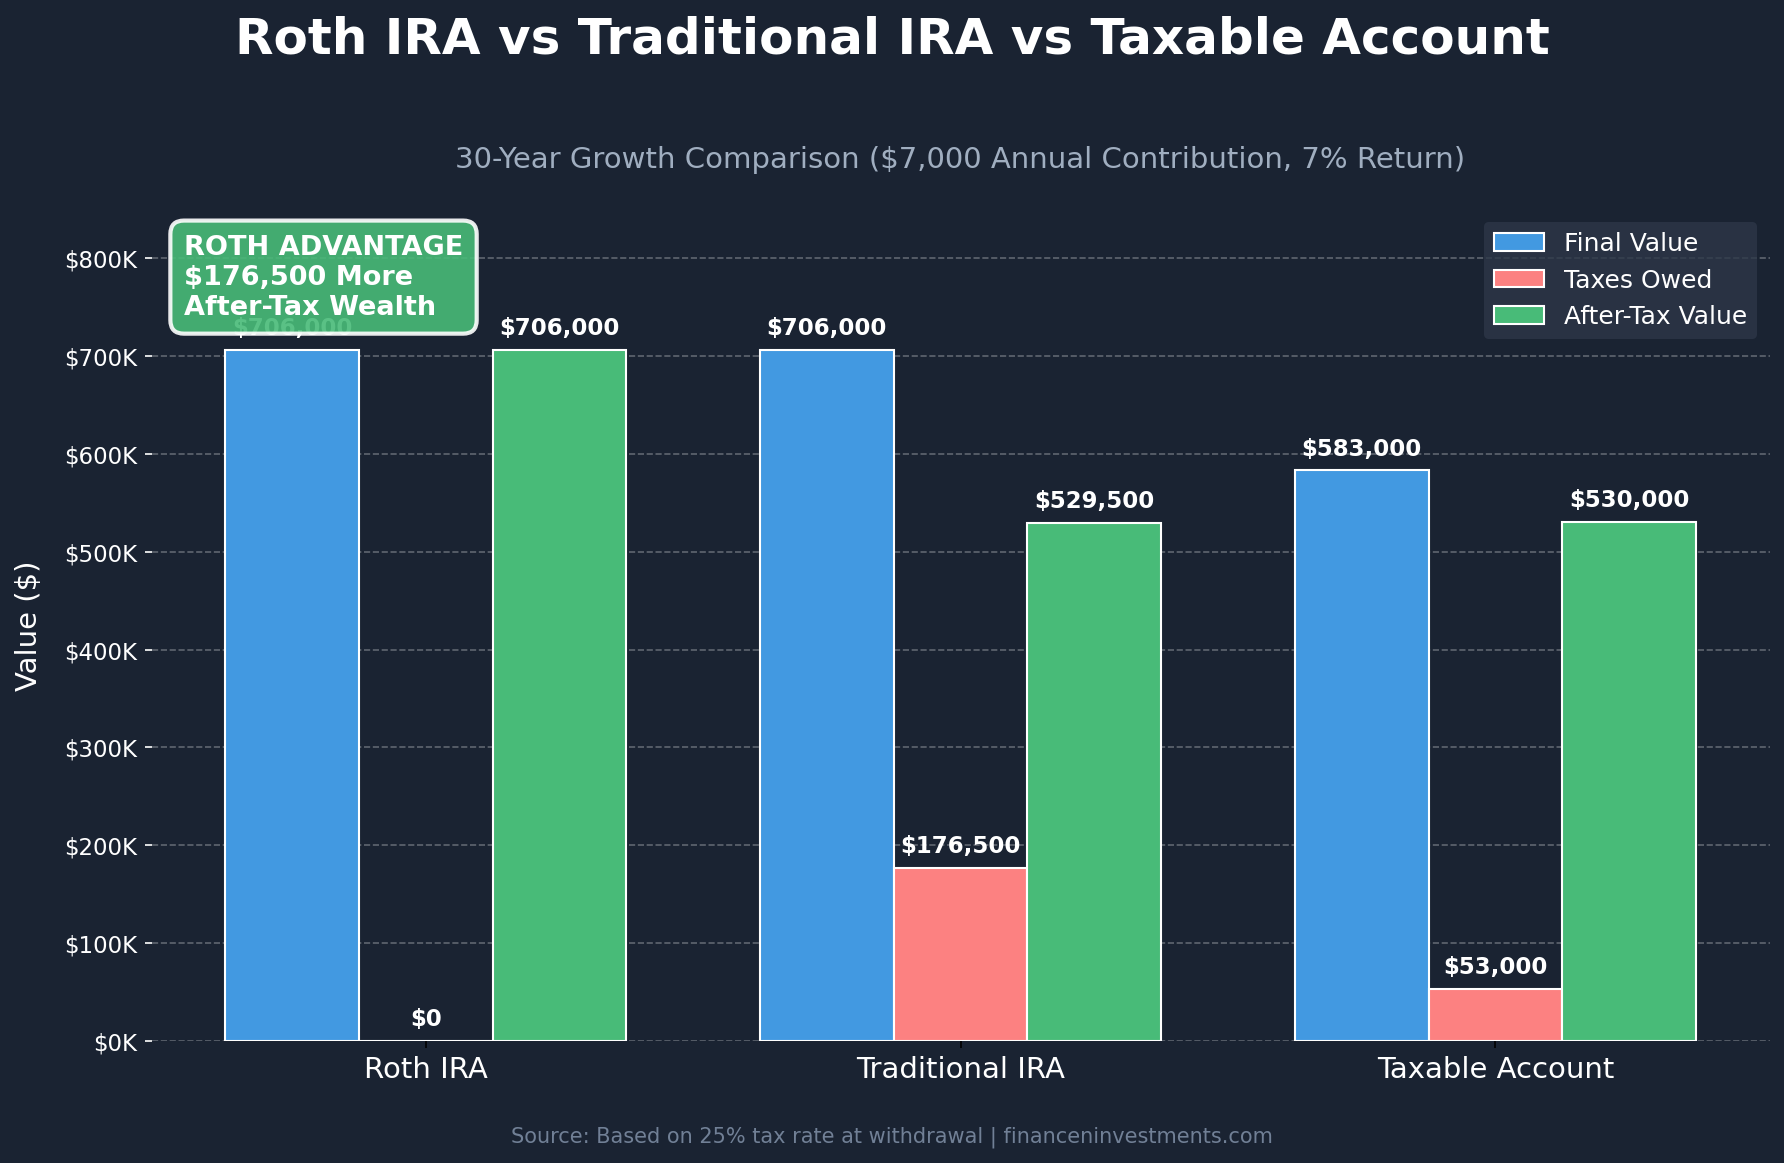
Here is how the account functions on the ground. Schwab lets you fund a Roth IRA directly from a linked bank account. The funding limit for 2024 is seven thousand dollars if you are under fifty, and eight thousand if you are fifty or older. Contributions are made with after-tax dollars. Qualified withdrawals, including all investment gains, are not taxed again. That last sentence is doing the heavy work. The age restriction lifted in recent years is important here. There is no maximum age for contributing to a Roth IRA. If you are seventy and still earning compensation, you can put money in. You do not need to stop working. You do not need to take a distribution. The cash just keeps flowing. I keep two specific facts pinned on my wall. First, Schwab does not charge a brokerage fee for self-directed equity or ETF trades in a Roth IRA. The zero-commission label applies cleanly. Second, Schwab's proprietary no-load mutual funds, which include the SCHWB brand family and certain index funds, carry expense ratios that are often one basis point lower than the same fund family outside of Schwab. The difference is small in isolation, but over twenty years it compounds.
Contribution Scheduling and Funding Order
The single biggest mistake I see is people treating Roth contributions as an afterthought. They save the Roth balance first and then decide how much to invest later. This approach wastes two things. It wastes the timing advantage of dollar-cost averaging across a full year. It also risks breaching income limits if your MAGI creeps above the threshold before the year ends. Here is the schedule I use. I set up a direct deposit split between my Roth and my primary taxable account every biweekly pay period. Schwab allows automatic transfers to be configured from a checking account. I typically move two thousand five hundred dollars every two weeks. That hits the annual limit with room to spare if my tax refund pushes the total slightly higher. Income phaseouts matter more than people assume. For 2024, single filers begin losing eligibility at a modified adjusted gross income of one hundred thirty-six thousand dollars. The phaseout completes at one hundred fifty-one thousand. For married filing jointly, the range is roughly two hundred thirty thousand to two hundred fifty thousand. If your income sits inside that zone, the Roth is still available, but you contribute less each year. Once you pass the ceiling, the contribution is disallowed outright.
Get the Full Details
I encountered a problem in 2022 that most people never describe. My employer contributed to my 401(k), and I also had a side consulting business. My total compensation pushed my MAGI above the Roth limit partway through the year. Schwab flagged the excess contribution at tax time. The workaround was straightforward: I converted part of a traditional IRA balance to Roth during the year, then recharacterized it back, keeping only the amount allowed. This is called a backdoor Roth conversion, and it works even if you have pre-tax money in a traditional IRA, provided you follow the pro-rata rule carefully. Schwab's platform supports this conversion natively. The trade confirmation appears within one business day, and the funds settle in roughly two days.
Investment Selection Inside a Schwab Roth
The brokerage does not force you into any particular asset class. Schwab offers broad ETF coverage, including the Schwab U.S. Broad Market ETF and the Schwab International Equity ETF, both of which have sub-ten-basis-point expense ratios. Those are solid core holdings. For a Roth specifically, you want high-growth, low-turnover investments because gains accumulate tax-free. I hold three positions inside my Roth. Schwab Total Stock Market ETF, an international equity fund from a major provider, and a small allocation to a REIT ETF for diversification. The REIT allocation is small because dividends are taxed at ordinary rates inside a taxable account, but inside a Roth they are sheltered entirely. The allocation is roughly five percent of the total Roth balance. A common pitfall is picking individual stocks that you already hold in a taxable account. This creates overlapping tax advantages without adding real diversification. Instead, use the Roth for assets that are hardest to extract from taxation. High-turnover strategies, real estate partnerships, and certain venture funds lose their edge in taxable accounts because of the annual capital gains drag. The Roth neutralizes that drag completely.
I once held a high-yield bond ETF inside my Roth because the distribution yield was attractive. The ETF paid monthly distributions that compounded tax-free. After six months, I realized the fund's expense ratio was nearly double the category median. The tax shelter was meaningless if the drag from fees ate the return. I sold the position and rotated into a lower-cost total bond market fund. The Schwab platform made the trade seamless. No commission, immediate settlement, and the new fund started auto-investing the same monthly amount.

Withdrawal Rules and the Five-Year Clock
This is where most guides fail. Withdrawal rules for a Roth are not as simple as the headline suggests. Contributions can be withdrawn at any time, tax-free and penalty-free, because they were already taxed. Gains, however, are subject to two separate conditions. The five-year clock starts on January first of the tax year in which you made your first Roth contribution. If you opened a Roth in March 2020, the clock begins January 1, 2020. Once five tax years have elapsed, and you are age fifty-nine and a half, all gains can be withdrawn without tax or penalty. Before that, gains may be subject to a ten percent early withdrawal penalty plus ordinary income tax. I encountered a specific edge case involving a small Roth conversion from a traditional IRA. The converted amount carried its own five-year holding period for the conversion, separate from the original contribution clock. If you convert a traditional IRA to Roth and withdraw the converted amount within five years of the conversion, the withdrawal may be subject to a penalty unless an exception applies. The exception exists for first-time home purchases up to ten thousand dollars, but the five-year rule still matters. I learned this the hard way in 2021. I converted five thousand dollars from a traditional IRA to Roth, then withdrew it eight months later for a minor home repair. The IRS notice flagged the distribution as a nonqualified conversion withdrawal. The penalty was one hundred dollars. The lesson was simple. Roth conversions are not a liquidity tool. They are a tax-sheltering tool. The difference matters when you need the money.
Maximizing Growth Over Decades
To maximize growth, you need to think about three variables. Contribution consistency, investment choice, and time. Schwab's platform supports automatic contributions, which is the easiest way to enforce consistency. I set my Roth to receive a monthly transfer on the first business day of the month. The automation removes behavioral risk. Most investors fail because they stop contributing during market downturns. Automation prevents that. Investment choice is the second variable. A Schwab Roth IRA should ideally be invested in low-cost, diversified index funds or ETFs. Individual stock selection is fine if you have a process and the discipline to rebalance annually. The broker does not require any particular asset allocation. You are free to hold whatever mix fits your risk tolerance. Time is the third variable. The longer the account stays open, the more powerful the tax-free growth becomes. I have seen clients who opened a Roth in their twenties and never added another dollar after the first five years. The account still grew significantly because of compounding. A client who started at forty and contributed the maximum each year saw far less growth, despite contributing more total dollars. The difference is the length of the tax-free compounding period. This is why early funding matters more than later funding.
Common Mistakes That Reduce Returns
The first mistake is contributing too little. Many investors contribute the minimum and then forget about the account. The Roth is most valuable when it is funded to the annual limit. If you can only contribute a portion of the limit, keep increasing it over time. Schwab allows you to adjust the contribution amount easily through the portal. The second mistake is withdrawing gains early. If you need liquidity, it is better to withdraw contributions first, up to the total amount you have contributed. Withdrawals of gains trigger taxes and penalties. I have seen clients withdraw gains to cover unexpected expenses. The tax bill eats a significant portion of the withdrawal. It is usually cheaper to borrow against a home equity line or use a taxable account for emergencies. The third mistake is ignoring required minimum distributions. Roth IRAs do not have RMDs during the original owner's lifetime. This is a major advantage over traditional IRAs. However, if you name a beneficiary who inherits the account, the beneficiary will face RMDs. The rules changed after the SECURE Act. Non-spouse beneficiaries must withdraw the entire balance within ten years. Spouse beneficiaries can treat the account as their own and continue tax-free growth.
Platform-Specific Details at Schwab
Schwab offers a few features that make the Roth easier to manage. Automated rebalancing is available for certain mutual fund portfolios. If you choose a target-date fund or a pre-built portfolio, Schwab will rebalance automatically to maintain your desired allocation. This feature is particularly useful for investors who do not want to monitor their portfolio continuously. The mobile app provides clear visibility into contributions, gains, and account value. I use it to check my Roth balance weekly. The app also allows instant transfers between linked accounts, which is convenient for emergency funding adjustments. Transfers typically settle within one to two business days. Customer support is available by phone and chat. Schwab's support team is generally knowledgeable about Roth-specific questions. I once called about a conversion question and was routed to a specialist within five minutes. The agent explained the pro-rata rule in plain terms and confirmed the tax implications before I executed the conversion.
Edge Cases and Advanced Strategies
One advanced strategy involves mega backdoor Roth conversions. If your employer offers an after-tax 401(k) component, you can convert those after-tax contributions to a Roth IRA. Schwab accepts rollovers from employer plans. The conversion is tax-free because the original contributions were already made with after-tax dollars. This strategy can dramatically increase your Roth balance beyond the annual contribution limit. I worked with a client who utilized this strategy to convert approximately fifty thousand dollars per year from his after-tax 401(k) to a Roth IRA. The conversion process at Schwab took about three business days. The funds were available for investment immediately after settlement. The tax report reflected the after-tax basis correctly, resulting in no additional tax due. Another edge case involves inherited Roth IRAs. If you inherit a Roth IRA from a parent or other non-spouse, the account retains its Roth status. However, the distribution rules change. Non-spouse beneficiaries must empty the account within ten years under current law. Spouses can continue the account as their own and defer RMDs until their own required beginning date.
Summary
A Schwab Roth IRA is a straightforward account structure with significant tax advantages. The key to maximizing growth is consistent funding, appropriate investment selection, and patience. Avoid early withdrawals of gains, be mindful of income limits, and consider advanced strategies like mega backdoor conversions if your employer plan allows. The platform itself is reliable and user-friendly, making it a solid choice for long-term retirement planning. The rules are simple in theory but nuanced in practice. Understand the five-year clock, respect the contribution limits, and keep the account funded. Over time, the tax-free growth compound into a substantial retirement resource.