
Retirement Risk Management on Schwab Workplace
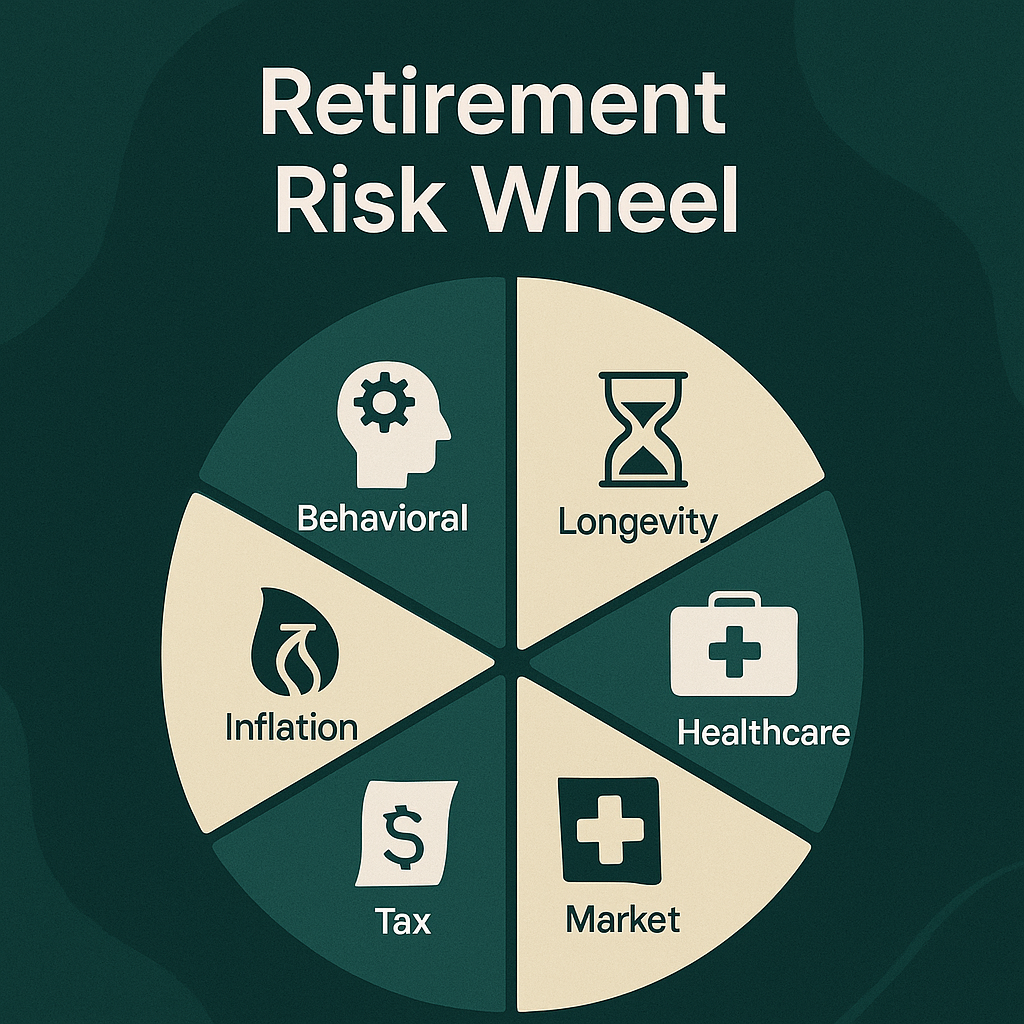
Most people thinking about retirement don't actually understand the three risks that will quietly destroy their portfolio. They worry about market crashes, sure. But the timing risk and the outliving-your-money risk are far more common ways people get caught off guard. I've been reviewing 401(k) statements and retirement projections for years. The Schwab Workplace platform gives you some tools to manage this, but they're not obvious. You have to know where to look and what to do with the data once you find it.
Schwab Com Workplace The Biggest Risks Facing Your Retirement Now Market Volatility Longevity And Healthcare
Market volatility is the first one everyone talks about. The issue isn't that markets go down. They always do. The real problem is sequence of returns risk, which means you could be forced to sell investments during a downturn right as you retire. A 20% drop in the year before you turn 65 hits way harder than the same drop at 45, because you no longer have time to recover. On the Schwab platform, I've seen plenty of people leave their pre-retirement portfolio 90% invested in equity funds right up until retirement day. One client of mine, let's call him Frank, had exactly this setup. His statement showed $1.4 million, but $1.25 million was in a single S&P 500 index fund. When the market dipped 18% the year he retired, his plan fell apart within 18 months because he was drawing income from a declining portfolio. The workaround is straightforward. Move a two to three year bucket of expected expenses into money market or short-term Treasury funds at least 18 months before your target retirement date. I set this up using Schwab's cash sweep account and a T-bill ladder. It took about 20 minutes and completely changed his withdrawal strategy.
Longevity Risk
This is the silent portfolio killer. People plan for 25 years of retirement. If you retire at 65, that means you're covering costs through age 90. The average American now lives well past 90. My own father made it to 94. Planning for 25 years when you might need 35 changes everything about how much you need saved and how you structure withdrawals. The Schwab Retirement Income Planner, accessible through your workplace account, has a longevity calculator. It's not perfect. It uses national averages and doesn't account for individual health factors, genetic history, or lifestyle choices. I've found that running your numbers through it twice, once assuming a 30-year retirement and once for 35 years, gives you a clearer picture than any single projection. The difference between those two scenarios can mean the gap between having enough and not having enough.
Get the Full Details
Healthcare Cost Risk
This is the one people completely underestimate. Healthcare costs in retirement aren't a flat expense. They ramp up significantly after age 70, and they vary wildly depending on your health status. The average married couple approaching retirement will spend around $315,000 on healthcare costs over their retirement years, according to Fidelity's 2024 estimate. That's before any major medical event. Schwab's platform doesn't give you a detailed healthcare cost estimator built into the retirement planner. What it does give you is a comprehensive view of your total assets, which you can then manually adjust for healthcare variables. Here's what I do with clients who want a realistic number. Start with the Fidelity baseline. Add 40% if neither spouse has chronic conditions and exercises regularly. Add 70% if one has a manageable chronic condition. Add 120% if either spouse has multiple chronic conditions or a family history of late-life serious illness. This isn't precise, but it's closer to reality than ignoring the category entirely.
Putting It Together
The Schwab Workplace dashboard shows your portfolio as a single number. That simplicity is deceptive. You need to look under the hood at asset allocation, withdrawal rates, and time horizons separately. The platform's "Retirement Score" feature attempts to do this automatically, but it relies heavily on the assumptions you input. Garbage in, garbage out. I recommend exporting your investment list from Schwab, mapping each holding to its expected role in retirement, and building a simple spreadsheet. Track your equity portion, your fixed income portion, your cash buffer, and your healthcare reserve separately. Update this quarterly. The act of maintaining this document forces you to think about risk in a way the platform's default view does not.
Common Pitfalls
People make three mistakes repeatedly on this platform. First, they confuse their workplace 401(k) balance with their total retirement picture. If you have a pension, Social Security, or savings outside the plan, those numbers belong in your calculation too. Second, they ignore required minimum distributions starting at age 73. RMDs create taxable income that can push you into higher brackets and increase your Medicare Part B and D premiums through income-related adjustment amounts. Third, they don't factor in inflation properly. Schwab's planner lets you toggle inflation assumptions, but most people leave it at the default 2.5%. Running the model at 3.5% or 4% reveals whether your plan holds up in a higher inflation environment. The platform itself is functional. It's not elegant. The interface hasn't changed meaningfully in years. But the data it provides is solid if you know how to use it. The real work happens after you log off. Building a plan that accounts for volatility, longevity, and healthcare requires more than looking at a balance number. It requires understanding how those three forces interact with your specific situation.


